
What Rexel Doubters Got Wrong
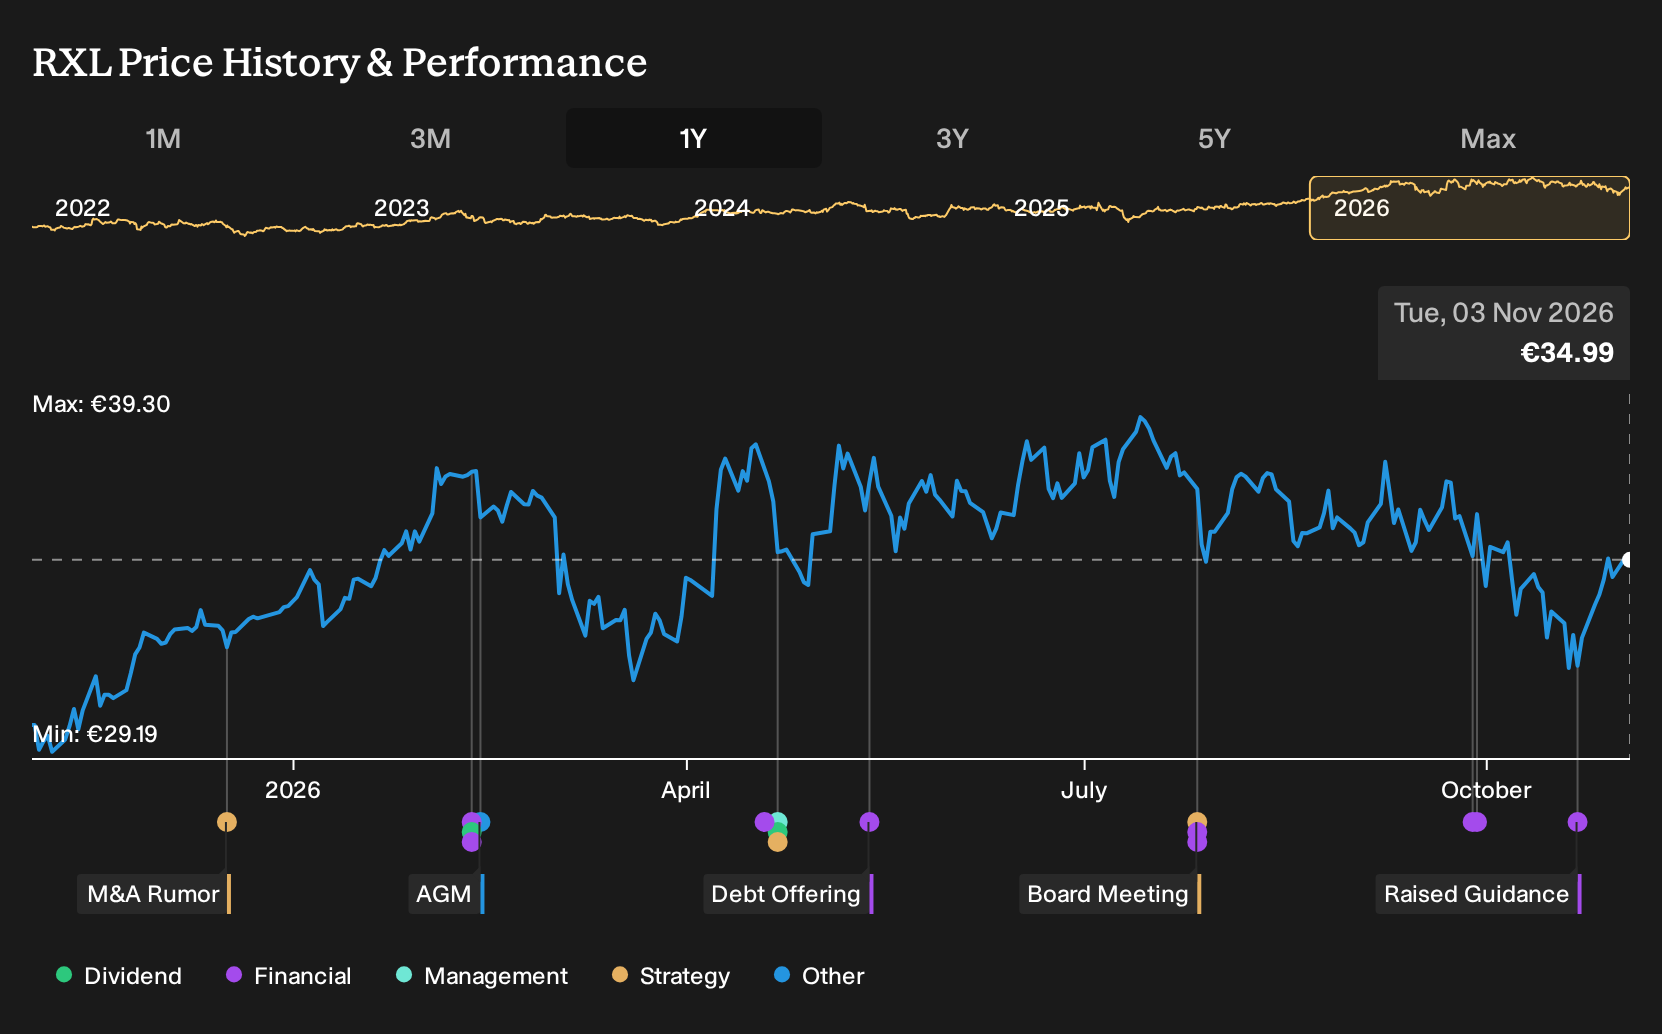
If you watched Rexel ramp up acquisitions in North America and deepen its push into data centers and broadband back in late 2025, the choice was not straightforward. Investors who held Rexel over the past year are up 23.5%, including dividends. If you had been weighing those expansion plans against warnings about weak European construction and margin pressure, which side of that debate would have seemed more convincing at the time?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Rexel is not the only name tied to this theme. Zero in on 41 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Rexel Stories Investors Were Arguing About
The shares cost €30 at the start of the period, so anyone looking at Rexel then had to decide whether the price already captured the potential in electrification and digital expansion or still left room for upside.
The bullish Narrative put Fair Value at €33. It leaned on assumptions that Rexel could use electrification, infrastructure projects, digital sales and AI-led productivity to support faster revenue growth and higher net margins over several years.
The cautious Narrative set Fair Value at €28.32. That view treated 3.4% annual revenue growth and a 4.1% profit margin as realistic assumptions while flagging weak European demand, competitive pressure and elevated financial leverage as key risks.
What The Rexel Evidence Put To The Test
The GCG wire and cable deal, backed by a €500 million equity raise and extra debt funding, gave clear support to the bullish Rexel story about using North American acquisitions and infrastructure exposure. Measured results also mattered. Revenue moved from €9,775.3 million in H1 2025 to €9,988.9 million in H1 2026, while net margin rose from 2.7% to 3.4%. The evidence supported the optimistic case.
The hinge assumption was that expansion would translate into better profitability, not just more scale. For any other distributor, you would stress test that same claim by tracking net margin alongside acquisition spend and capital raises rather than just watching sales growth.
What Rexel's Recent Run Now Prices In
Rexel now trades at €34.99, and the selected Narrative sees its Fair Value below that level, framing the stock as broadly in line with what cautious analysts think the business can deliver on current plans.
The Narrative leans on real digital productivity gains but worries about large project exposure and the GCG deal. For today’s price to add up, a buyer would need confidence that North American projects, GCG integration and Axelerate 28 efficiencies all keep landing close to plan.
"Although Rexel is increasing its exposure to North American infrastructure projects through acquisitions like GCG, the heavier tilt toward large engineered projects in data centers, power and utilities and defense could leave the business more vulnerable if project pipelines slow or are repriced. This would weigh on revenue growth and pressure EBITA margins."
One Narrative disagrees with today's price. → See where this Narrative says Rexel should trade
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 36% below our estimate - builds on demand as coconut water replaces traditional sugary sports drinks.
- Company 2 - 31% below our estimate - captures automatic payroll deferrals as more employers adopt default retirement plan enrollment.
- Company 3 - 41% below our estimate - scales late stage treatments aimed at maintaining revenues as key protections expire.
That is three of the list. See every one of the 194 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com