
Great Wall Motor (SEHK:2333) Profit Slide Keeps Valuation In Focus
Great Wall Motor (SEHK:2333) has just reported nine month 2026 earnings, showing revenue of CNY 159,868.71 million but a sharp decline in net income to CNY 3,826.12 million, which is intensifying investor focus on profitability.
Recent trading shows that sentiment around Great Wall Motor has cooled, with the share price declining 12.26% over the past 30 days and falling 58.83% year to date. This has contributed to a 57.23% drop in 1 year total shareholder return as investors reassess earnings risks against new energy and overseas growth efforts.
Compare Great Wall Motor's reset expectations with other auto stocks investors are watching by scanning our hand picked 194 high quality undervalued stocks in the sector.
Great Wall Motor now trades well below both analyst targets and one estimate of intrinsic value after a steep share price reset. Does that gap mark a genuine discount or a fair reflection of thinner profits?
Price-to-Earnings of 9x: Is it justified?
Great Wall Motor changes hands at a P/E of 9x, which lines up with a share price of HK$6.23 that screens as cheap against both peers and its own fair ratio benchmark.
The P/E ratio compares what investors pay today for each unit of current earnings. For an auto manufacturer like Great Wall Motor, where profitability can swing with product cycles and pricing pressure, this yardstick helps you gauge how much of those earnings the market is willing to value right now.
On one hand, the stock is described as good value versus the Asian auto sector, where the average P/E is 13.1x, and it also looks inexpensive compared to a peer group average of 22.1x. On the other hand, the P/E of 9x sits above the estimated fair P/E of 8.2x, which indicates the market is still assigning a richer multiple than that model suggests and leaves room for the ratio to compress toward that lower level if earnings quality or growth delivery disappoint.
Explore the SWS fair ratio for Great Wall Motor.
Result: Price-to-Earnings of 9x (ABOUT RIGHT)
Still, Great Wall Motor faces pressure if new energy investments weigh on margins or if overseas expansion requires heavier spending before earnings catch up.
Find out about the key risks to this Great Wall Motor narrative.
Another View: DCF Points to Deep Discount
A different lens on Great Wall Motor comes from the SWS DCF model, which puts fair value at HK$23.67 per share against the current HK$6.23 price. That implies the stock trades about 73.7% below this estimate. Is that a genuine mismatch, or just a model leaning too hard on optimistic assumptions?
Look into how the SWS DCF model arrives at its fair value.
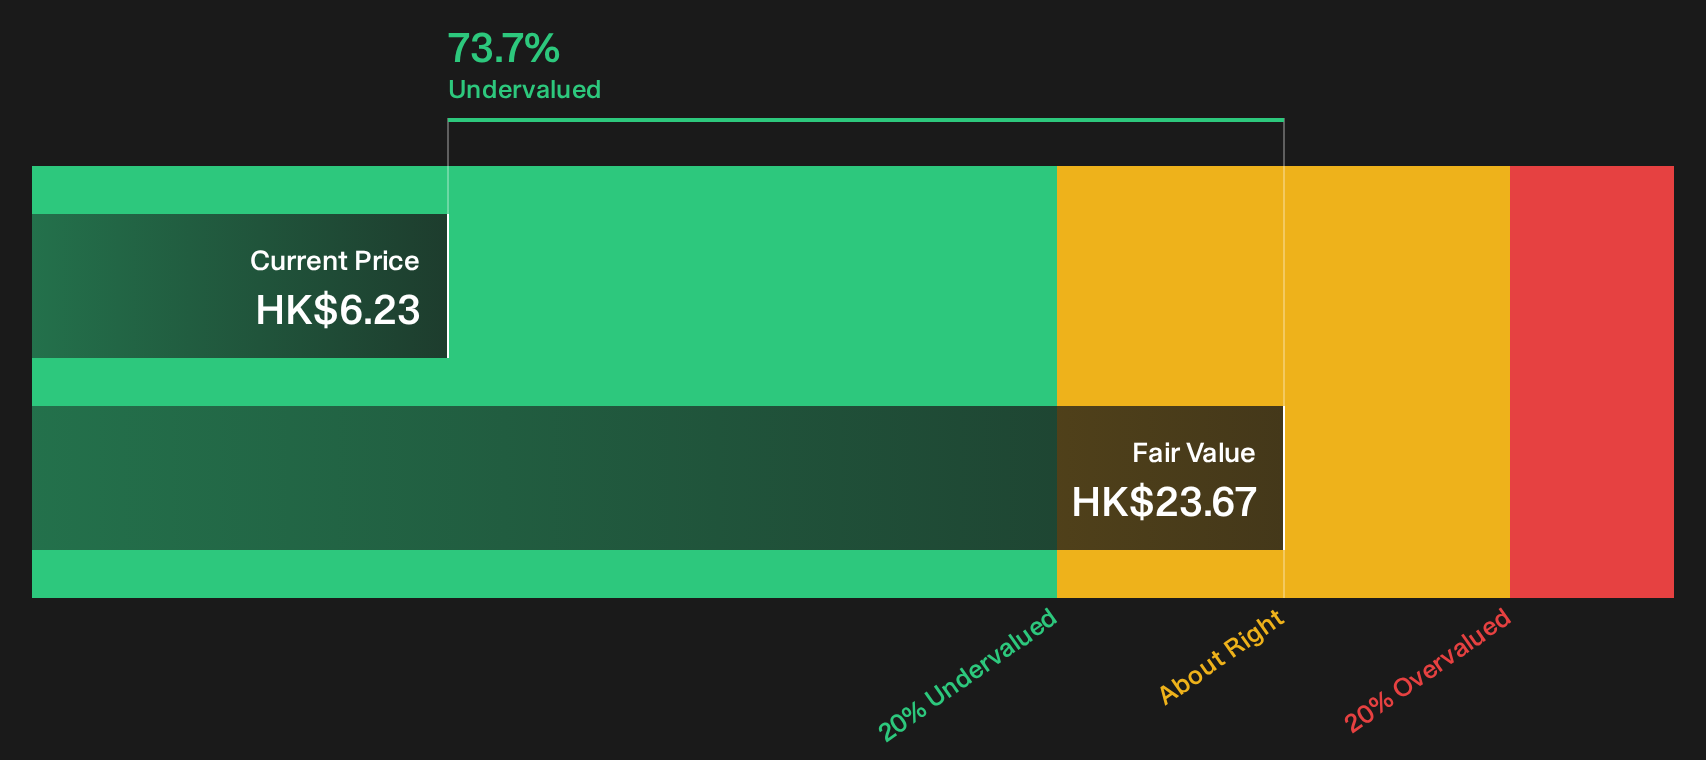
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Great Wall Motor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data can make Great Wall Motor feel tricky to judge, so move fast, pull up the full picture yourself, then weigh the 2 key rewards and 3 important warning signs
Looking for more Great Wall Motor sized ideas?
If you stop with Great Wall Motor, you risk missing other opportunities. Use the Simply Wall Street Screener to spot candidates that better match your style and risk limits.
- Target income resilience by reviewing stocks that qualify as 216 dividend fortresses and see which payouts have the fundamentals to back them.
- Spot sturdier businesses early by scanning our list of solid balance sheet and fundamentals (196 results) so you are not caught off guard by weak finances.
- Hunt for potential upside by filtering through 604 high quality undiscovered gems before broader attention moves the prices away from your comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com