
Lower Mortgage Rate Hopes Could Be A Key Test For KB Home Stock (KBH)
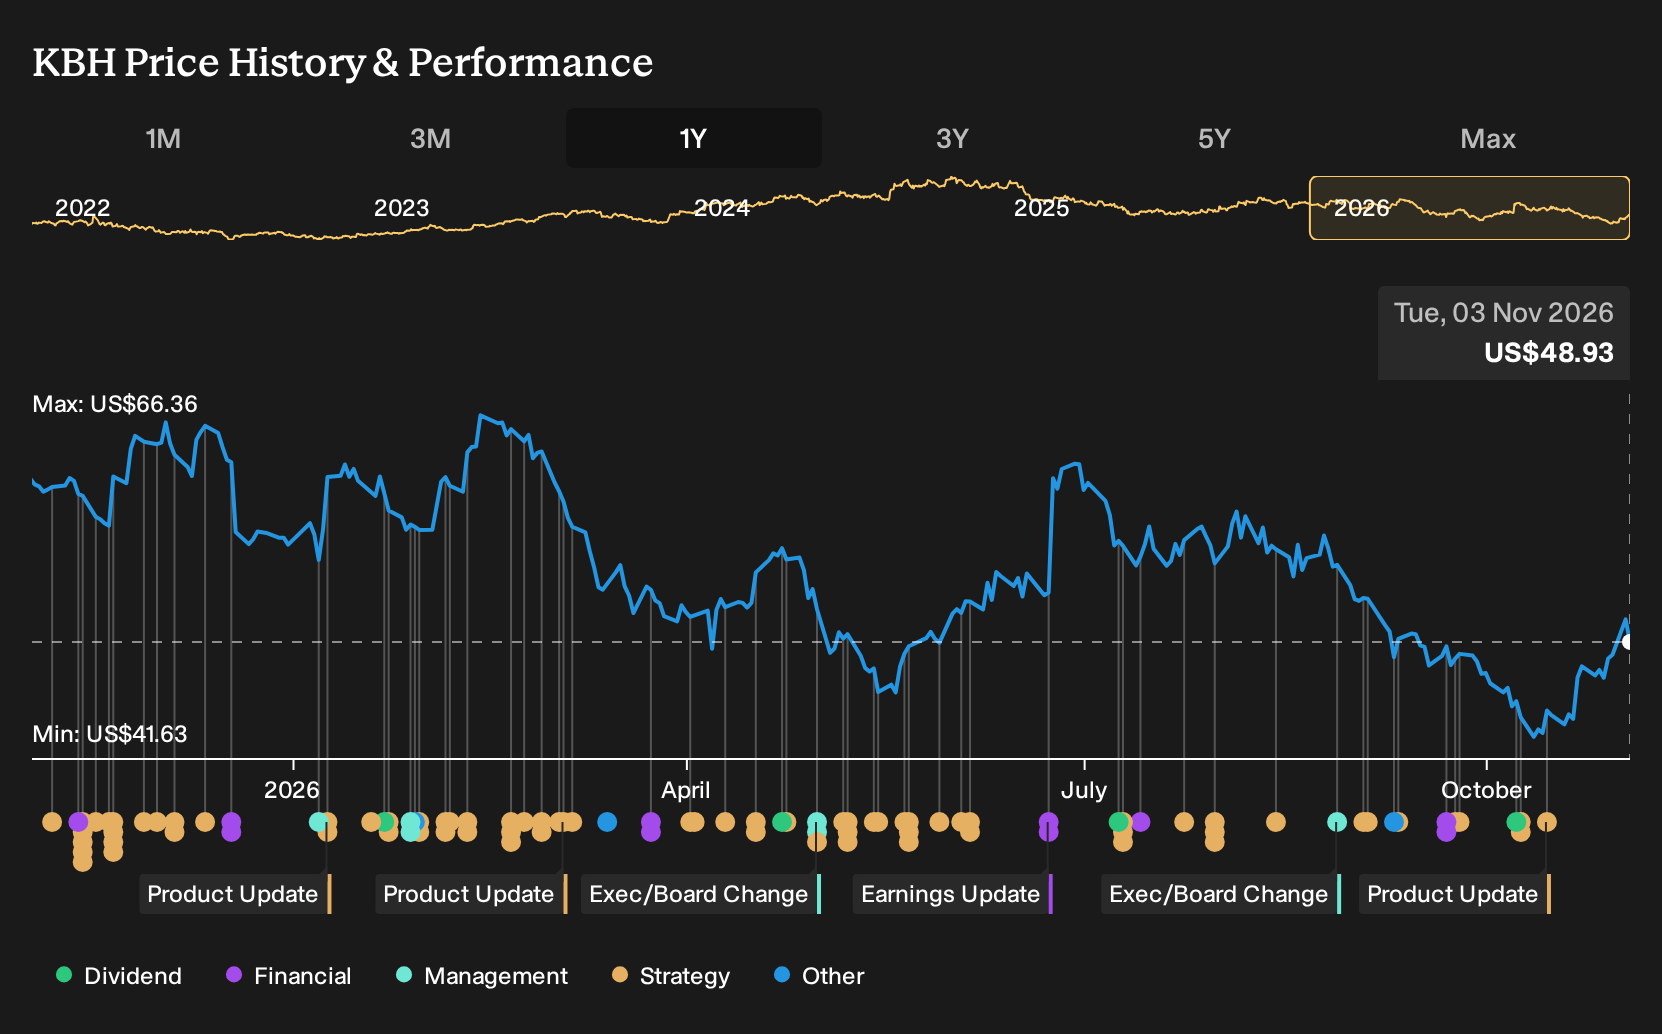
- KB Home recently benefited from a sector wide rally in homebuilders after reports of a possible reopening of the Strait of Hormuz suggested some relief for inflation and mortgage costs.
- The reaction highlights how sensitive KB Home’s order pipeline and pricing power can be to shifts in borrowing costs and broader housing demand expectations.
- We will now explore how this shift in rate expectations intersects with KB Home's investment narrative around build efficiency and land discipline.
Compare KB Home's rate sensitive set up with other builders by scanning the list of solid balance sheet and fundamentals (23 results) that could be better positioned if borrowing costs stay higher for longer.
KB Home Investment Narrative Recap
To own KB Home, you need to believe its faster build times, large lot pipeline and Built to Order focus can offset a softer demand backdrop and margin pressure. The recent move in KB Home after the Hormuz headlines ties directly into that belief, since lower borrowing costs would support orders and reduce the need for heavy incentives.
The key near term swing factor is whether buyer sentiment and order trends stabilize without eroding pricing too far. The biggest risk remains a prolonged period of weak demand and elevated resale inventory, which could force deeper price cuts, pressure housing revenues and weigh further on already compressed profit margins.
The most relevant recent development is the shift in market expectations around KB Home’s earnings. Estimates have been revised down and now point to lower near term earnings and revenue versus the prior year. That reset matters because it frames how much improvement investors now expect from build efficiency, product mix and land deployment.
When analysts trim forecasts while the stock trades at what is described as a discount to peers, the focus swings back to execution. For KB Home, that means turning its 61,000 plus lot position and quicker 99 to 108 day Built to Order cycles into steady deliveries, while managing debt coverage, incentives and construction costs if demand remains choppy.
KB Home Analyst Expectations and Implied Setup
KB Home's narrative projects US$5.5b revenue and US$275.1m earnings by 2029. This assumes 2.1% yearly revenue growth and an earnings increase of about US$48.7m from US$226.4m today.
Uncover why KB Home's fair value indicates a 5% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate KB Home angle is pure optimism on earnings power. Before the Hormuz headlines, the most bullish analysts were penciling in roughly US$5.8b revenue and about US$340.6m earnings by 2029. That is a much more upbeat story than consensus, and this fresh rate shock could easily push both narratives in new directions. Explore them.
Explore 2 other KB Home fair value estimates, including one that suggests as much as 5% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your KB Home research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for KB Home. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KB Home's overall financial health at a glance.
Looking for more KB Home sized investment ideas?
If the KB Home story has sharpened your thinking about risk, balance sheets and interest rate sensitivity, you can apply that same lens across the wider market with the Simply Wall St Screener.
- If you want potential upside with some quality guardrails, start with companies flagged as 19 high quality undiscovered gems that pair solid fundamentals with less crowded attention.
- For readers who care most about resilience, focus on businesses in the 30 resilient stocks with low risk scores that score well on financial health and earnings stability.
- If balance sheet strength is your top filter, broaden your watchlist through the list of solid balance sheet and fundamentals (23 results) where leverage and liquidity metrics are front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com