
Telkom Indonesia Shares Slid Even Though Sales Rose
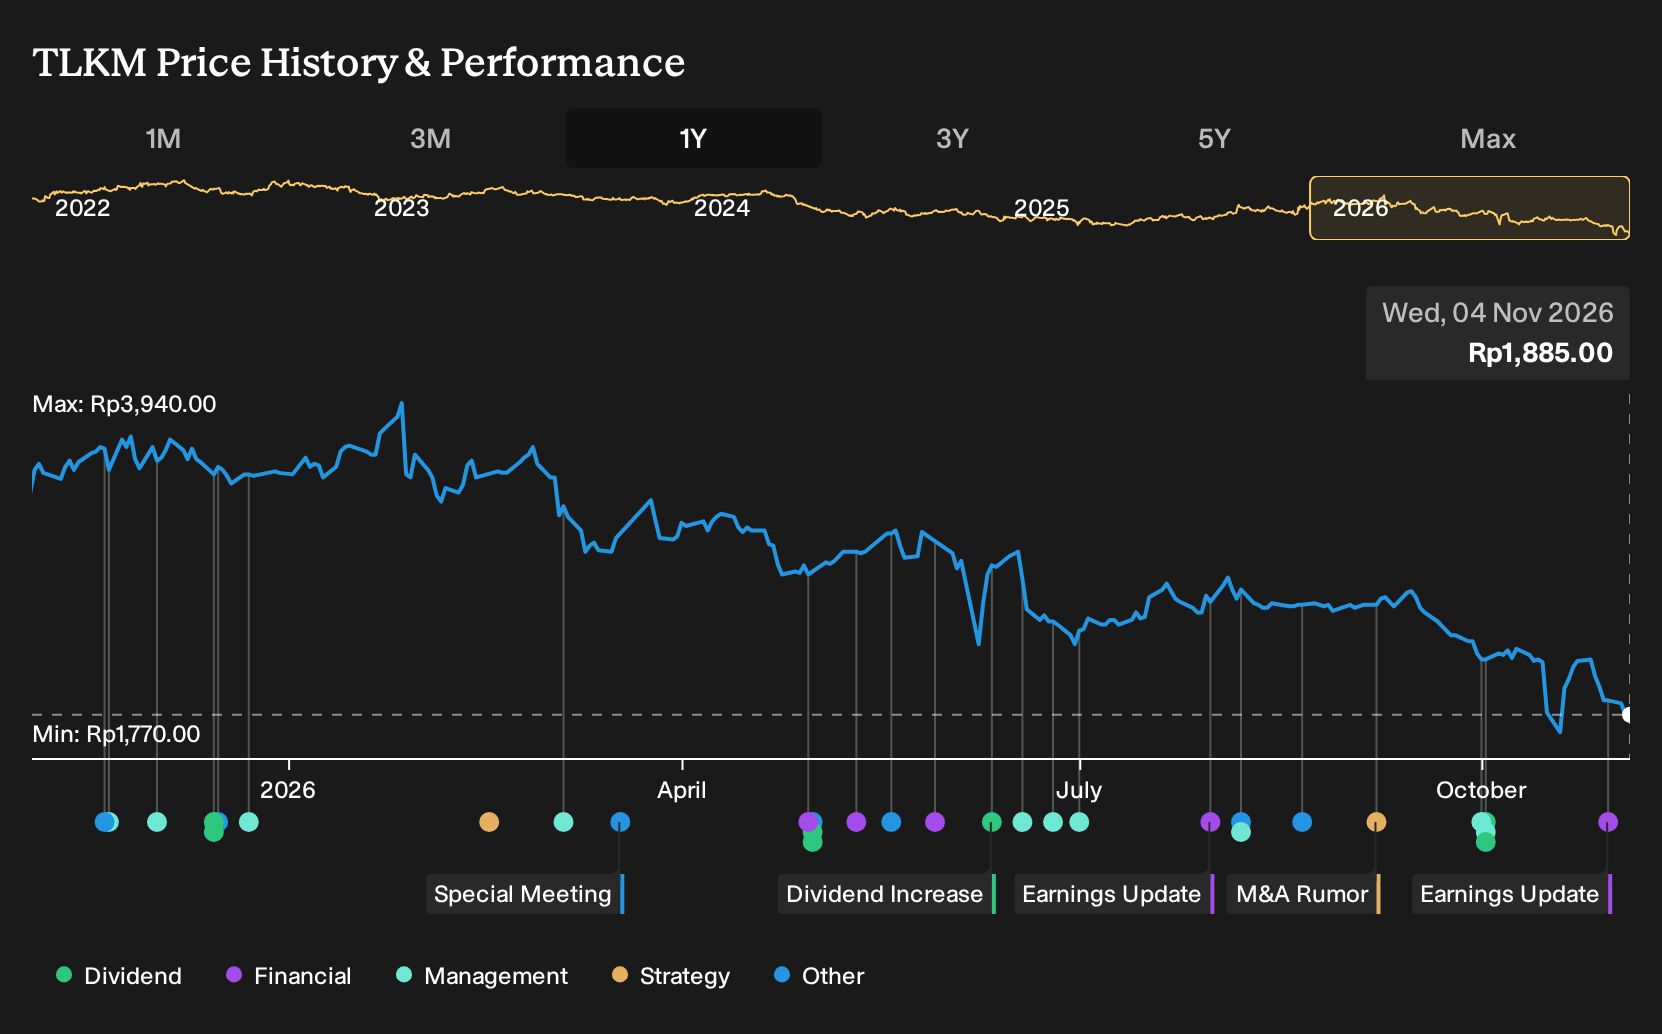
If you backed Telkom Indonesia for its digital and IoT promise, the past year will have felt very different on your statement. For Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia shareholders, the loss over the past year was 42.4%, including dividends. Q3 2026 results showed higher revenue alongside a lower net margin, which sharpens the question: if you bought into the bullish 2025 forecasts on convergence, data centers and digital platforms, what crucial risk or assumption did that original case overlook?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia. Zero in on 194 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Telkom Indonesia
The shares cost IDR3,500 at the start of the period, and investors in Telkom Indonesia faced two very different stories that both sounded reasonable.
The bullish narrative, published in June 2025, put fair value at IDR3,720 and leaned on fast fixed mobile convergence uptake and lower CapEx intensity below 17% of revenue as the foundation for higher margins and free cash flow.
The bearish case from October 2024 set fair value at IDR3,034 and rested on TLKM being screened as cheap on P/B, with a 12.3% revenue growth assumption and a 12.6x future P/E as key inputs.
What The Results Changed For Telkom Indonesia
Q3 2026 put hard numbers against the Telkom Indonesia story. Revenue reached IDR37,624,000m, higher than Q3 2025, yet net income slipped to IDR3,823,000m and net margin moved from 12.4% to 10.2%. The margin compression challenged the bullish case that leaned on expanding profitability and stronger free cash flow, so the evidence leaned toward the cautious narrative.
The key assumption was margin resilience during digital expansion. For any other telecom, you would track net margin alongside capital spending and see whether higher digital revenue is actually converting into stronger profitability rather than just higher top line.
What Today's Telkom Indonesia Price Already Assumes
Telkom Indonesia now trades at IDR1,885, with the recent Narrative placing its Fair Value above that quotation based on its own framework.
The argument focuses on fixed mobile convergence, group procurement and digital infrastructure as potential supports for margins and earnings. A buyer today would need to believe those efficiency gains and data center driven revenues can more than offset legacy pressures and high operating costs.
"Continued strategic initiatives such as group procurement processes to lower CapEx and improve content cost efficiency should significantly increase net margins and earnings due to the lowering of operational expenses. Expansion in the B2B segment, focusing on digital connectivity supported by platform expansion, particularly data centers and cloud services, points to potential sustainable revenue growth and improved earnings as these sectors offer higher margins."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 33% below our estimate - shapes high-efficiency AI data centre hardware focused on power and GPU constraints.
- Company 2 - 49% below our estimate - shifts intensive AI and cloud security spending toward recurring subscription revenue on core platforms.
- Company 3 - 46% below our estimate - converts long standing forensic software customers to higher priced AI supported subscription contracts.
That is three of the list. See all 196 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com