
Is Duke Energy (DUK) Cheap On Regulatory Filings Or Already Fairly Valued?
Duke Energy (DUK) is back in regulatory paperwork mode after its Carolinas and Progress units filed detailed updates with federal energy regulators to support an internal corporate reorganization.
For investors watching the tape, Duke Energy’s share price has eased 1.5% in the latest session to US$126.51, yet the 10.9% 1 month share price return and 7.7% year to date share price gain sit alongside a 5.8% 1 year total shareholder return, indicating near term momentum that has cooled while remaining supported over longer horizons as regulatory filings, Florida rate relief and steady financial updates reset expectations around both growth potential and perceived risk.
Scan how Duke Energy compares with other regulated utilities by running the curated 41 power grid technology and infrastructure stocks for potential power grid and infrastructure opportunities tied to similar regulatory and rate stories.Duke Energy has run hard over the past month, then paused on the latest regulatory headlines. The key question now is whether that cooldown is a chance to step in or a signal to wait for cheaper terms.
Most Popular Narrative: 6% Undervalued
Duke Energy’s most followed valuation storyline pegs fair value at about $133.94, a touch above the latest $126.51 close, which frames the recent pullback as a modest discount rather than a deep bargain.
Major economic development wins in Duke Energy territories, including large data center projects, are now supported by about 7.6 to 7.8 GW of executed electric service agreements and a 15.4 GW late stage pipeline that is expected to be fully contracted by the first half of 2027, which could translate into multi year load growth and higher regulated revenue as this contracted demand is served.
See why 94 investors see Duke Energy as 6% undervalued.
Result: Fair Value of $133.94 (UNDERVALUED)
Still, the story can change quickly if higher interest costs continue to weigh on utility valuations or if future equity issuance dilutes Duke Energy’s per-share earnings power.
Find out about the key risks to this Duke Energy narrative.
Another View: Duke Energy Through A Cash Flow Lens
The story looks different when switching from analyst targets to the SWS DCF model. On that framework, Duke Energy at US$126.51 screens as overvalued against an estimated future cash flow value of US$101.03. That gap raises a simple question: Is the current price baking in more optimism than the cash flows support?
Look into how the SWS DCF model arrives at its fair value.
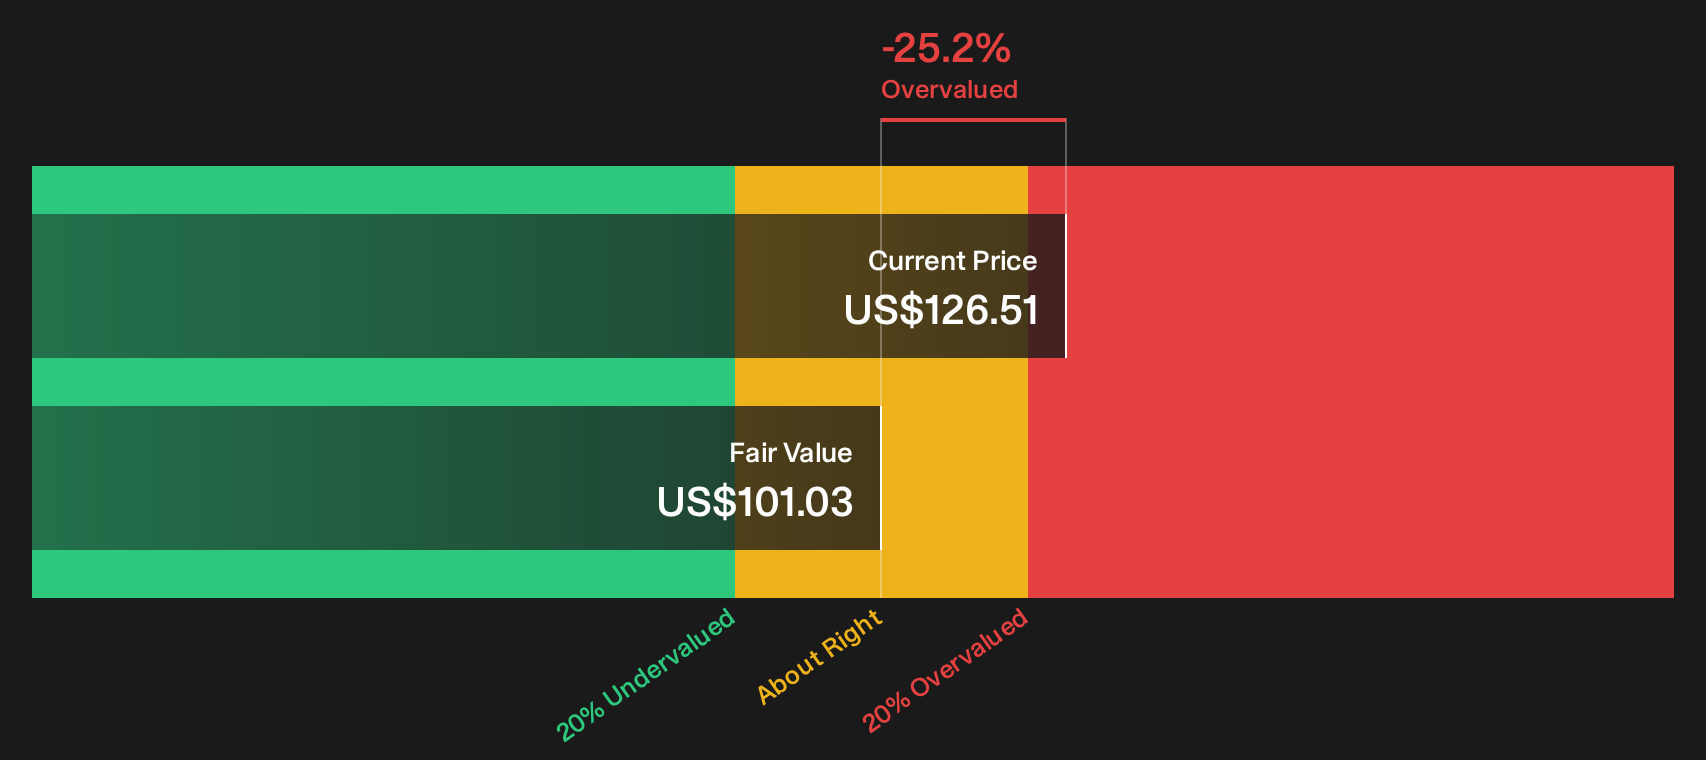
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duke Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Duke Energy’s value story can be useful when you test the numbers yourself and move quickly to lock in your own conclusion. To see both sides of the debate in one place, start with 4 key rewards and 2 important warning signs.
Looking for more Duke Energy style investment ideas?
Do not stop your research with Duke Energy. Broaden your watchlist with targeted screeners that surface different types of opportunities before other investors focus on them.
- Target potential mispricing by running the 35 high quality undervalued stocks that highlights companies combining solid fundamentals with prices that sit below their assessed worth.
- Explore potential income streams by scanning the 4 dividend fortresses built around higher yielding payers with a focus on stability.
- Prioritise resilience by using the 30 resilient stocks with low risk scores that concentrates on businesses with lower risk scores and steadier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com