
Could Centre Pompidou Deal Change The Bull Case For JCDecaux Stock?
- JCDecaux Artvertising has been chosen by the Centre Pompidou to supply advertising and artistic installations around the museum’s renovation works, creating an outdoor cultural route and contributing to funding until the venue’s planned reopening in 2030.
- The partnership gives JCDecaux a high profile cultural showcase for its out of home formats, testing how art focused installations can attract audiences and advertisers around a long running urban construction site.
- We will now look at how this long term Centre Pompidou art partnership could influence JCDecaux's broader investment narrative.
Scan JCDecaux's art focused move at the Centre Pompidou against other out of home and urban infrastructure plays by reviewing our curated 41 power grid technology and infrastructure stocks
JCDecaux Investment Narrative Recap
An investor in JCDecaux needs to believe that outdoor advertising keeps gaining budget share and that the shift to digital and programmatic formats translates into durable cash generation. The Centre Pompidou partnership and recent Artvertising win speak more to branding and format experimentation than to an immediate earnings driver, so the near term economic impact looks limited.
The key short term swing factor still sits in execution on new concessions and digital rollouts, where start up phases can pressure margins and cash flow. The biggest risk remains weak demand in markets such as China, combined with high capex needs and regulatory limits on digitisation in countries like France.
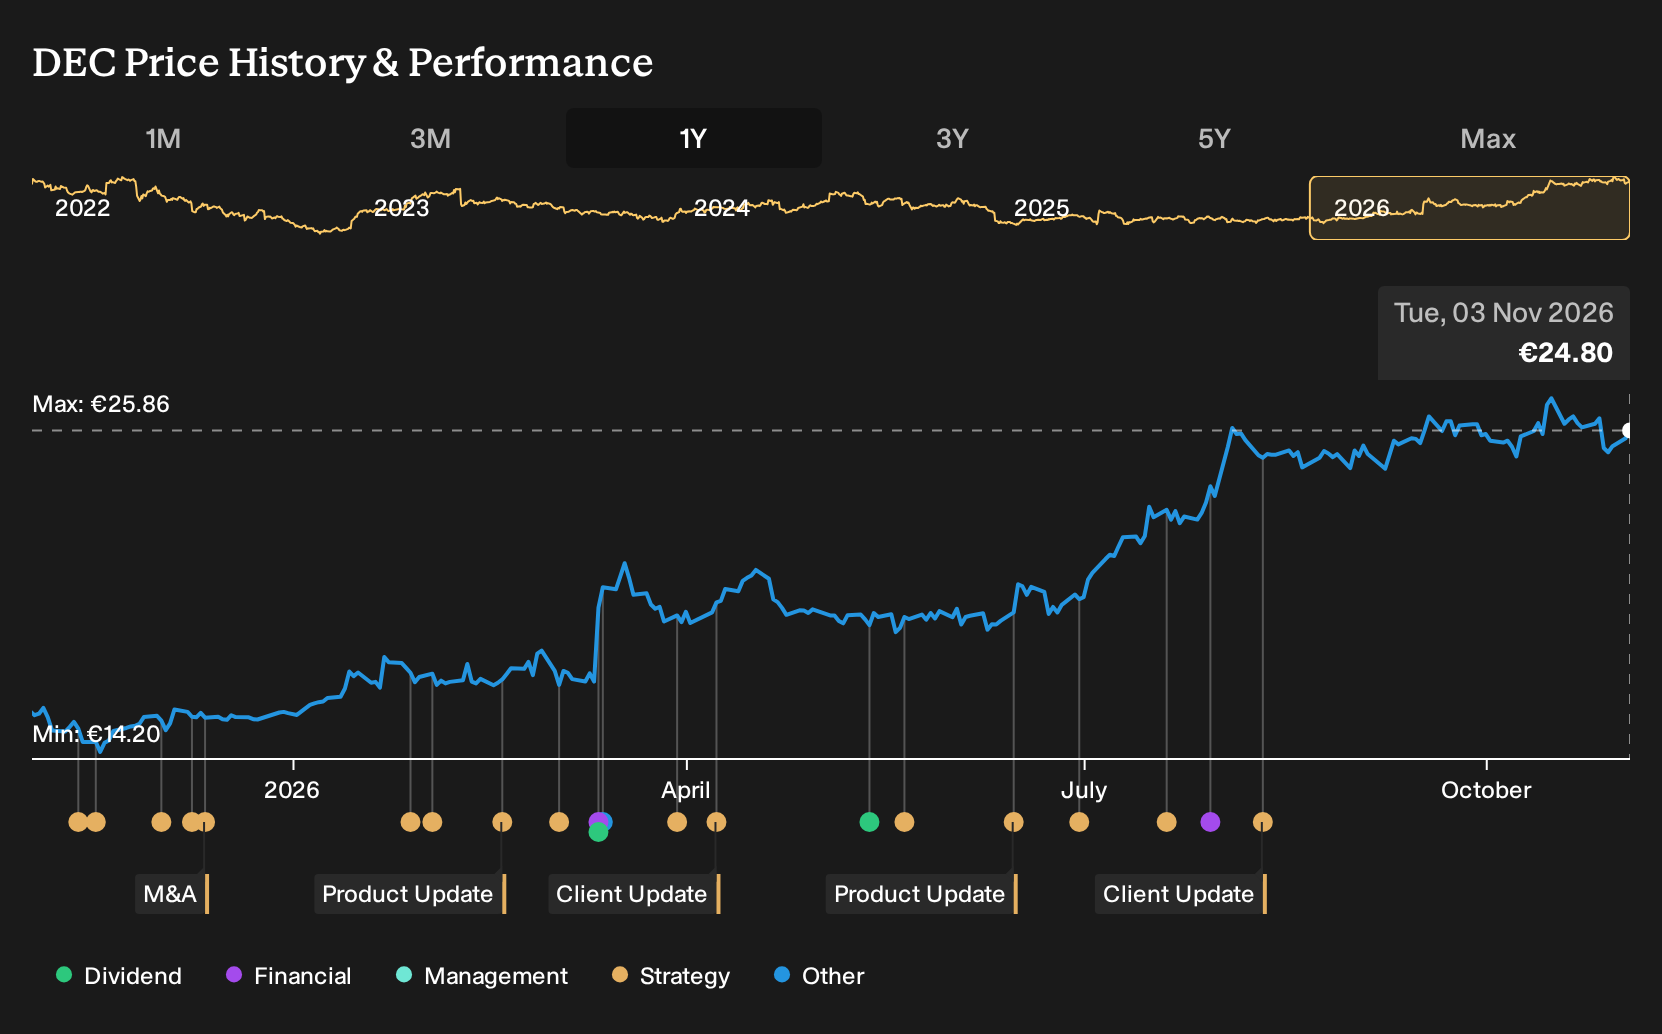
The recent disclosure of JCDecaux’s transactions in its own shares is the most relevant adjacent announcement. It indicates ongoing engagement with capital structure at a time when the share price has risen strongly over one year and currently trades on a P/E above both peer averages and some fair value estimates.
For you as a shareholder or prospective investor, the combination of the Artvertising projects, the self reported share transactions and the SBTi approved carbon trajectory creates a tight focus on execution. The linkage between premium sites such as Centre Pompidou, programmatic expansion and future free cash flow remains the core operational catalyst to watch.
JCDecaux's current analyst story points to revenues of €4.8b and earnings of €368.6m by 2029, based on forecast revenue growth of 8.7% per year and an earnings increase of about €41.8m from earnings today of €326.8m.
Discover why JCDecaux's fair value indicates a 13% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
One alternate angle you might consider focuses on earnings pressure rather than digital upside. The most cautious analysts, who were expecting 8.1% annual revenue growth to about €4.7b and earnings of €353.8m by 2029 before this JCDecaux Artvertising news, see limited room for disappointment. You could read the Centre Pompidou win and decide those earlier, more pessimistic assumptions now look too harsh, or you might view it as evidence that opinions on JCDecaux can differ widely and therefore merit a closer look from you.
Explore 3 other JCDecaux fair value estimates, including one that suggests as much as 56% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your JCDecaux research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JCDecaux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JCDecaux's overall financial health at a glance.
Looking For More JCDecaux Style Ideas?
If JCDecaux has sharpened your interest in how different businesses convert long term projects into potential shareholder value, it can help to set it alongside a wider watchlist. The Simply Wall St Screener lets you quickly compare balance sheets, income profiles and risk levels so you can see which other companies deserve a place on your radar.
- If capital preservation is a priority, consider stocks with steadier profiles by reviewing a curated set of 222 resilient stocks with low risk scores that may suit a more cautious approach.
- If you want potential value on your side, check companies that combine fundamentals with appealing pricing by scanning our 194 high quality undervalued stocks for ideas that might complement JCDecaux in a portfolio.
- If you prefer businesses that already show solid finances, broaden your research with a list of solid balance sheet and fundamentals (196 results) to see which tickers pair stronger balance sheets with underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com