
Is Emerson Electric (EMR) Priced For Too Much Good News?
Emerson Electric has rewarded long term holders with a strong run, which naturally raises a sharper question for new money coming in today. With the share price now well above levels of a few years ago, the key issue is whether that current tag is still aligned with what the business earns.
- Over the past 3 years the stock has delivered a 106.5% total return, which puts real pressure on the idea that earnings power has kept pace with the market's enthusiasm.
- Fresh financial results and an increased cash dividend signal management confidence and may support investor expectations for steadier profit and cash generation ahead.
- Your read on Emerson Electric is one view; the desks covering it have another. See what analysts think Emerson Electric's shares could be worth.
The issue now is whether Emerson Electric's present share price can be squared with its earnings when judged against a Fair Ratio benchmark.
If you are weighing Emerson Electric after this strong 3 year run, it can help to compare it with other industrials by starting with a focused list of 41 power grid technology and infrastructure stocks.
Is Emerson Electric Getting Expensive on Earnings?
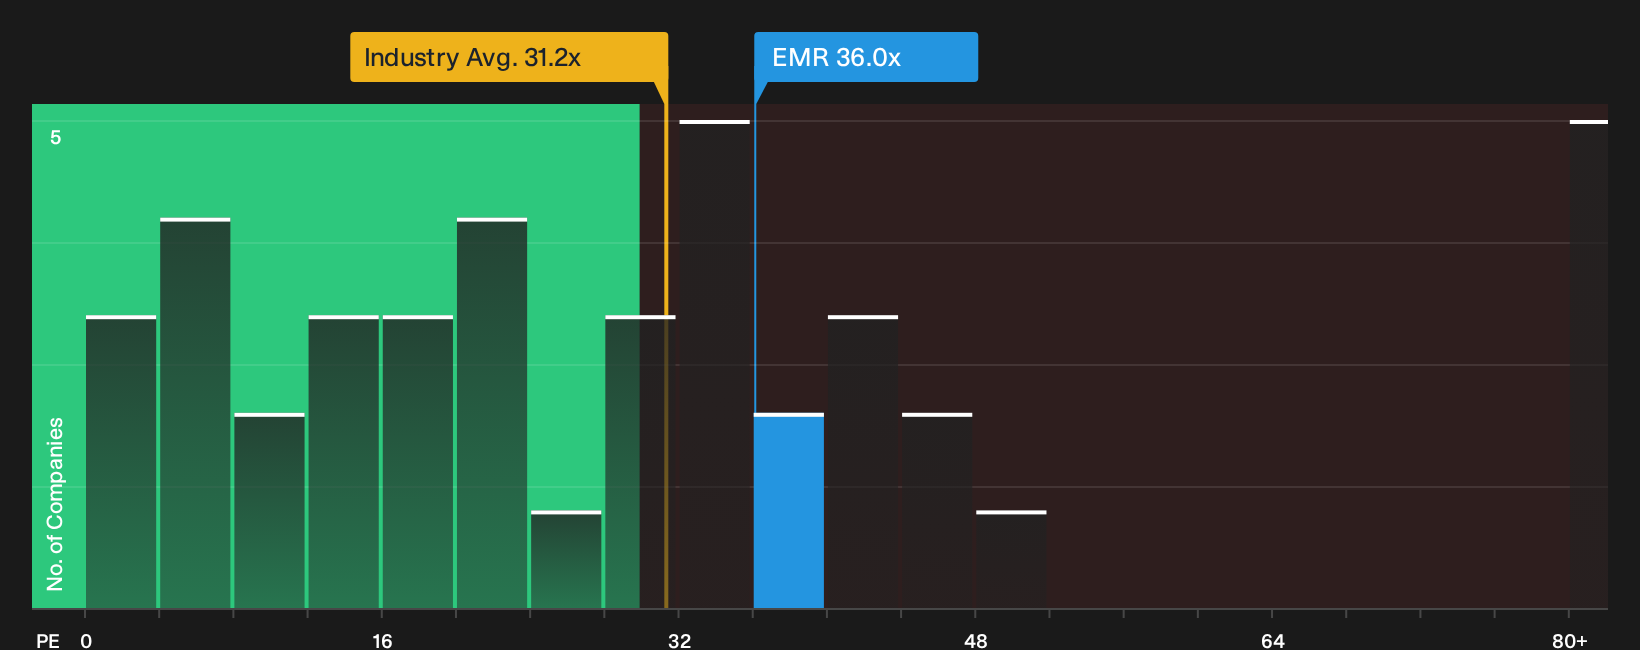
The P/E ratio fits Emerson Electric well because earnings remain a key anchor for how investors value established industrial groups. On this measure, the stock trades at about 36.0x, compared with an electrical industry average near 31.2x and a peer group closer to 40.1x. That places Emerson Electric on a premium to the broader sector, but shy of the more highly rated peers that investors currently group it with.
Because the latest results featured higher orders, top line growth and a larger dividend, the richer multiple looks tied to fresh confidence in the business. However, the current 36.0x mark still sits above what a Fair Ratio framework would suggest for the shares. This Fair Ratio benchmark reflects what might be expected for Emerson Electric given its growth profile, profitability, scale and risk, so the present valuation screens as overvalued on earnings against that yardstick. Explore the numbers behind Emerson Electric's P/E valuation.
The Emerson Electric Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle around Emerson Electric leaves off by spelling out the specific paths for growth, margins and earnings that would need to play out for the stock to look meaningfully cheaper or richer than it does today on the Community page. Rather than relying on a single valuation output, each scenario lays out the assumptions behind its fair value so you can weigh those inputs against actual results as new numbers arrive.
Community views on Emerson Electric are split between those who see more runway in its project and software funnels and those who think a lot of that optimism is already priced in.
Bull case: roughly fairly valued
"Emerson Electric's focus on subscription-based software and recurring revenue streams is reinforced by software annual contract value of about US$1.64b to US$1.68b..."
Discover why this Narrative puts Emerson Electric at roughly fairly valued.
Bear case: 23% overvalued
"The numbers indicate that Emerson Electric’s current share price already reflects optimistic outcomes on long cycle power, LNG, and software growth..."
Explore why this Narrative puts Emerson Electric at 23% overvalued.
One last Emerson Electric check that belongs beside the P/E chart
Price and earnings only tell you so much about Emerson Electric when the real steering power sits with the people in charge and how their rewards line up with your interests. See who runs Emerson Electric and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com