
The Call Woodside Energy Group Bulls Got Right
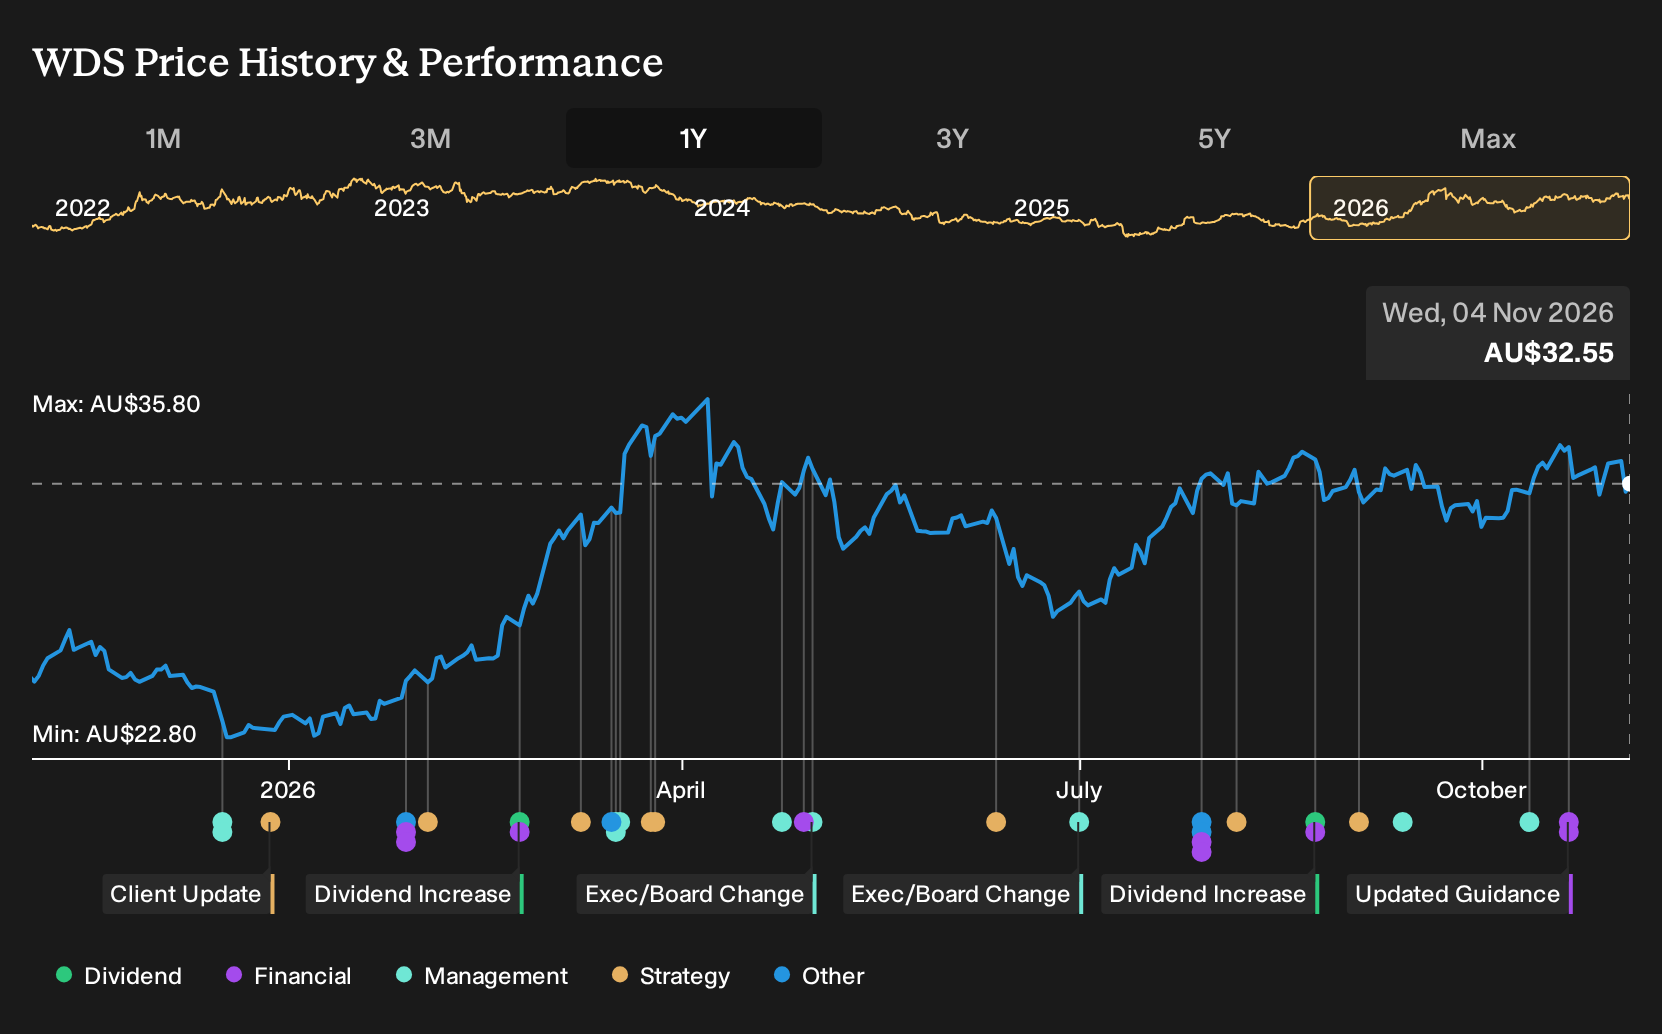
If you had paused on Woodside Energy Group after analysts argued over LNG megaprojects and decarbonization risks in late 2025, the decision now looks very different. Investors who held Woodside Energy Group over the past year are up 36.3%, including dividends. Recent headlines on Scarborough progress, Browse expansion moves and a 20-year Louisiana LNG contract sharpen the hindsight question: if you were weighing those projects a year ago, which risks and margin assumptions would matter most today?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Woodside Energy Group. Zero in on 4 high quality undervalued stocks for companies trading below our estimates.
The Two Competing Stories Around Woodside Energy Group
The shares cost A$24.94 at the start of the period, and investors in Woodside Energy Group were effectively choosing between two very different stories about where margins might settle.
The bullish narrative put fair value at A$26.7, based on an assumption that revenue would grow 0.5% a year and that net profit margins would be 16.0%, with the shares at some point trading on a 27.8x P/E.
The bearish view saw fair value at A$23.62, focused on the risk that revenue would fall 5.2% annually and that margins would contract to 8.0%, while also assuming a higher 37.0x P/E.
What The Results Changed For The Woodside Energy Group Thesis
The clearest new data point was Woodside Energy Group’s 20-year LNG offtake deal with QatarEnergy from the Louisiana project. This supported the optimistic case that long contracts could underpin utilisation and pricing. H1 2026 also showed revenue of US$7.45b and net income of US$1.67b, with net margin at 22.5%, above the 16.0% bullish assumption. Taken together, the evidence supported the optimistic case.
The episode turned on one simple checkable claim: that large LNG projects would carry firm offtake, healthy realised prices and resilient profitability. For any similar producer, focus on three disclosures each results season: contracted volumes, realised pricing and the net margin line that those contracts actually deliver.
What Woodside Energy Group's Current Price Already Assumes
Woodside Energy Group now trades at A$32.55, with this Narrative’s Fair Value sitting below that level. The gap reflects a cautious view that the current tag already bakes in a mature LNG and oil producer with solid contracted volumes and capital returns.
The key question for you is what must keep going right for that price to hold. A buyer today would need to judge that large LNG and deepwater oil projects stay on schedule and on budget while cost cuts offset tougher regulation and higher decommissioning obligations.
"The main thing that has to go right is that Woodside executes large LNG and deepwater oil projects like Scarborough, Louisiana LNG and Trion while delivering its targeted structural cost reductions and managing higher decommissioning and regulatory burdens."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 17% below our estimate - sells hybrid cloud, AI and security projects that replace fragmented, on-premise IT contracts.
- Company 2 - 34% below our estimate - expands from entertainment gear into appliances and services bundling installation with ongoing tech support.
- Company 3 - 29% below our estimate - supplies critical truck and bus components that repairers use when original parts face delays.
Three companies from the same screener. Open every one of the 12 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com