
Clariane (ENXTPA:CLARI) Following Nine Month Revenue Growth Has Its Valuation Back In Focus
Clariane (ENXTPA:CLARI) has drawn fresh attention after reporting nine month 2026 group revenue of €4,051 million, with organic growth of 4.7% compared with reported growth of 1.9% versus the prior period.
That revenue update lands against a mixed share price backdrop for Clariane, with the stock at €3.204 and a 1 day share price return of 1.65% and a 7 day share price return of 1.71%, yet down 20.26% over 90 days. The 3 year total shareholder return of 39.68% contrasts with a 5 year total shareholder return that has fallen 80.70%, suggesting short term momentum is fragile even though long term holders who invested three years ago are still ahead overall.
Scan how Clariane compares with other healthcare operators showing resilient fundamentals and recent price pressure by reviewing the hand picked list of solid balance sheet and fundamentals (196 results) in this sector.
Clariane’s share price has slipped while analyst and intrinsic estimates point higher, creating a wide gap. Is the stock already cheap enough, or does that discount signal deeper risk in the valuation work ahead?
Most Popular Narrative: 31% Undervalued
Clariane’s most followed valuation story points to a fair value of €4.66, comfortably above the last close at €3.20. This puts the recent 9 month revenue update against a market price that already reflects a sizeable discount.
Clariane's ongoing disposal plan aims to generate €1 billion in gross proceeds by December 2025, with €500 million already completed. This could signal reduced future revenue streams from divested assets, impacting overall revenue growth.
See why 8 investors see Clariane as 31% undervalued.
Result: Fair Value of €4.66 (UNDERVALUED)
Still, the narrative could be challenged if French pricing pressure hits profitability harder than expected, or if refinancing costs chip away at Clariane’s already slim net income.
Find out about the key risks to this Clariane narrative.
Another View: Clariane Through Earnings Multiples
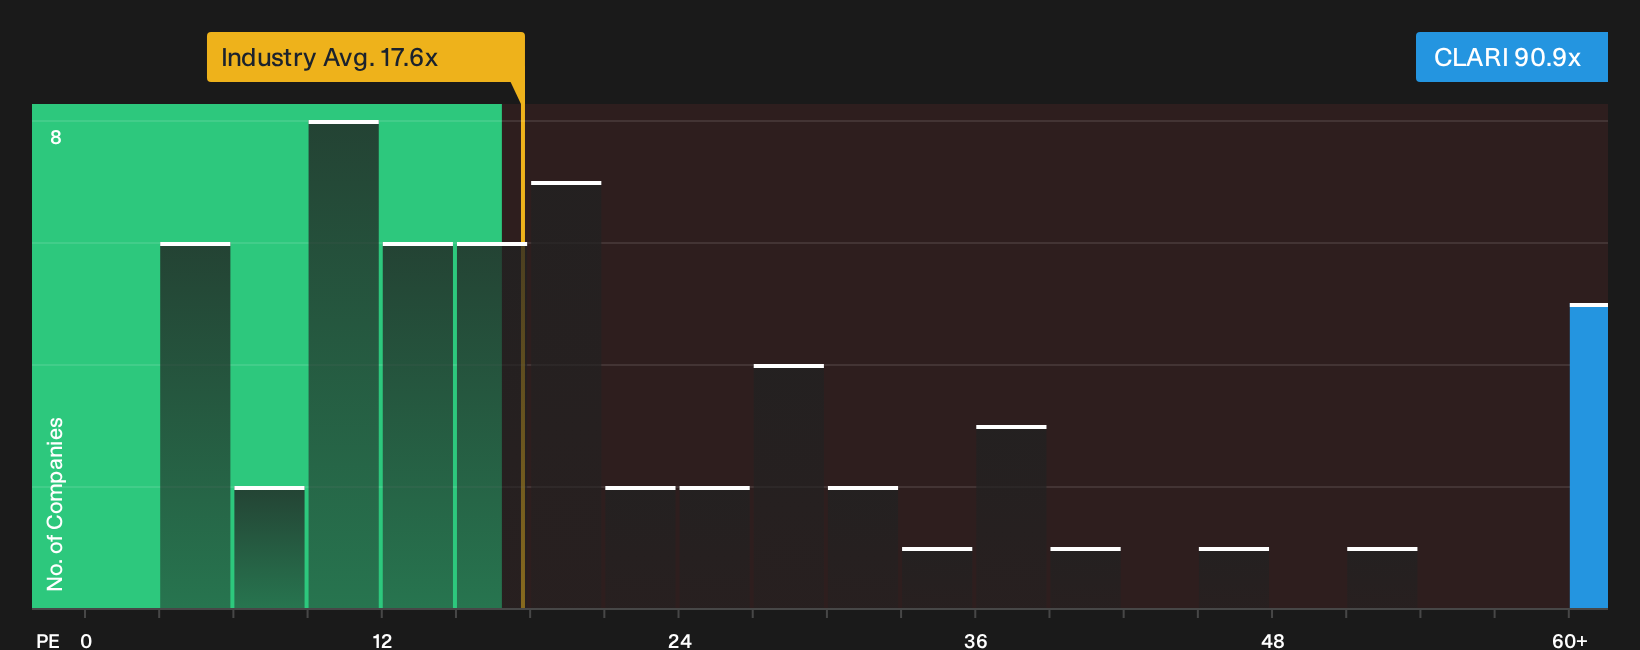
Clariane may look inexpensive against analyst fair value at €4.66, yet the current P/E of 90.9x tells a very different story. The stock trades well above peers at 12x and above its own fair ratio of 28.6x, which points to meaningful valuation risk if expectations reset.
For investors comparing Clariane with other healthcare operators using earnings multiples, the detailed breakdown of these P/E gaps can help frame how much sentiment and optimism are already reflected in the price, and where that could move if the market leans back toward the fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Clariane’s valuation and risk profile only matter if you put them in context quickly and test them against the underlying data yourself. To see both sides of the story in one place, review the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Clariane?
If Clariane has sharpened your thinking, you can use that momentum to widen your watchlist and pressure test fresh opportunities before the crowd catches on.
- Seek potential bargains that pair quality with a discount by scanning the 197 high quality undervalued stocks.
- Prioritise resilience and focus on capital preservation by running your filters through the 221 resilient stocks with low risk scores.
- Look for early standouts that the market has not fully focused on yet by reviewing the 603 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com