
Consolidated Edison (ED) Following Stronger EPS Forecasts Looks Fully Valued
Fresh optimism around Consolidated Edison (ED) is being driven by a new Wall Street consensus that points to stronger quarterly earnings, with analysts now expecting EPS of $2.07 and a 9% year over year increase.
Recent trading reflects that optimism. At a share price of $116.81, Consolidated Edison has logged a 30 day share price return of 12.98% and a year to date gain of 16.82%, while total shareholder return over 1 year sits at 23.20%. This suggests building momentum rather than a short lived bounce.
Scan how the shift in expectations for Consolidated Edison compares with other regulated utilities by reviewing a curated set of 41 power grid technology and infrastructure stocks.
After a 16.82% year-to-date climb and a share price now above both intrinsic estimates and the average analyst target, is Consolidated Edison priced for perfection, or is it still reflecting market caution that proves too harsh?
Most Popular Narrative: 9% Overvalued
Against a fair value estimate of $107.44 based on the most followed narrative, Consolidated Edison at $116.81 is priced at a premium. That gap sits on top of an already busy story around grid spending, earnings quality and the trade off between stability and future returns.
Planned infrastructure investment of about US$38b over the next five years and US$72b over the next decade at CECONY is expected to expand Consolidated Edison’s regulated asset base, which can support future revenue and earnings tied to that growing rate base.
Customer requests for electric capacity that are roughly 20 to 25% above historical levels, with about two thirds of new large projects choosing all electric solutions, point to future load growth that can increase Consolidated Edison’s regulated revenues as those projects come online.
See why 1 investors see Consolidated Edison as 9% overvalued.
Result: Fair Value of $107.44 (OVERVALUED)
Still, Consolidated Edison’s story relies on regulators allowing sufficient returns, provided that extreme weather or legal setbacks do not push costs and penalties sharply higher.
Find out about the key risks to this Consolidated Edison narrative.
Another View: What Multiples Say About Consolidated Edison
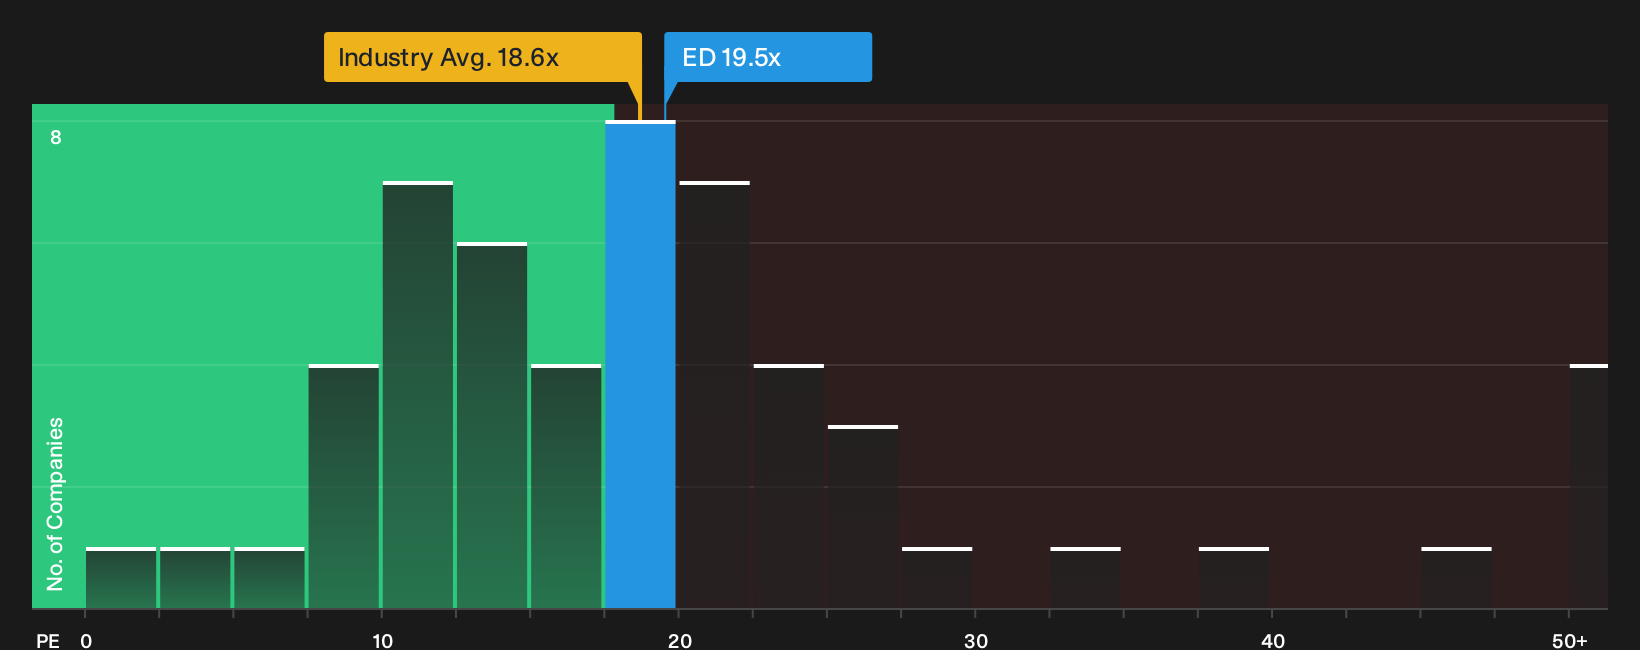
The narrative fair value of $107.44 paints Consolidated Edison as roughly 9% overvalued. Yet the P/E of 19.5x sits below the estimated fair ratio of 21.5x and under the US Integrated Utilities average of 21.5x, while sitting above the global sector at 18.2x. That mix points to a stock priced as a relatively solid utility, not a clear outlier. Which signal do you weigh more heavily when the story and the simple multiple point in different directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of optimism and caution around Consolidated Edison line up with your own read, or does it feel one sided and incomplete? Take a few minutes to weigh the upside against the red flags, then ground your next move in the full picture of 3 key rewards and 2 important warning signs.
Ready to act beyond Consolidated Edison?
If this review sharpened your view on Consolidated Edison, do not stop here. Broaden your radar with fresh ideas that match your own risk and return priorities.
- Target steadier compounding by scanning a focused set of 30 resilient stocks with low risk scores that aim to keep portfolio volatility in check.
- Hunt for mispriced opportunities using the 35 high quality undervalued stocks that filters for quality fundamentals at prices that may lag underlying strength.
- Strengthen income potential by reviewing the 4 dividend fortresses built to spotlight higher yielding companies with the backing of robust cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com