
ON Semiconductor Stock Outlook: Is Wall Street Bullish or Bearish?
With a market capitalization of $28.3 billion, Scottsdale, Arizona-based ON Semiconductor Corporation (ON) is a global semiconductor manufacturer specializing in intelligent power and sensing solutions. Its products, including advanced MOSFETs, image sensors, and silicon carbide technology, serve the automotive, industrial, computing, medical, and aerospace markets, improving energy efficiency, safety, and sustainability.
Shares of the semiconductor giant have substantially outpaced the broader market over the past year. ON has risen 43.9% during this period, compared with a 10.5% advance for the S&P 500 Index ($SPX). The stock has continued to outperform in 2026, gaining 34.1% year-to-date, while the S&P 500 has advanced 10.6% over the same period.
However, ON has trailed the First Trust Nasdaq Semiconductor ETF (FTXL), which has climbed 63.7% over the past year and gained 61.4% year-to-date.
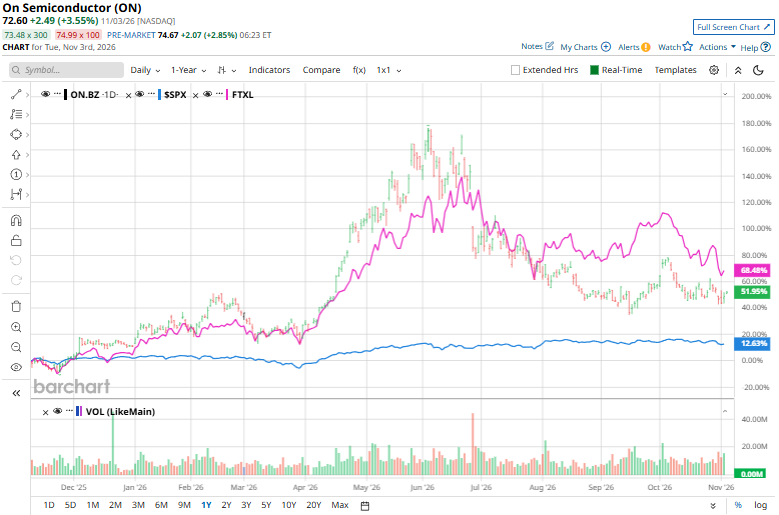
On Nov. 2, ON Semiconductor reported its third-quarter 2026 results, beating analyst estimates for both revenue and earnings. Shares jumped 3.6% in the following trading session. Revenue increased 11.1% year over year to $1.72 billion, led by 21% growth in the Power Solutions Group (PSG) to $889.9 million. The Analog and Mixed-Signal Group (AMG) and Intelligent Sensing Group (ISG) each reported 2% revenue growth. Diluted EPS rose 42.9% to $0.90, while non-GAAP gross margin expanded to 41.2% from 38% and operating margin increased to 23.2% from 19.2%. Meanwhile, AI data center revenue surged 175% year over year to $180 million.
Looking ahead, ON Semiconductor expects fourth-quarter 2026 revenue of $1.72 billion to $1.82 billion, non-GAAP EPS of $0.95 to $1.07, and non-GAAP gross margin of 41.5% to 43.5%.
Beyond its quarterly results, the company announced an agreement to acquire Ferric to expand its AI processor power-delivery business. Following the announcement, ON raised its 2030 AI data center revenue target by $500 million to more than $3 billion. Separately, it revised the terms of its planned Synaptics Incorporated (SYNA) acquisition, replacing the previous $7 billion all-stock agreement with an approximately $5.7 billion all-cash transaction.
Looking ahead, analysts expect ON’s diluted EPS to increase 38.7% year over year to $3.26 for the fiscal year ending in December 2026. Meanwhile, the company has exceeded consensus EPS estimates in each of the past four quarters, which is impressive.
Of the 30 analysts covering ON, the consensus rating is “Strong Buy.” This assessment comprises 12 “Strong Buy” ratings, two “Moderate Buy” ratings, and 16 “Hold” ratings.
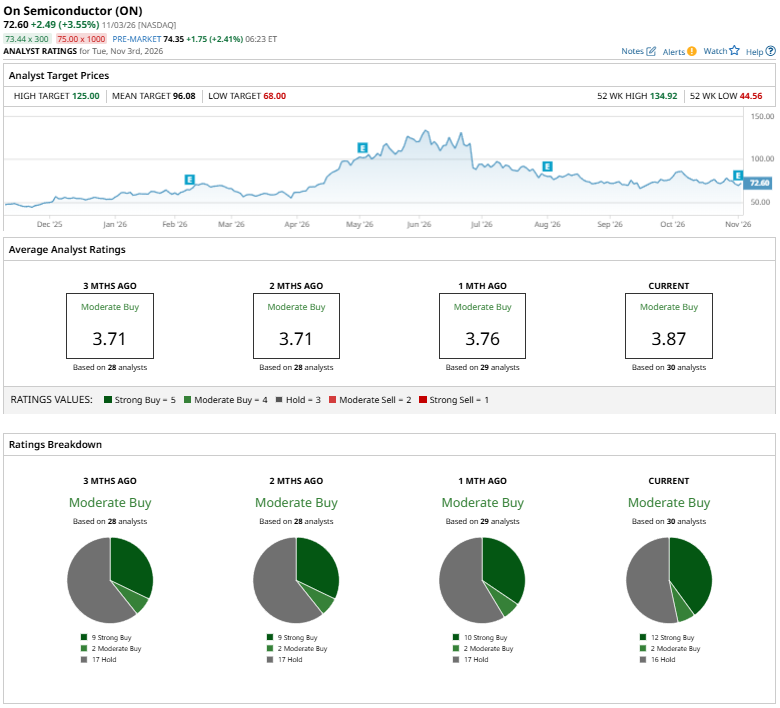
ON’s analyst configuration reflects a more bullish outlook than a month ago, when the stock had 10 “Strong Buy” recommendations.
On Nov. 3, 2026, Cantor Fitzgerald analyst Matthew Prisco reiterated a “Neutral” rating on ON Semiconductor and maintained his price target of $90.
Based on analysts’ estimates, the mean price target of $96.08 implies a 32.3% premium to ON’s current share price, while the Street-high price target of $125 suggests a 72.2% premium.
On the date of publication, Abhishek Bhuyan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.