
Is Triumph Financial (TFIN) Below Fair Value After Its Stronger 2026 Results?
Triumph Financial (TFIN) just posted stronger third quarter and year to date results, with higher net interest income and a sharp jump in net income compared with the same periods in 2025.
Triumph Financial’s share price has softened in recent months, with a 90 day share price return down 19.14%, even though the 1 year total shareholder return is up 16.51%. That mix of shorter term weakness and longer term recovery suggests investors are still reassessing the improved earnings story against past volatility and risk.
Scan how Triumph Financial’s earnings rebound compares with peers by running the hand picked list of solid balance sheet and fundamentals (23 results) alongside TFIN’s recent performance and business mix.
Triumph Financial now trades below the average analyst price target, even after a strong earnings rebound. Is that a reasonable safety margin, or a sign the market still distrusts the story?
Most Popular Narrative: 16% Undervalued
Triumph Financial’s widely followed thesis pegs fair value at $75 per share, above the recent $63.16 close. This frames today’s pullback as a valuation gap that hinges on where future fee income and margins actually land.
The continued mix shift from traditional banking toward higher margin fintech and intelligence offerings, which are expected to represent a greater share of Triumph Financial’s revenue base, supports a higher contribution from fee income and potentially stronger returns on assets.
Expansion of Triumph Financial’s data and decision support tools such as the Intelligence offerings and RFP Manager, built on a large brokered freight dataset, provides opportunities to grow subscription and analytics revenue and support a second leg of earnings contribution beyond core financial services.
See why 2 investors see Triumph Financial as 16% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, Triumph Financial’s heavy exposure to freight focused factoring and payments, along with weaker core banking revenue, could unsettle that 16% undervalued narrative.
Find out about the key risks to this Triumph Financial narrative.
Another View: Triumph Financial Looks Expensive On Earnings
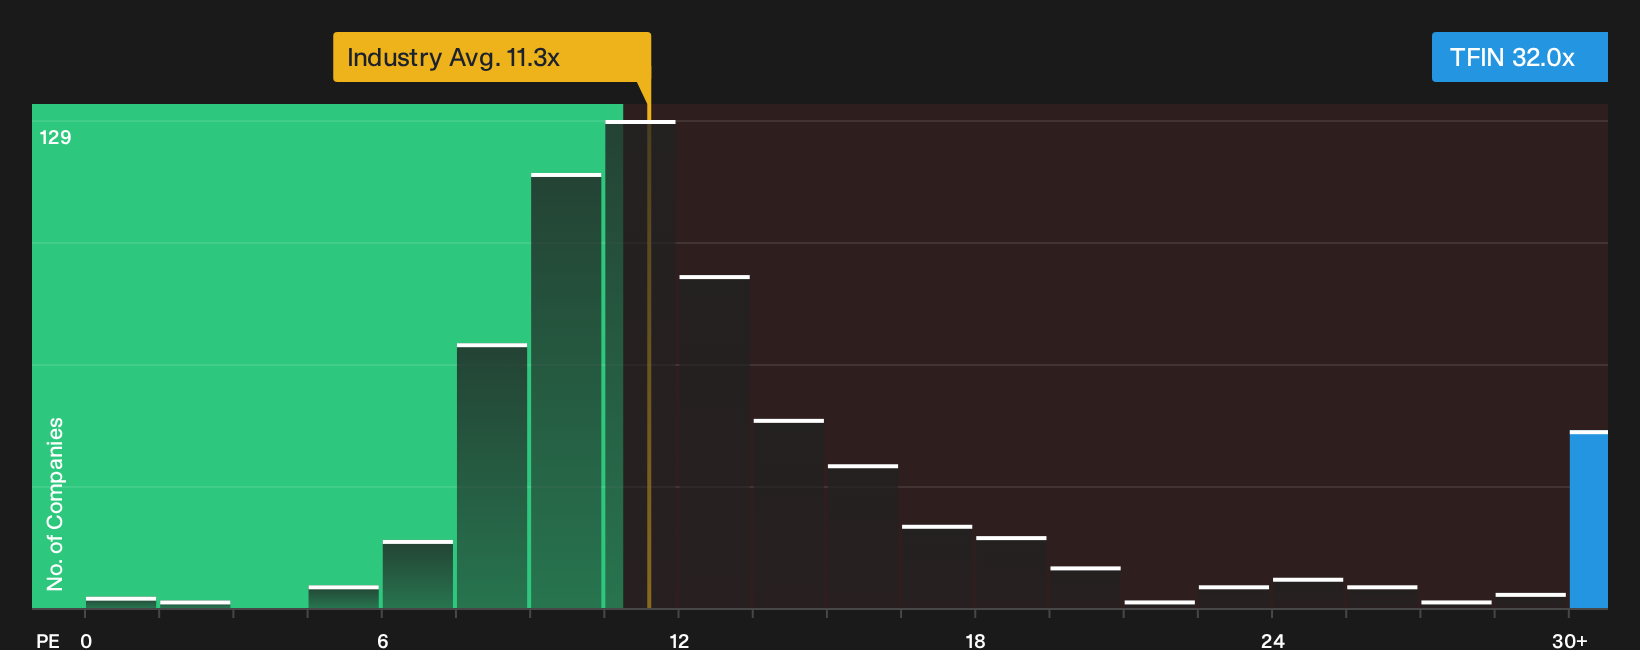
The story changes once you step away from fair value models and look at Triumph Financial through a straight P/E lens. The stock trades at about 32x earnings, while the US Banks industry sits near 11.3x and close peers average 11.6x. A fair ratio for TFIN is estimated at 18x, which hints at meaningful valuation risk if sentiment swings back toward bank like multiples. How much premium are you willing to pay for the fintech and freight narrative?
For a closer look at how that earnings based gap is built up and where it might close from here, check the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This mix of optimism and caution around Triumph Financial will not resolve itself. Pull the filings, stress test the assumptions, then weigh the 3 key rewards and 3 important warning signs.
Looking for more Triumph Financial sized ideas?
If Triumph Financial has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities before the crowd catches on.
- Target resilient balance sheets and steadier fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) that already clear tough financial hurdles.
- Hunt for potential value gaps by scanning the 35 high quality undervalued stocks that combine quality metrics with prices that lag underlying fundamentals.
- Prioritise income and staying power by filtering for 4 dividend fortresses that pair higher yields with more robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com