
Phillips 66 (PSX) Posts Strong Q3 Results, Is The Upside Fully Priced?
Phillips 66 (PSX) is back in focus after third quarter 2026 results showed sharp year on year jumps in sales, revenue, and net income, alongside active investment in midstream and chemicals.
Despite a small 1-day share price decline of 1.13% to US$271.94, Phillips 66 has built strong momentum, with a 90-day share price return of 34.26% and year-to-date share price gain of 108.27%. The 1-year total shareholder return of 106.26% and 5-year total shareholder return of 311.86% reflect how the market has been reassessing both future earnings capacity and risk as earnings have surged, renewable fuels agreements have been announced, and sector flows have shifted, including recent selling from a major energy ETF.
Scan for other energy players showing similar momentum and capital discipline by reviewing our hand picked 35 high quality undervalued stocks alongside the latest move by Phillips 66.
After a 108% year to date surge and with a share price sitting below both analyst targets and some fair value estimates, is Phillips 66 pricing in justified caution or leaving too much upside on the table for patient holders?
Most Popular Narrative: 4.8% Undervalued
On the most followed view, Phillips 66 carries a fair value estimate of $285.74 versus a last close of $271.94. This leaves a modest valuation gap that depends on how durable its refining and midstream cash generation really is.
The main requirement is continued delivery on midstream and refining cost targets, including reaching about $4.5b of Midstream EBITDA and sustaining low per barrel operating costs while managing leverage and operational risks.
Phillips 66 is viewed as fairly valued and bullish, and current earnings, cash generation and cash return levels imply the share price already reflects a large part of the expected margin strength and operational improvement story.
See why 51 investors see Phillips 66 as 5% undervalued.
Result: Fair Value of $285.74 (UNDERVALUED)
Still, a sharp downturn in refining conditions or prolonged derivative losses that absorb cash could quickly challenge the current Phillips 66 fair value story.
Find out about the key risks to this Phillips 66 narrative.
Another View: Phillips 66 On Earnings Multiples
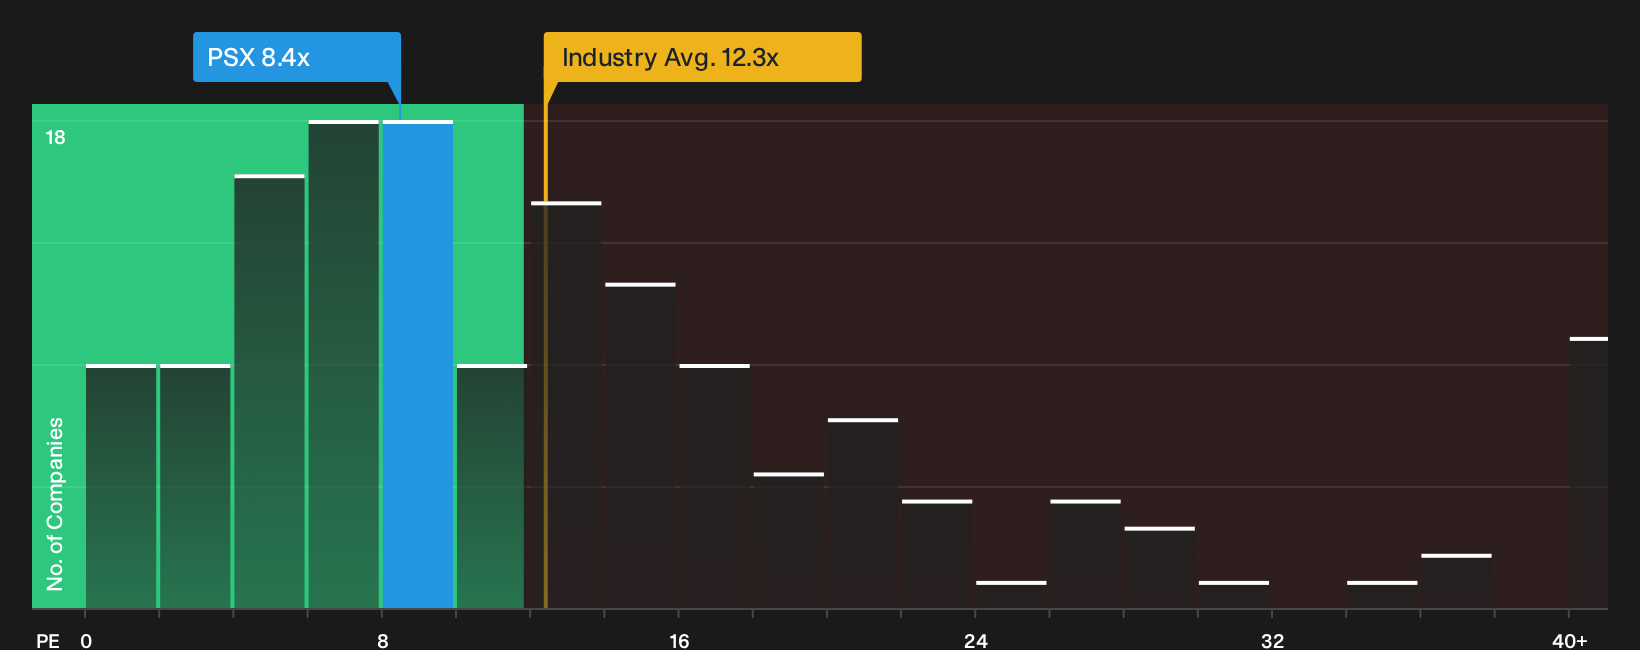
The fair value narrative paints Phillips 66 as about 4.8% undervalued at $285.74, yet the earnings multiple picture is less straightforward. The stock trades on a P/E of 8.4x, slightly above peers at 7.9x, but below an estimated fair ratio of 14.4x. That mix of slight premium to the group and wide gap to the fair ratio suggests either a cushion for long term holders or room for the valuation to compress if sentiment cools. Which side of that trade do you think the market is really pricing in today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the narrative so far. If you want to move quickly and rely on your own judgement, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Phillips 66?
If you stop with Phillips 66, you only see one piece of the puzzle. Cast the net wider with a few targeted stock ideas built from real fundamentals.
- Target potential opportunities by scanning a curated set of 19 high quality undiscovered gems that many investors are not watching yet.
- Prioritise stability and peace of mind by reviewing a 30 resilient stocks with low risk scores that screens for resilient balance sheets and lower volatility profiles.
- Focus on dependable fundamentals by running through a list of solid balance sheet and fundamentals (23 results) that filters for financial strength before momentum grabs wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com