
Why Aurora Innovation (AUR) Is Getting Attention Today
Aurora Innovation (AUR) is back in focus after signing a memorandum of understanding with Charger Logistics, in which the carrier intends to purchase up to 500 Aurora Driver-powered trucks for deployment beginning in 2027.
The Charger Logistics MOU comes amid a mixed trading backdrop for Aurora Innovation. The share price has climbed 10.34% year to date, yet fallen 24.69% over the past 30 days and 36.17% across 90 days, while the 3-year total shareholder return remains very large despite a 4.79% decline over the last year. This suggests that recent weakness is cutting into what had been strong longer term momentum, as investors weigh rapid revenue growth guidance and recurring losses against growing interest in its autonomous trucking platform.
Scan beyond Aurora Innovation and see how other autonomy and AI infrastructure players are setting up with 53 AI infrastructure stocks for the next phase of demand in this space.
After that sharp pullback and with Aurora Innovation still loss making despite rapid revenue guidance, the real tension is simple: do you still get paid enough for the risk at this price, as the valuation section now tackles?
Most Popular Narrative: 63% Undervalued
Aurora Innovation last closed at $4.27, while the most followed narrative puts fair value at $11.63. This implies a wide gap that only makes sense if the long haul trucking rollout eventually lives up to its billing.
Deepening OEM and manufacturing partnerships with Volvo, PACCAR, International and AUMOVIO, combined with increased U.S. production capacity, lays the groundwork for a larger fleet of autonomous trucks on the road, which could increase operating leverage as fixed platform costs are spread over a larger installed base.
See why 32 investors see Aurora Innovation as 63% undervalued.
Result: Fair Value of $11.63 (UNDERVALUED)
Still, the story can break if revenue remains tiny against large quarterly losses or if commercialization targets, such as the 200 truck milestone, keep slipping.
Find out about the key risks to this Aurora Innovation narrative.
Another Angle On Aurora Innovation’s Valuation
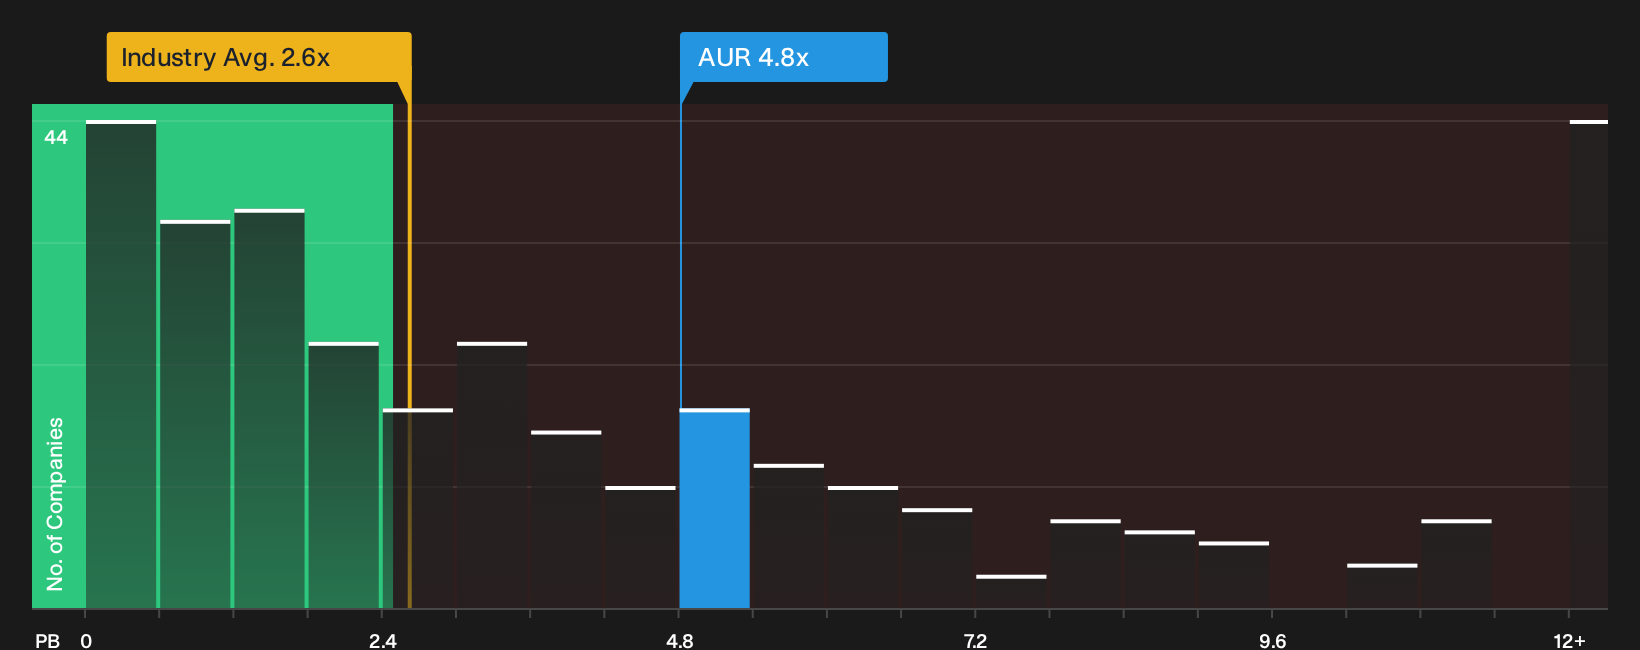
The first narrative paints Aurora Innovation as significantly undervalued on a long range earnings and price target view. A different lens tells a more complicated story. The stock trades around 4.8x book value compared with about 2.6x for the broader US software group and roughly 4.3x for closer peers. That richer P/B ratio, despite ongoing losses and no profit forecast in the next three years, points to investors already paying up for the autonomous trucking vision. The question is simple for anyone considering the shares: How comfortable are you paying a premium multiple today when the path to actual profitability is still some distance away?
To see how that richer valuation multiple stacks up against the underlying numbers, and what the fair ratio suggests the market could gravitate toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Aurora Innovation’s valuation and execution story mean there is plenty for you to weigh up. Act while sentiment is still split, and walk through both sides of the debate by checking the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aurora Innovation?
If Aurora Innovation has you thinking about where capital could work harder, do not stop here. A few focused stock lists can quickly surface alternatives with different risk and reward profiles.
- Target resilient balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that prioritises financial strength over story alone.
- Hunt for mispriced opportunities by reviewing a focused set of 35 high quality undervalued stocks where quality and valuation metrics line up more cleanly.
- Lock in income ideas by checking a hand picked group of 4 dividend fortresses that emphasise higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com