
Boeing (BA) Stock Trades At A Discount After Fresh Orders
Boeing has had a rough year in the market, and with fresh orders and a large backlog in the headlines, the key issue for investors is whether the current share price is still in line with what its earnings can reasonably support.
- The stock is down 23.9% year to date, which puts fresh focus on whether that weaker share performance now lines up more closely with the earnings power of the business.
- A record order of 140 Boeing 737-10 jets for lessor Avolon and a large total backlog highlight potential future revenue, but the production delays and higher costs reported recently may affect how quickly those orders convert into earnings.
- There is a second opinion on Boeing worth weighing. See what analysts think Boeing's shares could be worth.
The issue now is whether Boeing's current market value is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you want a second starting point for research alongside Boeing, consider using a focused stock screen built around 41 power grid technology and infrastructure stocks.
Is Boeing a Bargain on Earnings?
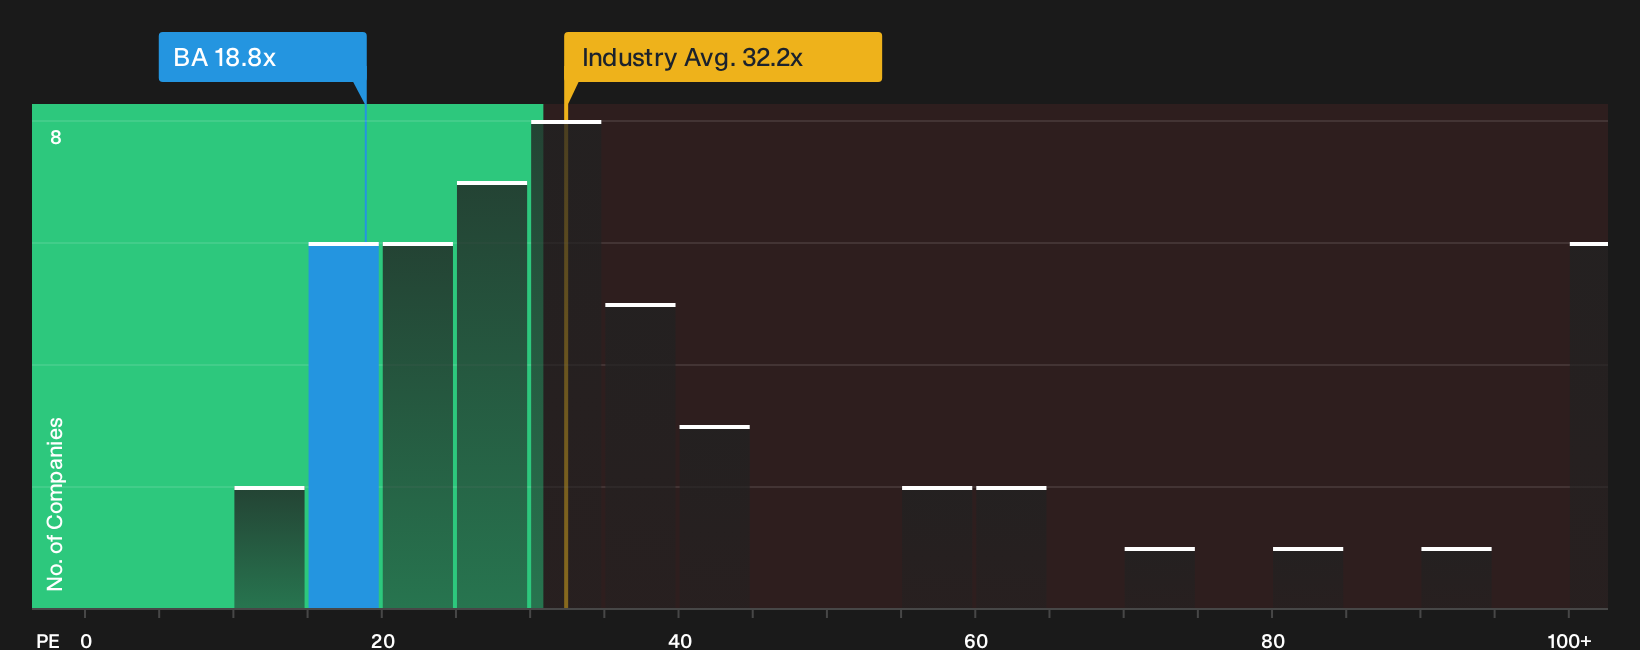
The P/E ratio fits Boeing because earnings are the key link between its large backlog and what shareholders are paying today. On this metric, Boeing trades on a P/E of 18.8x, which is below the Aerospace & Defense industry average of 32.2x and also under the peer group on 26.2x. Against the Fair Ratio benchmark, which reflects what investors might usually pay given Boeing's growth profile, profitability, size and risk, the current multiple points to the stock being undervalued rather than stretched.
Because the record Avolon order and wider backlog are already public, the key takeaway is that even with these contracts in view the market is pricing Boeing at a discount to both sector norms and the more tailored Fair Ratio yardstick. That gap suggests investors are still pricing in execution and production risks, so any assessment of the shares will come down to how confidently you think management can turn that order book into sustained earnings power over time. Explore the numbers behind Boeing's P/E valuation.
The Boeing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Boeing pick up where the valuation puzzle leaves off, explaining which potential paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. They are available on Boeing's Community page so you can see how those assumptions evolve. Where a single ratio or model gives one number, these narratives unpack the future that number relies on so you can watch whether it still matches reality.
Community views on Boeing split between a long runway in the backlog and services business and a slower, more fragile financial clean up.
Bull case: 29% undervalued
"A record-high commercial aircraft backlog exceeding $500 billion, with firm orders for the 737 and 787 programs stretching to the next decade, indicates sustained, long-term growth visibility…"
Discover why this Narrative puts Boeing at 29% undervalued.
Bear case: 8% overvalued
"Any single programme charge above $1 billion in a quarter through 2027... Commercial Airplanes still at a negative operating margin at the end of 2027…"
Explore why this Narrative puts Boeing at 8% overvalued.
One more Boeing check that belongs beside the valuation work
Price ratios and backlogs show what Boeing is today, while professional earnings projections sketch what informed observers think this business could look like a few years from now. Explore where analysts expect Boeing to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com