
China Mengniu Dairy (SEHK:2319) Faces A Fresh Valuation Test Following Mbappé Split
China Mengniu Dairy (SEHK:2319) is back in focus after it cut ties with football star Kylian Mbappé following a Mao meme controversy, putting brand risk and current valuation under closer scrutiny.
Short term momentum around China Mengniu Dairy has been strong, with a 7 day share price return of 18.36% and a 30 day move of 22.86% helping lift the year to date share price gain to 42.93% at HK$21.34, even though the 5 year total shareholder return is down 47.16%. This leaves recent Mbappé headlines feeding into a debate about whether sentiment is improving faster than the long run record might justify.
Contrast China Mengniu Dairy's reputational and valuation pressures with financially stronger options by scanning the curated list of solid balance sheet and fundamentals (195 results), which may offer more resilience if sentiment swiftly turns.
China Mengniu Dairy has risen sharply in a short period, and reputational risk is now front and center. Does the current price still leave enough upside to compensate for that brand and earnings uncertainty?
Most Popular Narrative: 9% Undervalued
Against the last close at HK$21.34, the most followed narrative on China Mengniu Dairy anchors fair value at HK$23.57. This frames the recent surge as still short of that mark while brand risk headlines swirl in the background.
Ongoing shift at China Mengniu Dairy from scale and low-price competition toward higher value milk, yogurt and functional nutrition, supported by strong growth in premium and fresh milk segments in 2H25 and 1H26, continues to point to a richer product mix that can support future revenue and margin improvement.
See why 8 investors see China Mengniu Dairy as 9% undervalued.
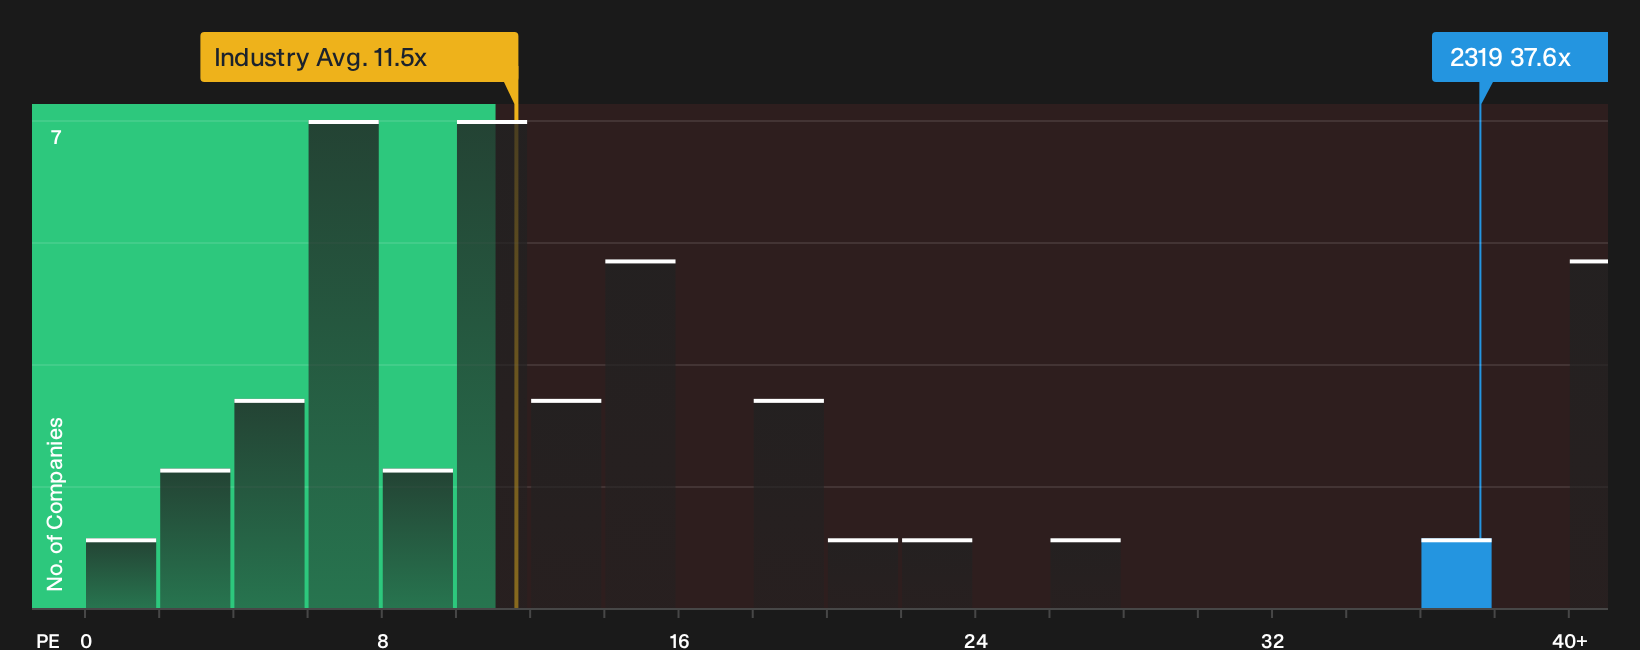
That narrative uses a 7.07% discount rate and assumes annual revenue growth of 4.9%, with profit margins rising from 2.2% to about 6.0%, to arrive at a fair value of HK$23.57. Against HK$21.34, this implies China Mengniu Dairy trades at roughly a 9% discount to that framework, even though the same narrative flags a P/E of 37.6x today versus an estimated fair P/E of 22x and an industry level of 11.5x.
The gap between the narrative fair value and the SWS DCF output is even starker. The DCF estimate of HK$63.83 per share, based on projected future cash flows for the dairy group and discounted back using the same SWS framework, is far above both the current share price and the HK$23.57 narrative fair value. This highlights how sensitive long term cash flow models can be to earnings path assumptions and terminal values.
For readers trying to reconcile all of this, the key question is which lens feels more realistic. The narrative ties its HK$23.57 figure to concrete datapoints such as record free cash flow of CN¥6.3b, an 8.0% operating margin in 2025 and forecasts for earnings to reach CN¥6.0b by around 2029. The DCF output assigns much more value to those future cash streams than either the narrative or the market currently do at HK$21.34.
Result: Fair Value of HK$23.57 (UNDERVALUED)
Still, if China Mengniu Dairy’s core liquid milk margins stay under pressure or if complexity from expansion keeps lifting costs, this optimistic narrative could quickly be challenged.
Find out about the key risks to this China Mengniu Dairy narrative.
Another View: Rich Multiple, Different Message
That 9% undervaluation story for China Mengniu Dairy looks very different when you switch from narratives and DCF to the simple P/E yardstick. On 37.6x earnings, the stock trades well above the Hong Kong Food industry at 11.5x and the fair ratio of 22x.
Put plainly, the P/E suggests investors are paying a premium that leaves much less room for disappointment if growth or margins undershoot, even if the SWS fair value narrative and DCF hint at upside. Which signal do you trust more when brand risk is back on the front page?
For readers weighing that premium against the growth story, the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around China Mengniu Dairy leave you unsure, consider acting promptly, reviewing the underlying data, and weighing the potential upside alongside the specific positives highlighted in the 3 key rewards
Looking for more investment ideas beyond China Mengniu Dairy?
Do not stop at China Mengniu Dairy. Broaden your watchlist with fresh ideas that match different goals, risk levels, and income needs using the Simply Wall St Screener.
- Target potential mispricing by scanning for quality opportunities that screens highlight as out of favour through the 199 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that appear in the 221 dividend fortresses, where yields and track records sit side by side.
- Dial down risk by focusing on businesses filtered by the 221 resilient stocks with low risk scores, so you can prioritise resilience when markets turn against you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com