
DXC Technology (DXC) Stock May Be A Bargain Following Agentic AI Push
DXC Technology has seen a sharp reset in its share price over the past few years, and recent swings have pushed investors to ask what they are really paying for the company's earnings today. With the stock changing hands around US$13.78, the issue is whether that quotation lines up with the profit engine behind the business.
- Over the past 5 years the share price has fallen 59.2%, which puts the focus squarely on whether current earnings still support even this lower market value.
- Recent efforts to expand agentic AI services, reshape the portfolio and address weaker sales execution can influence expectations for future profit margins and the timing of cash generation that underpin any earnings based valuation.
- There is a second opinion on DXC Technology worth weighing. See what analysts think DXC Technology's shares could be worth.
The issue now is whether the stock's current price is justified by DXC Technology's earnings power today and what those profits imply for investors over time.
If you are weighing whether DXC Technology's US$13.78 price truly lines up with its earnings story, it can help to compare that question across 35 high quality undervalued stocks.
Is DXC Technology Still Cheap on Earnings?
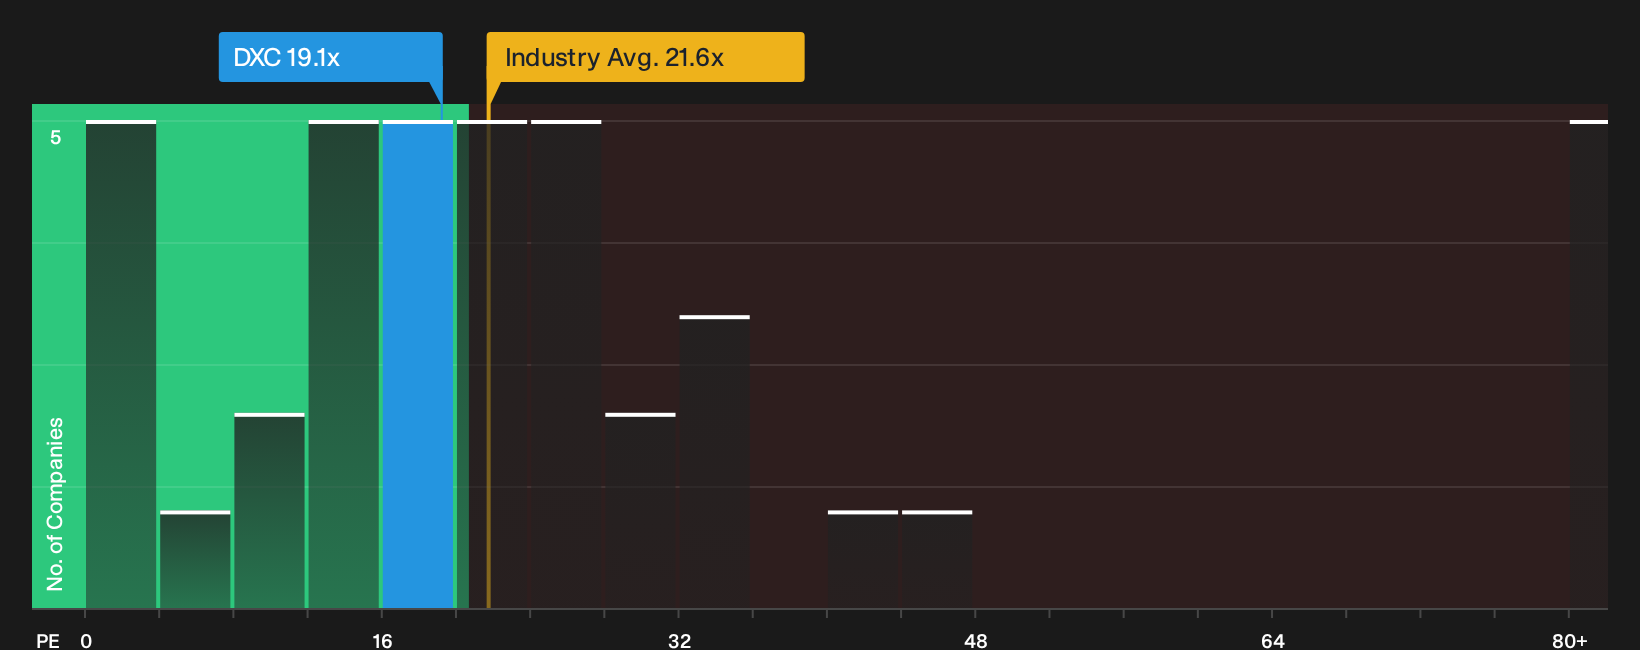
The P/E ratio is a useful lens for DXC Technology because earnings still provide a clear anchor for what investors are currently paying. At roughly 19.1x earnings, the stock trades below the broader IT industry average of about 21.6x and a peer group closer to 21.2x. That means you are paying a lower price for each dollar of DXC Technology's profits than for many comparable IT service providers.
The fair P/E level implied by DXC Technology's own fundamentals and risk profile sits above where the shares trade today, which points to the stock being undervalued on this metric. Because the company has recently cut revenue and EPS guidance while pushing harder into agentic AI and considering a sale of its insurance arm, the market may be discounting execution risk more heavily than this model does. For investors, the gap between the current multiple and that tailored fair value is the key question to explore further. Explore the numbers behind DXC Technology's P/E valuation.
The DXC Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for DXC Technology pick up where the P/E puzzle leaves off and explain which combinations of future growth, profitability and earnings power would need to occur for the stock to be worth materially more or less than today’s price. Rather than relying on a single multiple or model output, each narrative sets out the assumptions that underpin its view of fair value so you can compare those expectations with DXC Technology's reported results over time on the Community page.
Community views on DXC Technology are split between those who see more upside in the AI and cash flow story and those who think most of that is already reflected in the current price.
Bull case: roughly fairly valued
"The company wide use of agentic platforms such as OASIS, Agentic SOC and Converge, together with a targeted US$1.0-1.5b reduction in spending over three years, provides room for DXC Technology to convert AI driven productivity into structurally higher adjusted EBIT margins and stronger net income from essentially the same revenue base…"
Discover why this Narrative puts DXC Technology at roughly fairly valued.
Bear case: 10% overvalued
"Ongoing organic revenue declines, with recent quarterly revenue of US$3.0b that was down 6.7% year over year and guidance for a further 3% to 5% organic decline in the current fiscal year, could show that DXC Technology is not yet stabilizing its top line, which would pressure future revenue and earnings…"
Explore why this Narrative puts DXC Technology at 10% overvalued.
DXC Technology’s value is one thing, who is actually steering it is another
The people setting priorities at DXC Technology, how they are rewarded and what they are incentivised to chase can all reshape the investment story in ways the P/E alone cannot show. See who runs DXC Technology and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com