
How Lower Quarterly Earnings Will Impact Avis Budget Group Stock (CAR)
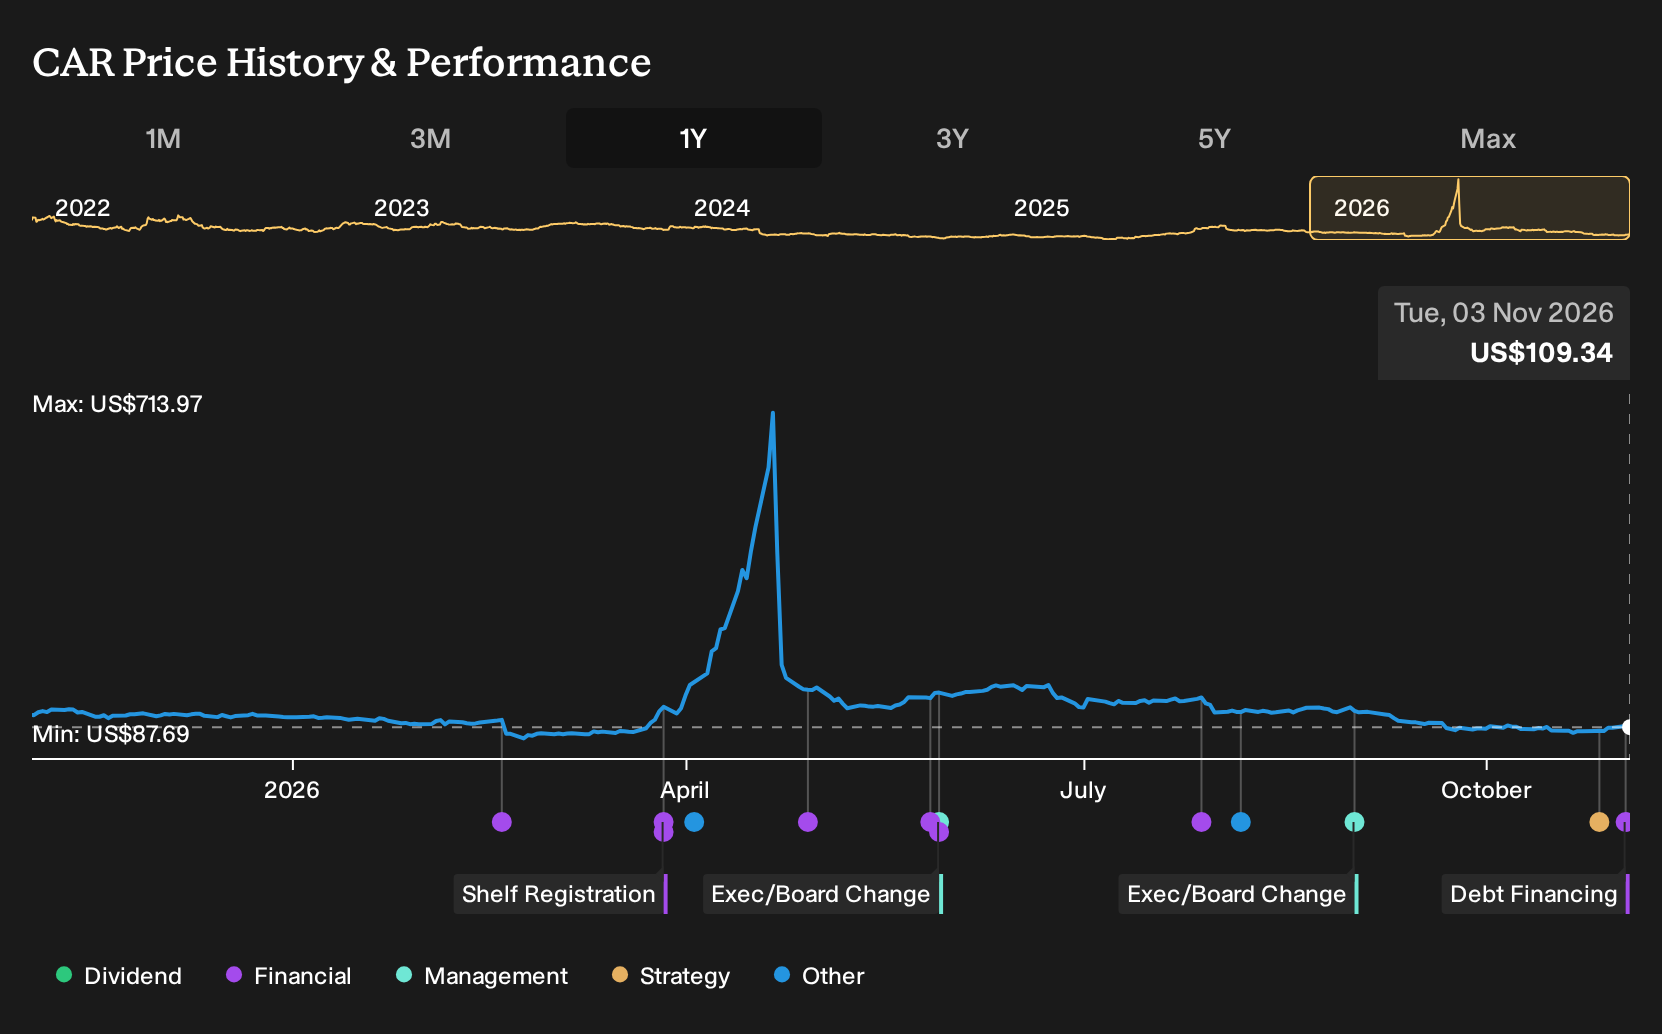
- Avis Budget Group reported third quarter 2026 revenue of US$3,436 million and net income of US$183 million, with basic earnings per share from continuing operations of US$5.19.
- The nine month period to September 30, 2026 showed relatively flat sales at US$8,964 million but a reduced loss of US$65 million, indicating pressure on profitability yet some improvement versus the prior year.
- This analysis now considers how Avis Budget Group’s sharply lower quarterly earnings may influence the broader investment narrative around the rental operator.
Scan how Avis Budget Group’s earnings reset compares with peers by sizing up a hand picked list of 35 high quality undervalued stocks that may be pricing in very different expectations.
Avis Budget Group Investment Narrative Recap
An investor in Avis Budget Group needs to believe that tighter fleet management, premium offerings and technology focused services can eventually convert relatively flat revenue into more reliable profits. The sharp drop in quarterly earnings puts that thesis under pressure in the near term, because it highlights how sensitive results remain to utilization, recall issues and pricing.
The most important short term catalyst is execution on premium and tech enabled rentals that support higher revenue per day and fewer unrentable vehicles. The biggest risk is that recall costs, legal matters and high leverage limit flexibility. The latest quarter reinforces that risk rather than changing it.
The redemption of US$350 million of 5.75% Senior Notes due July 2027 is closely tied to that leverage question. Avis Budget Group has already flagged that interest payments are not well covered by earnings, so any reduction in gross debt and future interest expense is important for the equity story.
For you as a shareholder, this kind of liability clean up can matter as much as quarterly EPS volatility. It speaks to whether balance sheet repair can keep pace with recall costs, legal exposures and uneven profitability, which in turn shapes how much of any future operating improvement actually reaches the bottom line.
Avis Budget Group's current analyst narrative points to revenues of US$12.1b and earnings of US$592.8 million by 2029, based on assumed yearly top line expansion of 1.2% and an earnings swing of about US$1.23b from a loss of US$636.0 million today.
Uncover how Avis Budget Group's fair value indicates a 6% potential upside to its current price, before that discount to fundamentals starts to close.
Exploring Other Perspectives
You now see a very different angle on Avis Budget Group. The most optimistic analysts lean heavily on the premium Avis First rollout as the swing factor, with prior forecasts pointing to about US$12.5b of revenue and US$694.4 million of earnings by 2029. After this quarter’s weaker profit, those upbeat assumptions may be revisited. It therefore helps to weigh several viewpoints before deciding how this reset fits your own thesis.
Explore 2 other Avis Budget Group fair value estimates, including one that suggests potential upside of as much as 135% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avis Budget Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avis Budget Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avis Budget Group's overall financial health at a glance.
Looking for more investment ideas beyond Avis Budget Group?
If this reset in the Avis Budget Group story has you rethinking where to focus fresh capital, use the Simply Wall St Screener to scan for other opportunities that better match your risk appetite and time horizon.
- For investors who want potential upside without ignoring quality, review a curated set of under-appreciated businesses through the 35 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, filter for companies that pass strict balance sheet tests with the list of solid balance sheet and fundamentals (23 results).
- When income is the priority and you want payouts above cash in the bank, search for high yielding candidates via the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com