
How Raised Revenue Guidance Will Impact Granite Construction (GVA) Investors
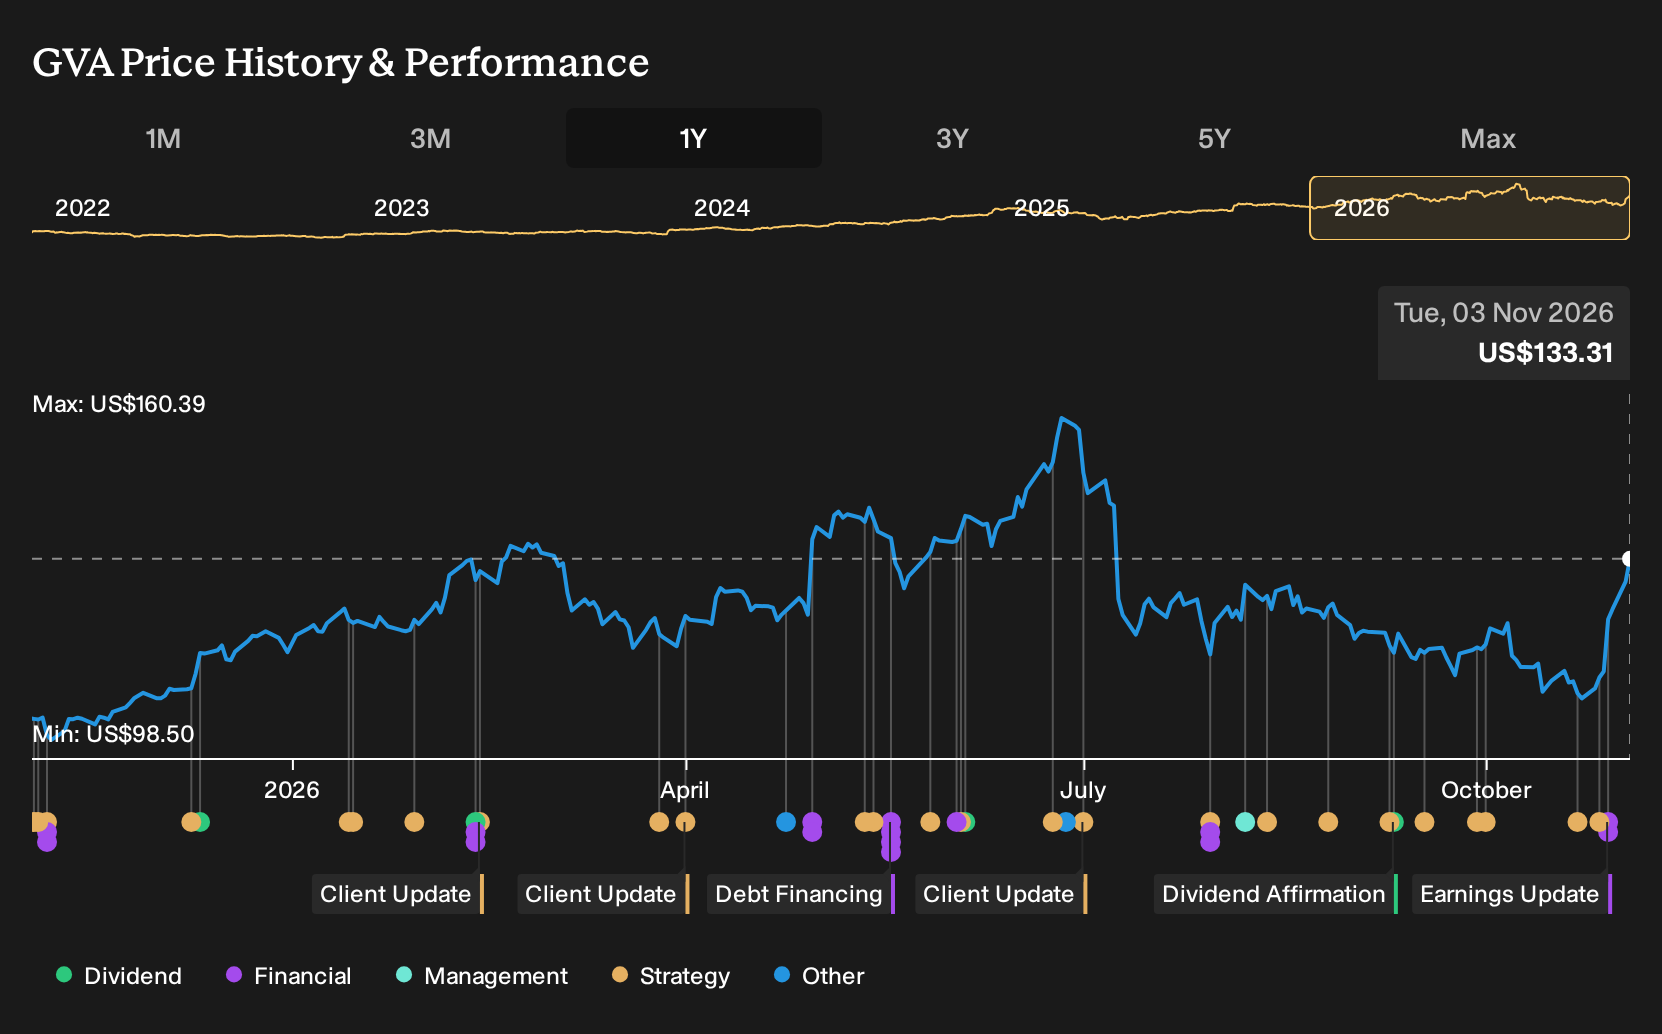
- Granite Construction reported third quarter 2026 sales of US$1,766.33 million with net income of US$3.21 million and raised full year revenue guidance to a range of US$5.4 billion to US$5.5 billion.
- The business paired higher reported sales and fresh contract awards with a nine month net loss of US$316.65 million, highlighting pressure on profitability despite a growing project pipeline.
- Next, the focus will shift to how Granite Construction's raised 2026 revenue guidance influences its existing investment narrative around margin quality.
Scan beyond Granite Construction and compare other contractors that have strong backlogs and more focused profitability profiles using our curated list of list of solid balance sheet and fundamentals (23 results)
Granite Construction Investment Narrative Recap
To stay invested in Granite Construction, you need to be comfortable with a story where revenue is growing but profitability is under strain. The third quarter showed higher sales and a small profit, while the nine month period still carried a sizeable net loss. The key short term swing factor is whether management can stabilize margins in Construction and Materials while working through a larger backlog.
The raised 2026 revenue guidance, on its own, does not resolve that profitability question. It signals management’s confidence in converting the project portfolio into top line, but the main risk remains cost pressure, weather and execution issues that could keep cash gross margins from improving and leave interest coverage tight while losses persist.
The most relevant update for this earnings print is the new full year revenue guidance of US$5.4b to US$5.5b, nudged up from US$5.3b to US$5.5b. That tweak matters because it ties directly into the core thesis that Granite Construction can use its public infrastructure exposure and larger backlog to support scale while working on margin repair.
For you as a shareholder, that guidance sits beside a nine month net loss of US$316.65 million, so it is hard to ignore execution risk. The higher top line range may help support utilization of quarries and plants and feed best value contracts, but the real catalyst remains clear progress on project mix and cost control rather than just hitting the revenue band.
Granite Construction’s analyst narrative points to forecast revenue of US$6.5b and projected earnings of US$687.3 million by 2029, based on an assumed yearly revenue growth rate of 9.6%. That outlook compares with current earnings that reflect a loss of US$164.9 million, so the consensus implies an earnings swing of roughly US$852 million from today’s level.
Uncover why Granite Construction's fair value indicates a 29% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Granite Construction, the bullish twist in the alternate story is the catalyst of bigger federal and data center work. The most optimistic analysts were already penciling in about US$6.5b of revenue and earnings of US$594.4 million by 2029 before this earnings surprise. That is a very upbeat script compared with the current loss-making picture. Your takeaway is simple: opinions differ widely, and this fresh guidance and contract news could push those forecasts and narratives in new directions, so it is worth comparing several viewpoints before deciding where you stand.
Explore 3 other Granite Construction fair value estimates, including one that suggests as much as 93% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Granite Construction research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Granite Construction. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Granite Construction's overall financial health at a glance.
Looking For More Investment Ideas Beyond Granite Construction?
Once you have formed a view on Granite Construction, it can help to line that up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for businesses that match the balance sheet strength, valuation style or dividend focus you care about most.
- If capital preservation is high on your list, compare Granite Construction with companies that score well on resilience and financial stability using our 30 resilient stocks with low risk scores.
- For investors hunting for value opportunities, set Granite Construction alongside other candidates that pair solid fundamentals with attractive pricing through our 35 high quality undervalued stocks.
- If reliable income streams appeal to you, weigh Granite Construction next to companies that offer robust payouts by checking our 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com