
Why BFF Bank Bears Were Right Before A 82% Drop
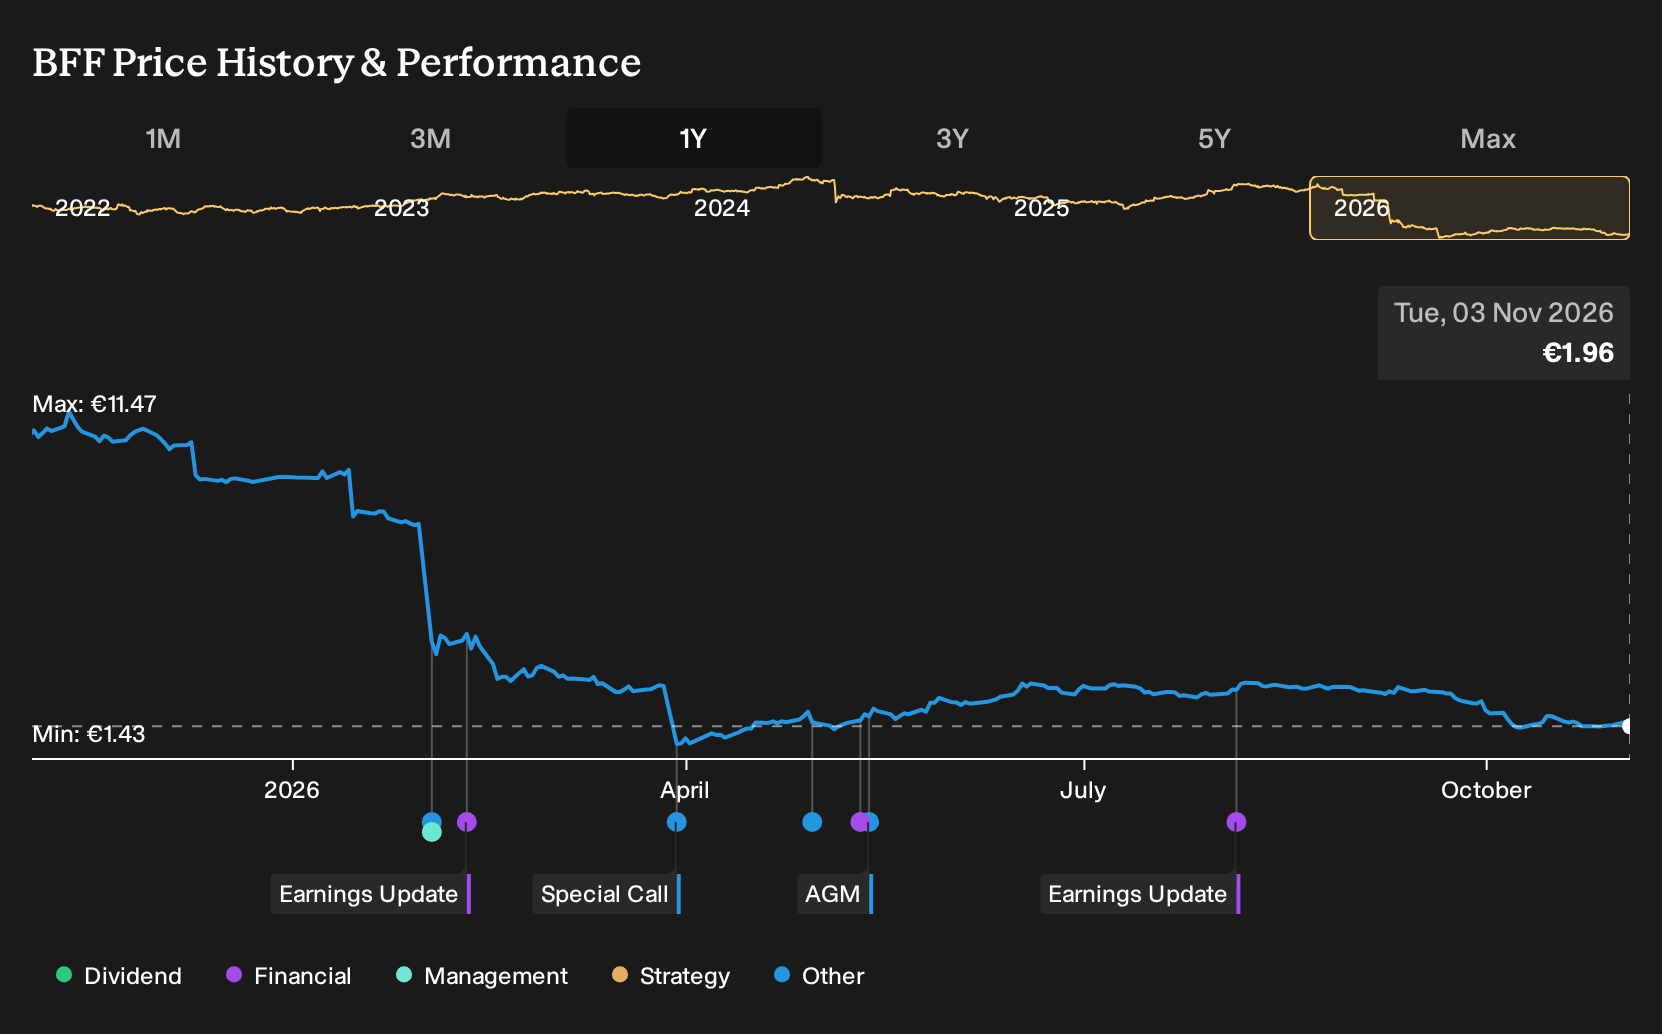
If you only skimmed headlines, the 2026 Q2 update from BFF Bank might have looked puzzling. Total revenue for the quarter was €109.174 million, while net income excluding extra items was €1.93 million and the net margin was 1.8%. Investors who held BFF Bank over the past year are down 81.7%, including dividends. If you had been deciding whether to buy on 3 November 2025, how much of this gap between solid top line and thin profit was already visible in the earlier debate over digital disruption, regulation and healthcare factoring concentration?
If the move has made BFF Bank harder to judge, start where the gap is still open and scan 199 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On BFF Bank
The shares cost €10.9 at the start of the period, and anyone looking at BFF Bank then had to pick between two very different stories about the next few years.
The bullish view pointed to a Fair Value of €13, a rough guide to what that camp thought the stock could be worth if its assumptions played out. This view was built on revenue growing 6.8% a year and digitalization helping Italian and French contracts translate into higher efficiency.
The bearish case pointed to a Fair Value of €7.7 and focused on digital disruption and tighter European rules as real hazards. Exposure to Italian public sector and healthcare receivables was seen as a concentration risk that could unsettle revenue if policy or payment terms shifted.
What The Results Changed For The BFF Bank Story
The clearest new fact was operational. BFF Bank reported Q2 2026 revenue of €109.174 million, slightly above the €106.287 million booked a year earlier, which supported the optimistic view that activity could hold up. Profitability told a different story. Net income excluding extra items fell to €1.93 million and net margin dropped from 32.9% to 1.8%, which backed the cautious case on earnings quality. Overall, the evidence cut both ways.
The episode turned on one assumption. Bulls and bears both talked about margins, so the key check for any similar lender is the net margin trend against earlier claims, not just whether revenue lines move in the hoped-for direction.
What You Would Be Paying For In BFF Bank Today
At a share price of €1.96, this Narrative sees Fair Value above the current level and bases that view on how BFF Bank is reweighting its business toward lower risk weighted, fee driven activities rather than pure loan growth.
For that higher figure to align, a buyer today would need to assume that BFF Bank can continue derisking factoring and lending while preserving the profitability of its core franchises.
"The main thing that has to go right is that BFF Bank continues to execute on deleveraging and derisking in factoring and lending, including managing calendar provisioning and court ruling exposures, without eroding the profitability of its core franchises."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 30% below our estimate - turns integrated AI and cloud infrastructure into subscription and usage-based revenue.
- Company 2 - 45% below our estimate - pushes marketing and hiring to shift sales toward overseas stores and digital channels.
- Company 3 - 42% below our estimate - expands from underwear into sports apparel as health conscious consumers seek performance gear.
Three companies from the same screener. Open all 195 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com