
Why Element Fleet Management (TSX:EFN) Is Back In The Spotlight
Element Fleet Management (TSX:EFN) just packed several developments into a short stretch. Fresh Q3 2026 earnings, the launch of Element Pay, and an expanded Waymo partnership are now shaping how investors frame the stock.
Despite a 1-day share price return of 1.36% and a 7-day share price gain of 2.84% that likely reflect fresh interest around Element Pay and the Waymo expansion, Element Fleet Management’s year to date share price return is down 37.48%. The 1-year total shareholder return has declined 38.59%, even as the 3-year and 5-year total shareholder returns of 18.44% and 78.04% point to a very different long-run picture of how the business has rewarded patient holders.
Scan beyond Element Fleet Management and identify other potential rebound stories with our curated list of 4 high quality undervalued stocks that share a mix of solid fundamentals and pricing pressure.
Element Fleet Management is now trading well below its highs after a sharp reset, even as earnings, Element Pay and the Waymo tie-up draw fresh attention. Is most of the repricing already done, or is meaningful upside still ahead?
Most Popular Narrative: 44% Undervalued
Against a last close of CA$22.42 for Element Fleet Management, the most followed narrative anchors on a fair value of CA$40.30, built using a 7.67% discount rate and explicit forecasts for revenue, earnings and margins.
The successful expansion into services such as advanced telematics, AI-driven analytics, and new mobility offerings through Element Mobility and partnerships (e.g., Samsara and Modis) positions the company to benefit from the growing demand for data-driven fleet optimization and outsourced mobility solutions. This is expected to support long-term recurring services revenue growth and improved net margins.
See why 12 investors see Element Fleet Management as 44% undervalued.
Result: Fair Value of CA$40.30 (UNDERVALUED)
Still, analyst concerns around Element Fleet Management’s high debt load and softer service growth mean any hit to funding costs or utilization could quickly challenge that potential upside.
Find out about the key risks to this Element Fleet Management narrative.
Another View: What Element Fleet Management’s P/E Ratio Signals
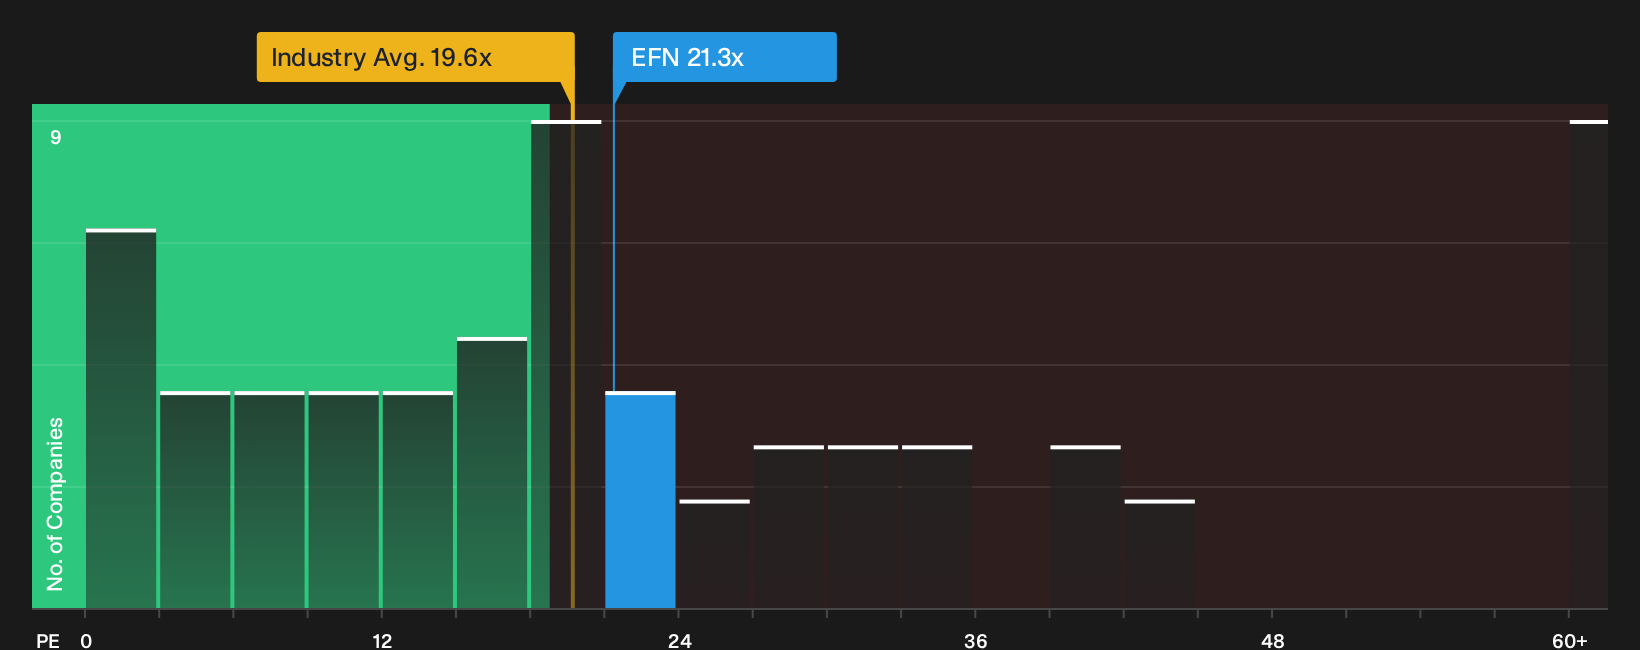
Step away from fair value models for a moment and look at the simple P/E. Element Fleet Management trades at 21.3x earnings, above the North American Commercial Services average of 19.6x, yet below a fair ratio estimate of 36.1x that the market could move toward over time.
In practice, that mix of richer pricing than the wider industry, cheaper terms than closer peers at 33.8x, and a fair ratio well above the current level frames both valuation risk and possible opportunity. Which side you lean toward depends on how much faith you place in Element Fleet Management’s future earnings path and balance sheet resilience.
To pressure test that view against the earnings multiple and see what the numbers imply in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far, right, with fresh products, new partnerships, and a sharp reset in Element Fleet Management’s share price all pulling sentiment in different directions. If you want to move quickly and shape your own view using the underlying data, start with the 3 key rewards and 4 important warning signs.
Looking for more Element Fleet Management style ideas?
If Element Fleet Management has your attention, do not stop here. Broaden your watchlist with a few targeted screens that spotlight different types of opportunities.
Use the Simply Wall St Screener to uncover fresh ideas that match your own risk, income, and quality preferences before the crowd catches on.
- Target potential value rebounds by scanning a curated set of 4 high quality undervalued stocks where pricing pressure contrasts with underlying fundamentals.
- Strengthen your income stream by focusing on 3 dividend fortresses that aim to pair higher yields with staying power.
- Reduce portfolio stress by filtering for 9 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com