
What Magnite Stock ChatGPT Ad Partnership Means For Shareholders
- Comscore previously announced an expanded partnership with Magnite that brings Proximic’s Predictive Audiences, contextual intelligence and ID free activation into the SpringServe video platform used to manage and monetize CTV inventory.
- Proximic’s AI driven audience tools sit inside SpringServe, giving publishers a way to combine first party data with contextual signals for ID free, privacy focused CTV targeting across formats such as pause ads.
- The focus now turns to how Magnite’s reported OpenAI collaboration around ChatGPT ad buying could reshape the broader investment narrative.
Scan how other AI focused ad-tech players are positioned by moving from Magnite’s ChatGPT and CTV headlines to a curated set of 41 AI small caps that could be setting up their next breakout.
Magnite Investment Narrative Recap
To own Magnite, you need to believe that independent CTV and programmatic infrastructure can keep gaining share with major streamers, OEM partners and commerce media buyers, even as budgets shift around formats and channels. The near term bull case rests on sustaining contribution ex TAC from CTV while keeping adjusted EBITDA margins and free cash flow on a firm footing.
The biggest swing factor right now is whether deeper programmatic adoption with large CTV clients offsets pressure in weaker areas like web display and any pullback in brand spending. The main risk is concentration. If key streaming or agency partners push harder into vertically integrated stacks or tougher terms, Magnite’s earnings power could reset lower.
The reported OpenAI collaboration around ChatGPT ad buying is the announcement that ties closest to the current narrative. Advertisers being able to use Magnite’s existing software to buy and manage ChatGPT ads puts the platform in the early mix for generative AI search and chat monetization, alongside CTV and DV+ channels already on the system.
Operationally, this kind of integration aligns with two existing catalysts. First, Magnite’s push to move more audience decisioning toward the supply side, where high intent environments like chat or commerce media can feed contribution ex TAC. Second, its AI and agent based products, which already handle millions of dollars of spend, could benefit from a broader pool of impressions if execution on the OpenAI work stays tight and reliable.
Magnite Forecasts And Analyst Assumptions
Magnite's current story in the market is anchored in what analysts think its income statement could look like a few years from now rather than just the OpenAI headlines. Consensus models build in revenue growth of 7.7% each year over the next 3 years, paired with a margin profile that moves from 22.5% today to 14.7% by 2029. That combination leaves earnings in the projections at US$136.5 million by 2029 compared with US$166.9 million today, which implies an earnings decline of US$30.4 million even as top line estimates keep rising.
Those profit expectations sit inside a very wide range. The most optimistic forecast has Magnite generating US$172.9 million of earnings by 2029, while the most cautious view sits at US$66.1 million. For investors, that level of dispersion underlines how much uncertainty remains around how CTV, DV+ and new channels like ChatGPT ad supply will ultimately translate into profit dollars rather than just revenue volume.
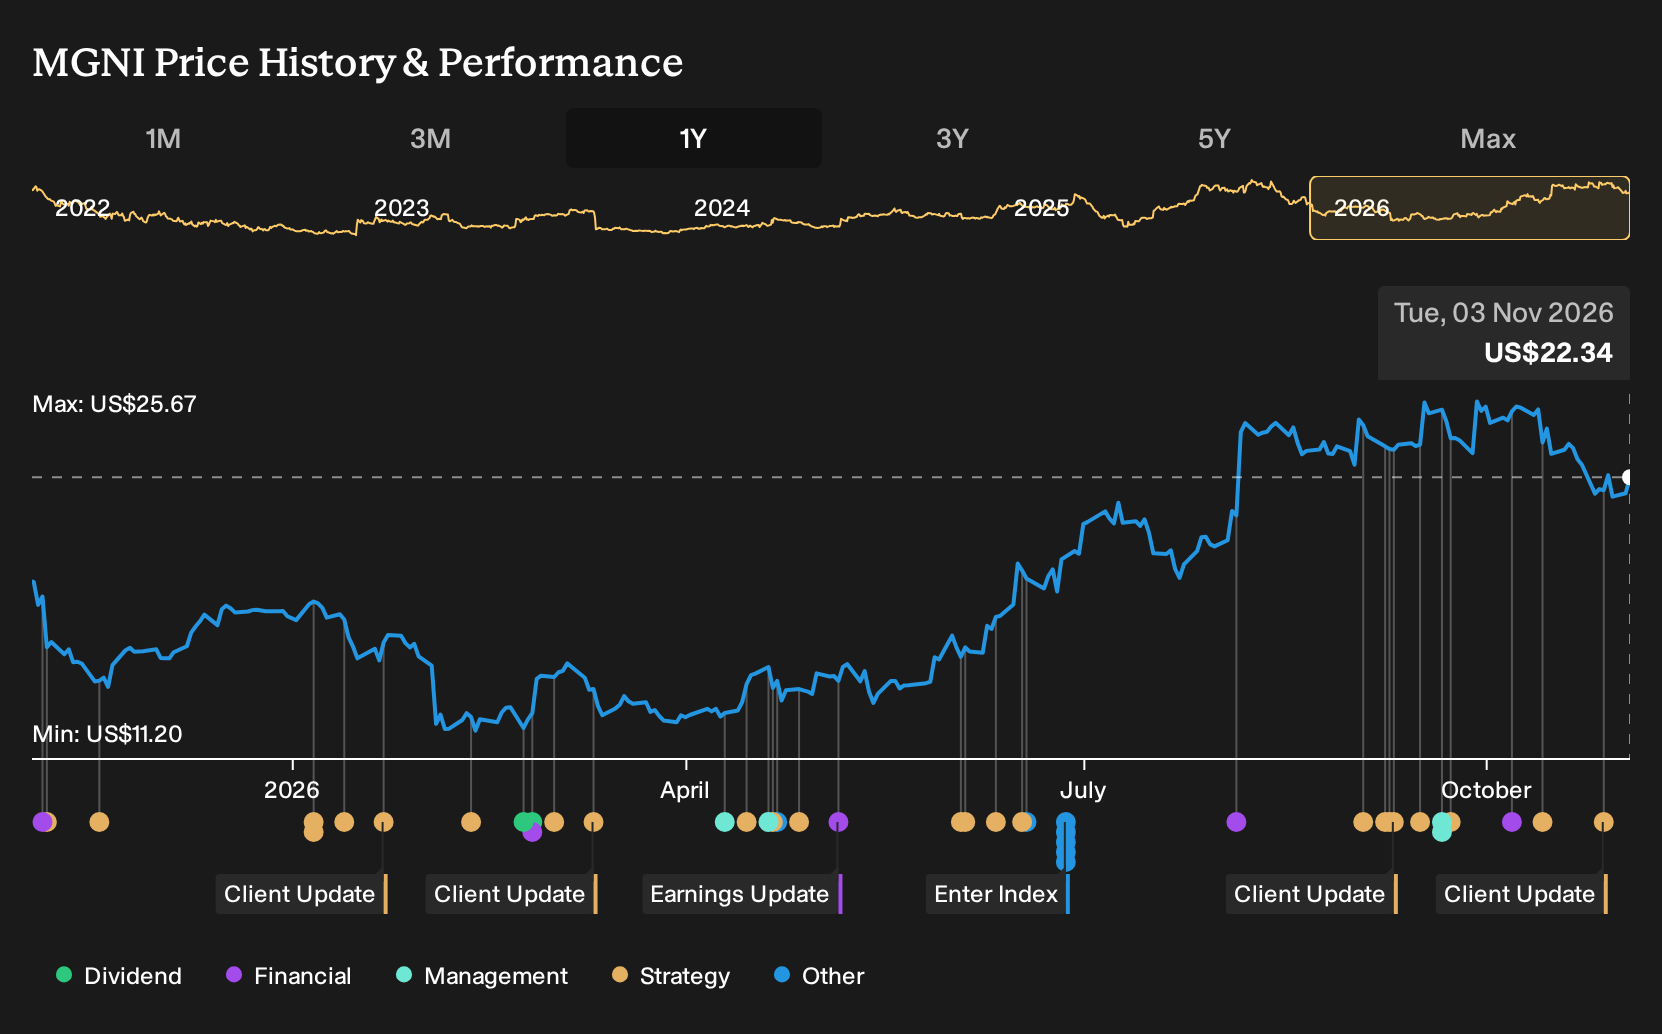
Valuation work built on these forecasts points to a 2029 revenue figure of US$926.0 million and the same US$136.5 million of earnings, backed out using a discount rate of just under 10%. Under that framework, the equity would need to trade on a P/E multiple of 40.9x those 2029 earnings compared with 20.1x today and a current US Media sector P/E of 22.9x. The current analyst price target of US$29.67, versus a recent share price of US$23.37, assumes the business is worth more than the market price even with lower earnings built into the models.
Magnite's forecast profile therefore mixes revenue growth, margin compression and a higher implied multiple. That setup tends to appeal to investors who put more weight on product positioning and new channels like CTV and AI powered ad buying than on near term earnings trends. It can be less appealing for readers who prefer cleaner trajectories in both profitability and valuation multiples.
Magnite's narrative projects US$926.0 million revenue and US$136.5 million earnings by 2029. This implies 7.7% yearly revenue growth and an earnings decline of US$30.4 million from current earnings of US$166.9 million.
Discover why Magnite's fair value points to a 33% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
You are seeing two very different stories about Magnite. The bullish angle treats AI driven audience tools and OpenAI style partnerships as a way to reach US$1.0b revenue and US$172.9 million of earnings by 2029. Others stay closer to US$926.0 million and US$136.5 million. Both views were formed before this news, so opinions may evolve. Consider exploring several alternatives yourself.
Explore 3 other Magnite fair value estimates, including one that suggests as much as 33% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Magnite research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Magnite. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magnite's overall financial health at a glance.
Looking For More Ideas Beyond Magnite?
If Magnite has sharpened your thinking about ad tech and AI, it can help to put that thesis alongside a few very different opportunities. Use the Simply Wall St Screener to quickly surface stocks that fit the risk, income or balance sheet profile you want, then compare those setups to what you see in Magnite.
- For investors who want growth potential without ignoring financial strength, scan a 19 high quality undiscovered gems that combines quality fundamentals with the possibility of being earlier in the market spotlight.
- If capital preservation and smoother return profiles matter most to you, filter for 30 resilient stocks with low risk scores that score well on resilience and business stability.
- Income focused readers who care about cash generation and staying power can review a list of solid balance sheet and fundamentals (23 results) that pairs durable finances with meaningful shareholder payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com