
Greif (GEF) Exits Coated Recycled Board, Is The Stock Cheap Or Expensive?
Greif (GEF) just paired fresh quarterly results with a portfolio shake-up, reporting higher adjusted EBITDA and net income excluding adjustments, while moving to exit its Coated Recycled Board business and reaffirming cash dividends.
Greif’s share price has eased in the short term, with the stock down 2.3% over the past week and 9.8% over 90 days, even as investors who stayed the course saw a 1-year total shareholder return of 48.1%. This suggests that recent momentum has cooled while the longer record remains strong.
Compare Greif’s portfolio reset and dividends with other packaging and materials players by scanning our hand picked 35 high quality undervalued stocks that combine cash generation with balance sheet strength.
Greif is cutting costs, reshaping its portfolio and still paying cash to shareholders while the share price has slipped in recent months. Are investors cooling on the story faster than the business has changed, or is the reset already reflected in the price?
Most Popular Narrative: 6.8% Undervalued
Greif’s most followed valuation storyline pegs fair value at $87.20, a touch above the recent $81.25 close. This frames current pricing as modestly below that narrative estimate while still grounded in relatively conservative assumptions about growth and margins.
The combination of low leverage around 1.1x, extended debt maturities to 2031 at a 3.14% rate and ongoing share repurchase authorizations of several hundred million dollars, alongside a higher quarterly dividend and a roughly 50% free cash flow conversion target, positions Greif to keep returning capital to shareholders while still funding projects that can influence long term earnings power.
See why 7 investors see Greif as 7% undervalued.
Result: Fair Value of $87.20 (UNDERVALUED)
Still, Greif’s heavier reliance on core packaging volumes after exiting containerboard, along with any extended industrial softness, could undercut the cost savings story investors are leaning on.
Find out about the key risks to this Greif narrative.
Another View: Greif Looks Expensive On Earnings
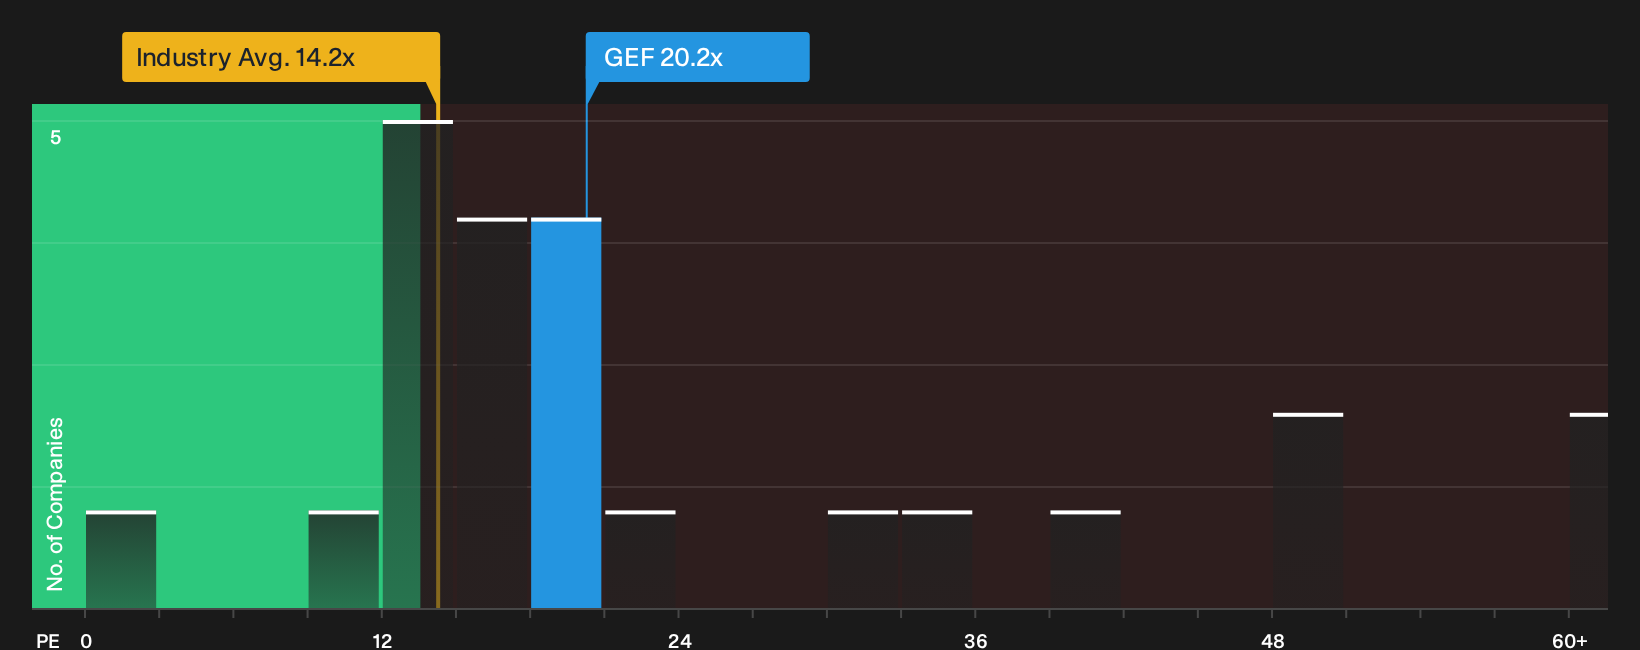
Greif may screen as 6.8% undervalued on fair value estimates around $87.20, yet the share price tells a different story when earnings multiples are in focus. The stock trades on a P/E of 20.2x, while the fair ratio sits at 14.4x and the global packaging group averages 14.1x.
That gap points to investors already paying a premium for Greif’s profile, which can limit upside if growth or margins track closer to industry norms rather than the stronger narrative. The question is whether you view that higher multiple as justified resilience or as valuation risk that leaves less room for error.
To pressure test that view against the earnings multiple and see how the market could move closer to the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Greif’s mixed signals on valuation, portfolio change and income can feel messy, yet this is exactly where careful investors often find their edge. Act before the story hardens and weigh both sides of the ledger by reviewing the 2 key rewards and 3 important warning signs
Looking for more Greif sized investment ideas?
Greif is just one potential opportunity. If you want a broader watchlist that matches your style, these filters can surface other ideas before the crowd moves.
- Target resilient returns by focusing on strong cash generators with support from the balance sheet through a list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality where fundamentals and valuation both matter by scanning a curated 19 high quality undiscovered gems.
- Aim to smooth the ride in choppy markets by focusing on a 30 resilient stocks with low risk scores that keeps risk scores front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com