
Park Hotels & Resorts (PK) Heads Into Earnings With Fair Value Still In Question
Wall Street’s attention is on Park Hotels & Resorts (PK) ahead of its third quarter 2026 earnings on 4 November, with consensus pointing to modest profitability on revenue of about US$603.9 million.
Park Hotels & Resorts shares have eased slightly in the past week but still carry strong momentum, with a 30 day share price return of 7.66% and a year to date gain of 55.25%. The 1 year total shareholder return of 81.83% points to investors reassessing both income potential and risk around the lodging REIT story.
See how Park Hotels & Resorts compares with other real estate opportunities showing strong momentum and potential mispricing in our curated list of 35 high quality undervalued stocks
Bulls see Park Hotels & Resorts as a discounted play on premium real estate, while bears focus on recent losses and sector risk. Which story does the current valuation actually support next?
Most Popular Narrative: 4% Overvalued
Park Hotels & Resorts last closed at $16.72, slightly above the $16.06 fair value implied by the most followed narrative that applies an 8.69% discount rate. This leaves very little margin for investors who want a clear gap between price and value.
The current valuation implies the share price already reflects a fairly valued, bullish view on Park Hotels & Resorts, where investors are paying for continued portfolio pruning, the ramp from Bonnet Creek, Casa Marina and Royal Palm, and the prospect of narrowing the cited NAV discount over time.
See why 16 investors see Park Hotels & Resorts as 4% overvalued.
Result: Fair Value of $16.06 (OVERVALUED)
Still, the current story around Park Hotels & Resorts is vulnerable if Hawaii underperforms for a longer period or if recent heavy renovation spending fails to earn its keep.
Find out about the key risks to this Park Hotels & Resorts narrative.
Another View: Park Hotels & Resorts Through Sales-Based Ratios
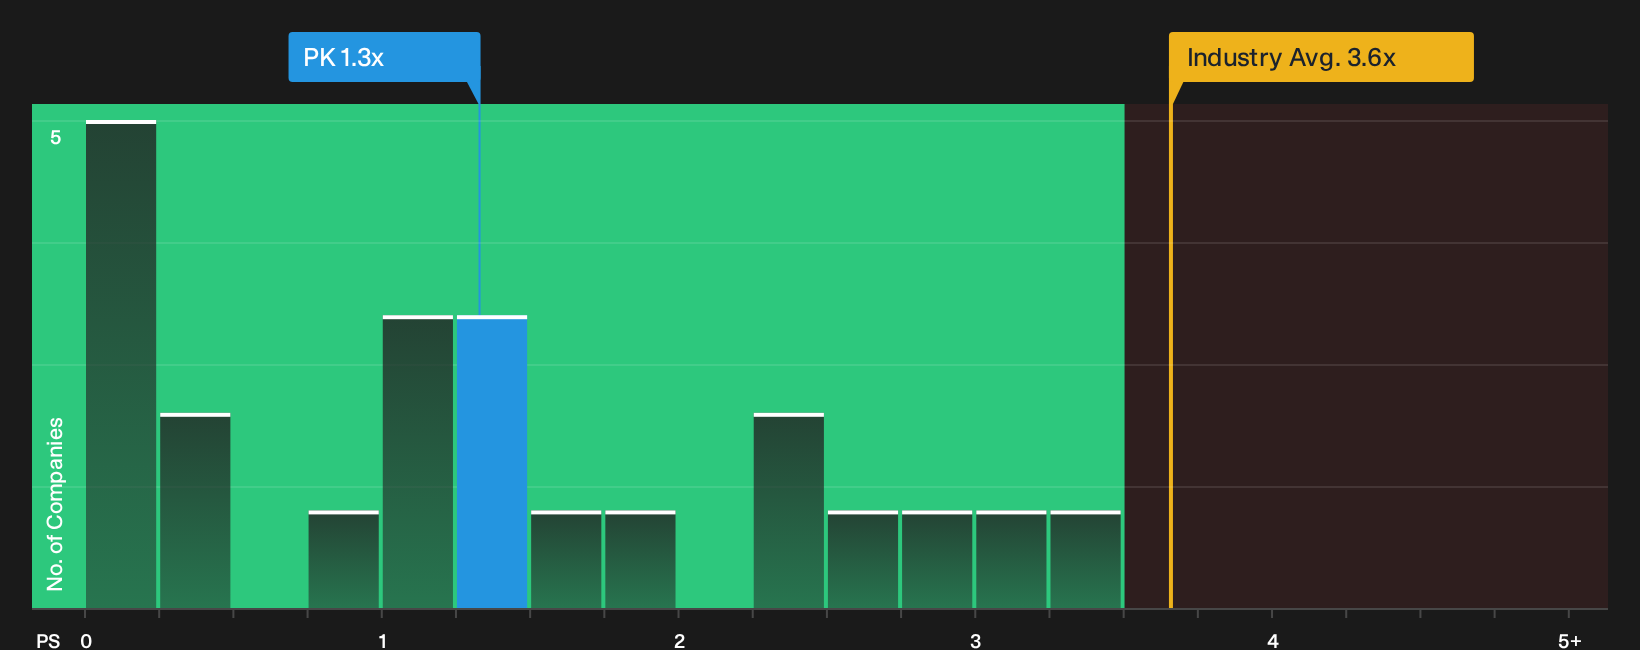
The fair value narrative for Park Hotels & Resorts argues the stock is about 4% overvalued at $16.72. Sales based ratios present a different perspective. With a P/S of 1.3x versus a fair ratio of 2.3x, and peer and industry averages of 2.4x and 3.6x, the implied gap points to either a pricing opportunity or a clear warning that the market is discounting risk. Which explanation do you think fits better?
To stress test that question against hard numbers, have a look at the valuation breakdown in our ratio based view of Park Hotels & Resorts, including how it lines up against peers and the wider Hotel and Resort REITs group, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Park Hotels & Resorts only matters if you let someone else make the call for you. Move quickly, review the numbers, and then weigh up the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Park Hotels & Resorts?
If Park Hotels & Resorts has you thinking more carefully about price, quality, and risk, use that momentum to scan wider and find your next move before everyone else.
- Target higher potential upside by checking companies that screen as undervalued on both quality and price through the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on payouts that aim for resilience with the 4 dividend fortresses.
- Reduce portfolio shock by concentrating on financially robust businesses using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com