
Vishay Intertechnology (VSH) Draws Fresh Valuation Focus, Is The Pullback Making It Cheap?
Vishay Intertechnology (VSH) moved into focus after the FPA Queens Road Small Cap Value Fund sharply reduced its position, even as the semiconductor manufacturer reported solid fundamentals and broad-based demand across electric vehicles, industrial electrification, and data centers.
Recent trading has been choppy. Vishay Intertechnology’s share price rose 6.66% in the last session to US$27.22 but is down 28.71% over the past month and 17.96% over the last 90 days, following a 78.02% year to date share price return and a 72.09% total shareholder return over one year. This suggests earlier enthusiasm has cooled as investors reassess how much of the electric vehicle, industrial and data center story was already reflected in the valuation.
Scan other chips and components stocks that match the Vishay Intertechnology story of strong end market demand and recent volatility by reviewing our curated 35 high quality undervalued stocks.
Vishay Intertechnology now trades at a sizeable discount to both intrinsic value estimates and analyst targets after that sharp pullback. Is this caution rooted in real concern, or has the reset gone too far on price?
Most Popular Narrative: 32% Undervalued
Against the last close at $27.22, the most followed narrative for Vishay Intertechnology points to a fair value of $40.00, so the current reset in the price is being framed as a sizable discount that only makes sense if the company struggles to profitably fill its new capacity.
With major multi year investments in capacity expansion now supported by nearly $900m already deployed, a planned 2026 capex range of $400m to $440m, and new Western facilities such as the German 12 inch fab and Newport UK fab ramping, Vishay Intertechnology is building headroom for future revenue growth and operating leverage as utilization improves.
See why 13 investors see Vishay Intertechnology as 32% undervalued.
Result: Fair Value of $40.00 (UNDERVALUED)
Still, the Vishay Intertechnology story can quickly wobble if heavy capex keeps free cash flow negative and new fabs like Newport struggle to reach profitable utilization.
Find out about the key risks to this Vishay Intertechnology narrative.
Another View: Vishay Intertechnology Looks Expensive On Earnings
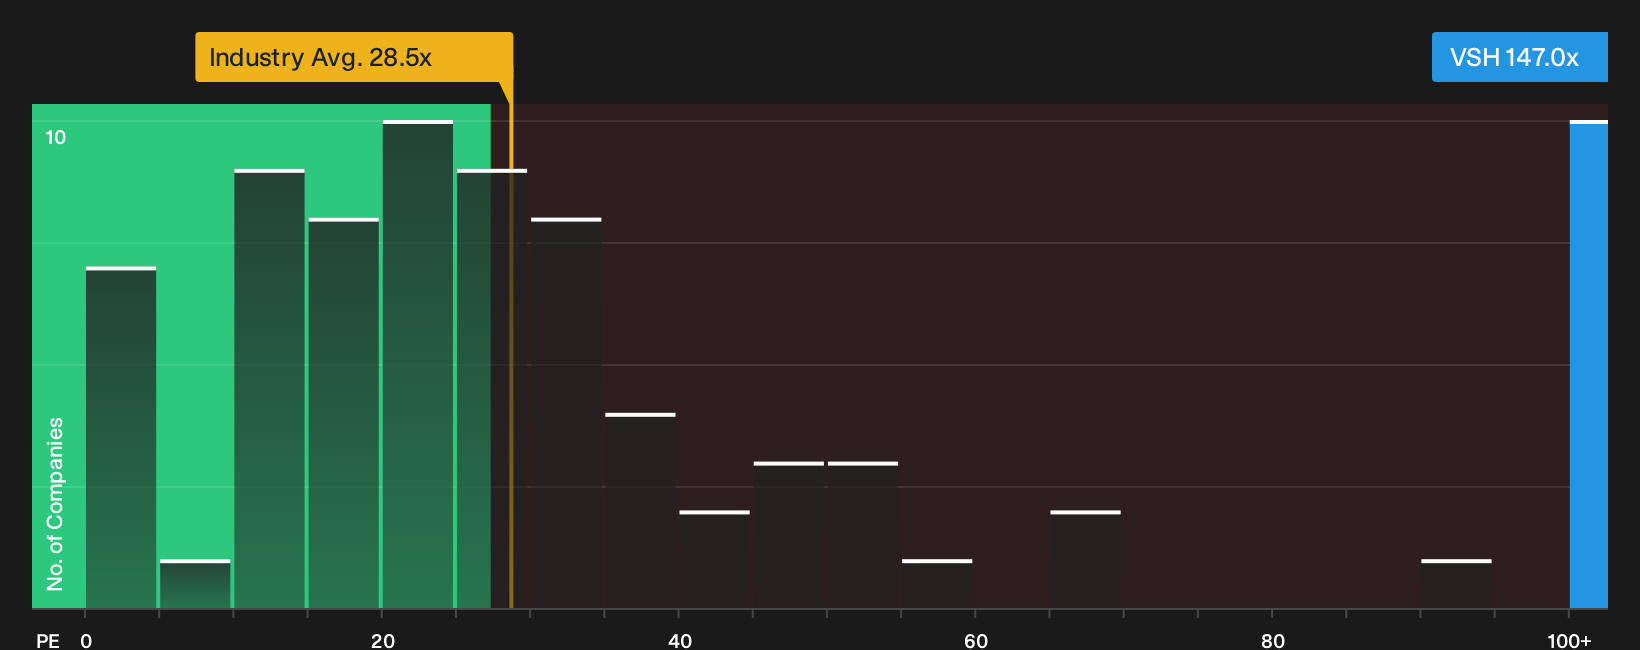
On one side, Vishay Intertechnology screens as attractive on fair value estimates and discounted cash flow, with the shares priced 51.6% below the future cash flow value of $56.26. On the other, the current P/E of 147x is far above the US Electronic industry on 28.7x, peers on 40.4x, and even the fair ratio of 73.2x. That gap points to real valuation risk if the earnings ramp does not arrive as expected.
See what the numbers say about this price in our valuation breakdown, then decide which signal you trust more, the cash flow model or the earnings multiple, with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Vishay Intertechnology can pull you in both directions, so move quickly from headlines to hard data and shape your own call by weighing its 3 key rewards and 4 important warning signs.
Looking for more Vishay Intertechnology style ideas?
If you stop with Vishay Intertechnology, you miss the chance to line up fresh angles, compare opportunities, and pressure test your conviction across multiple quality filters.
- Target resilient balance sheets and cleaner fundamentals by jumping into our list of solid balance sheet and fundamentals (23 results). It can help you filter for financial strength before the crowd notices.
- Hunt for mispriced quality by scanning the 35 high quality undervalued stocks. It filters for businesses where fundamentals and current prices may be out of sync.
- Build a steadier income stream by checking our 4 dividend fortresses. It highlights companies offering higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com