
First Commonwealth Financial (FCF) Lifts Dividend And Buyback On A Fair Value Debate
First Commonwealth Financial (FCF) just packed several capital moves into one day, pairing third quarter results with a higher cash dividend and a larger share repurchase authorization.
Recent price action suggests investors are weighing these capital returns against higher credit costs. The share price is around $21.17, with a year to date share price return of 26.24% and a 1 year total shareholder return of 39.83%. The 3 year total shareholder return of 79.37% points to momentum that has built over a longer stretch, despite a modest 90 day share price pullback of 2.35%.
Surf 35 high quality undervalued stocks that, like First Commonwealth Financial, combine visible capital returns with earnings progress and may be setting up for their next move.Investors now face a split view on First Commonwealth Financial. One side sees rising earnings, a higher dividend, and fresh buybacks; the other worries about credit costs. Which case does the current valuation lean toward?
Most Popular Narrative: 12% Undervalued
The most followed narrative estimates First Commonwealth Financial's fair value at $24.07. This is above the recent $21.17 close and presents the latest dividend and buyback moves in the context of a discounted share price.
Strong capital levels, with CET1 at 12.6% and a tangible common equity ratio of 9.9%, combined with an expanded US$75 million repurchase authorization and an 11-year record of dividend increases, give First Commonwealth Financial room to keep using buybacks and dividends to support per share earnings metrics.
See why 3 investors see First Commonwealth Financial as 12% undervalued.
Result: Fair Value of $24.07 (UNDERVALUED)
Still, the bullish narrative on First Commonwealth Financial can crack if loan growth keeps getting offset by large commercial payoffs, or if deposit competition forces meaningfully higher CD rates that squeeze its 4% net interest margin.
Find out about the key risks to this First Commonwealth Financial narrative.
Another View: What The P/E Ratio Says About First Commonwealth Financial
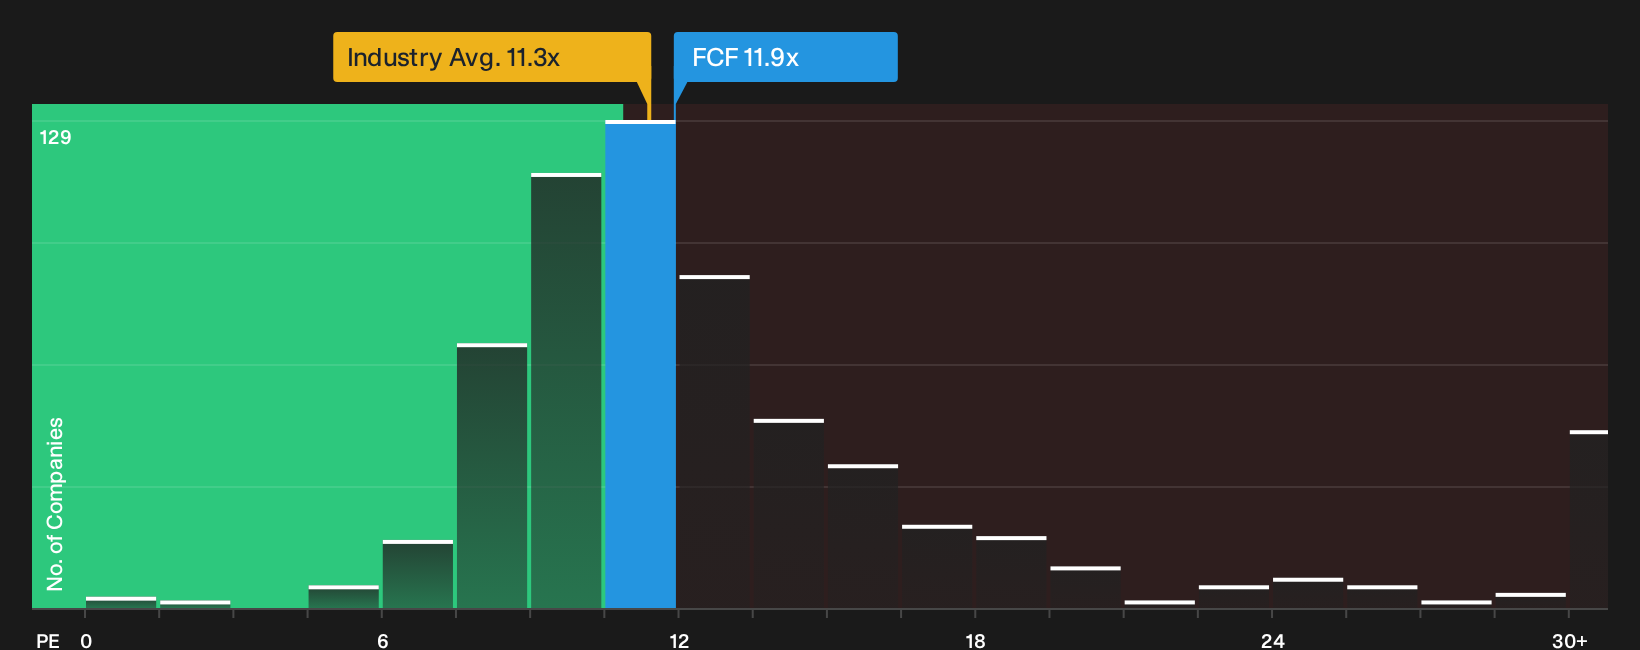
There is a different message coming from the plain P/E math. First Commonwealth Financial trades at 11.9x earnings, which is slightly higher than the US Banks industry on 11.3x and very close to its own fair ratio of 12.1x. That points to a stock where much of the easy valuation gap may already be reflected in the price, so how much room is left if sentiment cools?
For investors who prefer to benchmark against earnings multiples and peer comparisons, this kind of setup raises practical questions about upside and downside room, especially if growth or credit costs come in differently to what the market is currently factoring in, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on First Commonwealth Financial can pull you in either direction, so consider reviewing the numbers and forming your own stance with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond First Commonwealth Financial?
If First Commonwealth Financial has your attention, do not stop here. Broaden your watchlist with other opportunities that match clear financial traits and focused return profiles.
- Target potential mispricing by scanning companies that pair strong fundamentals with discounted valuations using the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing higher yielding payers with resilient payout profiles through the 4 dividend fortresses.
- Prioritize resilience and capital protection by filtering for companies with lower risk profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com