
AppFolio (APPF) Could Be 9% Undervalued Following Strong Q3 Earnings And Higher 2026 Guidance
AppFolio (APPF) drew investor attention after reporting third quarter revenue of US$295.69 million and net income of US$45.98 million, alongside higher full year 2026 revenue guidance of US$1.122 billion to US$1.127 billion.
Despite the upbeat 2026 guidance, AppFolio’s recent trading tells a mixed story. The share price rose about 16% over the past 90 days and 10% over the last month, hinting at rebuilding momentum. However, year to date the share price return is slightly down and the 1 year total shareholder return has also declined.
Spot similar earnings momentum and guidance stories by scanning our curated list of 19 high quality undiscovered gems, which, like AppFolio, have recently reported stronger revenue and profit figures.
So is AppFolio’s recent rebound a clear signal of stronger earnings and higher 2026 guidance, or more a snapback in sentiment after a weak year-to-date and one-year stretch? The valuation work starts there.
Most Popular Narrative: 9% Undervalued
AppFolio’s most followed valuation story pegs fair value at $245.91 per share, above the last close of $223.74. This frames today’s rebound as only a partial catch up to that narrative.
The numbers imply a share price that already reflects strong revenue, margin, and cash flow delivery, yet still prices AppFolio below what this narrative views as a fair outcome if AI-led automation, platform consolidation, and resident monetization continue to compound.
See why 21 investors see AppFolio as 9% undervalued.
Result: Fair Value of $245.91 (UNDERVALUED)
Still, the bullish AppFolio narrative can break if heavier reliance on costlier AI and payments infrastructure squeezes margins, or if insider selling signals softer internal confidence.
Find out about the key risks to this AppFolio narrative.
Another View On AppFolio’s Valuation
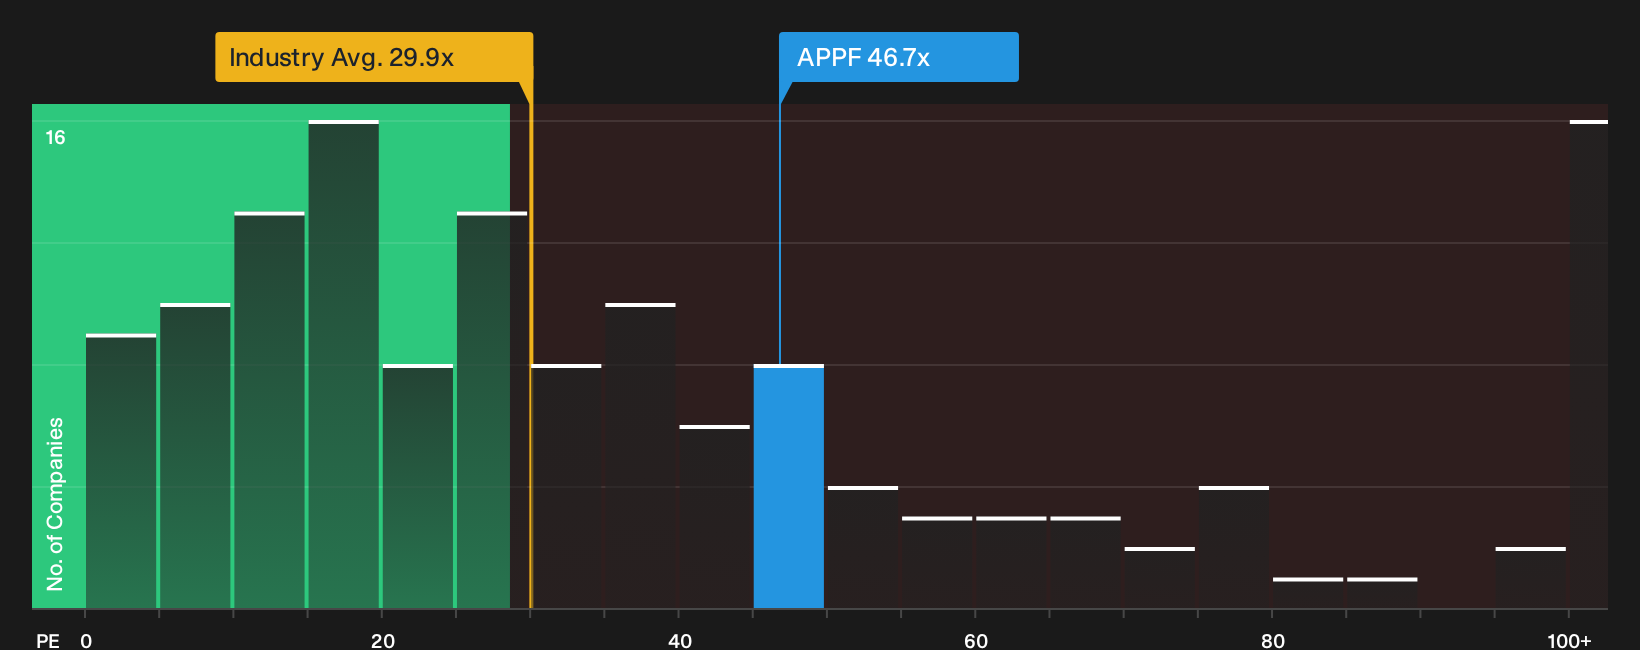
The first narrative leans on a fair value estimate of $245.91 per share. A different lens comes from the current P/E of 46.7x, which is well above the fair ratio of 32.8x, the US Software industry at 31.2x, and peers at 23.6x. That richer multiple points to valuation risk if sentiment cools before earnings catch up. How comfortable are you paying up for this kind of growth story?
For a closer look at how this pricing gap lines up with the underlying numbers, check out the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on AppFolio’s rebound or a clean setup for the next move: either way the data is on the table and it pays to check it yourself while sentiment is still in flux. To frame that view against both the upside and the downside, start with 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond AppFolio?
If AppFolio has sharpened your focus, do not stop there. Use the data to your advantage and let fresh ideas come to you before the crowd.
- Target income resilience by reviewing a curated pool of yield opportunities through the 4 dividend fortresses built from companies with stronger payouts.
- Hunt for mispriced quality by scanning the 35 high quality undervalued stocks that filters for fundamentals first so you are not just chasing headlines.
- Prioritize capital protection by working through the 30 resilient stocks with low risk scores that highlights businesses with steadier risk profiles you might otherwise overlook.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com