
Interparfums (IPAR) Shares Moved, What Is Drawing Attention Now?
Interparfums (IPAR) has drawn fresh attention after recent trading left the shares with a one year total return of 32.7% and a year to date gain of 37.0%.
The recent move to a US$117.09 share price comes after a strong year to date share price return of 37.0% and a 1 year total shareholder return of 32.7%. This is occurring even though momentum has cooled slightly over the past quarter as investors reassess Interparfums in light of its current valuation and growth profile.
Scan beyond Interparfums to spot other consumer-focused stocks with fresh momentum and solid financials using the curated list of solid balance sheet and fundamentals (23 results)
Interparfums has already rewarded holders with strong recent gains, yet the shares still trade below some valuation estimates. Has the meaningful upside already been captured, or is the market only partway through repricing this fragrance group?
Most Popular Narrative: 8% Undervalued
Interparfums is trading at $117.09 against a widely followed fair value estimate of $126.67, so the narrative implies some remaining upside driven by how the business is reshaping its brand portfolio and launch calendar.
The decision to make 2026 an off cycle year focused on line extensions, while preparing a concentrated wave of new blockbuster pillars for brands already above US$100m of sales in 2027 and further launches in 2028, supported by higher advertising and promotion spending that reached 18.8% of sales in the first half of 2026 and is guided toward about 21% for the full year, sets up a product cycle that can support higher revenue, operating margin and earnings power.
See why 8 investors see Interparfums as 8% undervalued.
Result: Fair Value of $126.67 (UNDERVALUED)
Still, the Interparfums story can change quickly if higher SG&A and advertising costs fail to lift sales, or if any major fragrance license underperforms.
Find out about the key risks to this Interparfums narrative.
Another View: Interparfums Through The P/E Lens
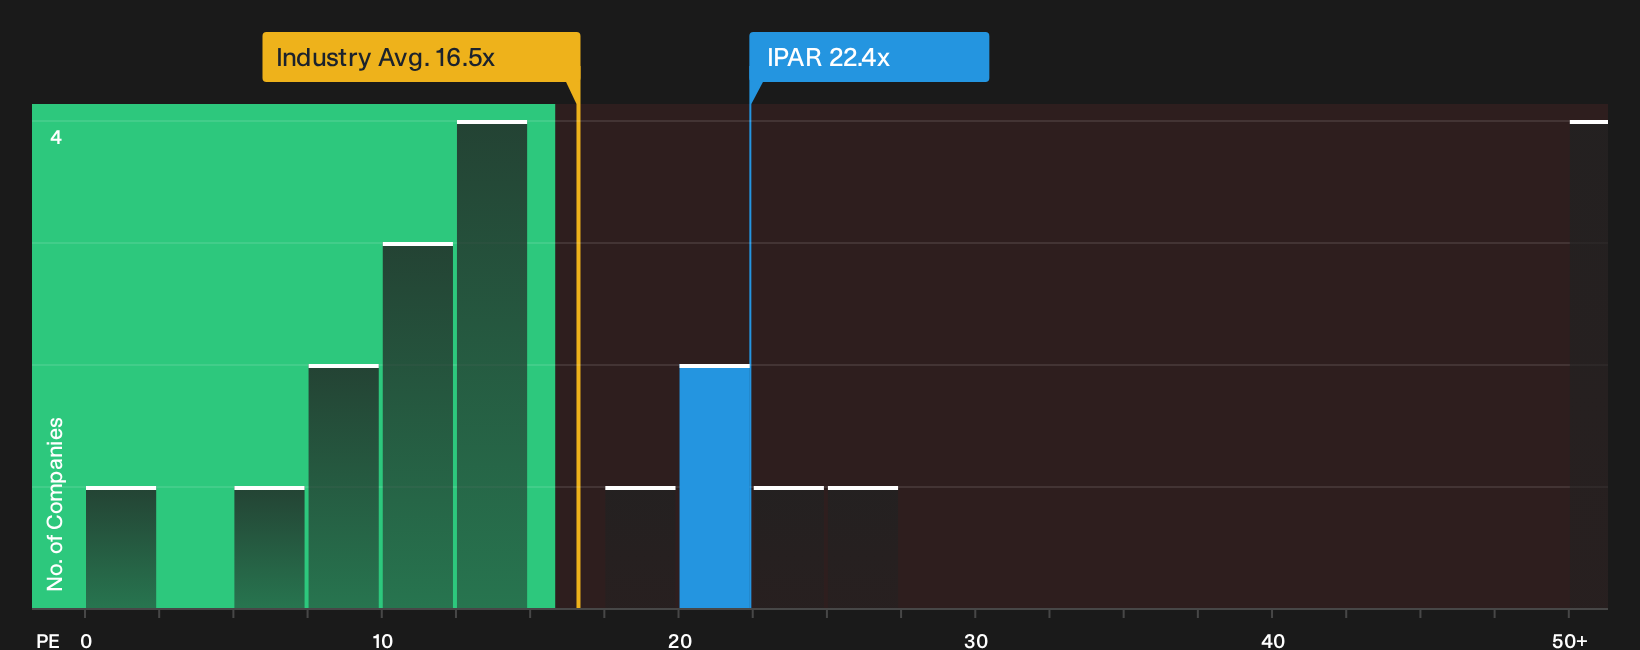
The DCF narrative paints Interparfums as undervalued, yet the P/E picture is less forgiving. IPAR trades at 22.4x earnings, above the global Personal Products industry on 16.5x, and above a fair ratio of 15.6x that the market could move toward. That gap points to valuation risk rather than a clear margin of safety. Which signal do you put more weight on?
For a closer look at how this price stacks up against earnings and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Interparfums valuation and risk profile can cut both ways, so assess the full data set quickly and weigh the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Interparfums?
If Interparfums has you thinking more broadly about opportunities, do not stop here. Fresh ideas often come from scanning outside your usual watchlist.
- Spot potential mispricings early and sift through 35 high quality undervalued stocks that combine quality fundamentals with more modest valuations.
- Prioritise resilience in choppy conditions by checking 30 resilient stocks with low risk scores that score well on stability and financial strength.
- Get ahead of the crowd by scanning 19 high quality undiscovered gems that pair solid numbers with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com