
Alkermes (ALKS) Stock Could Look Pricey After New Depression Trial
Alkermes has logged a strong multi‑year share price run, and with earnings in focus, the question now is how well that recent performance lines up with what the business is actually earning. Recent trial headlines around its neuroscience pipeline keep attention on the story, but the valuation rests on the numbers behind it.
- Over the past 5 years the stock has returned 87.0%. That puts real pressure on the current earnings base to carry that kind of share price progress.
- The new Phase 2 work on ALKS 7290 in major depressive disorder and adult ADHD can influence how investors think about future profit potential, the timing of cash flows and the earnings power that might eventually need to support today's valuation.
- Your read on Alkermes is one view; the desks covering it have another. See what analysts think Alkermes's shares could be worth.
The issue now is whether Alkermes' current share price around US$45.69 is adequately supported by its earnings profile or asks too much of future profit growth.
If you want to stress test this same earnings question beyond Alkermes, compare it with other 35 high quality undervalued stocks.
Does Alkermes Look Pricey on Earnings?
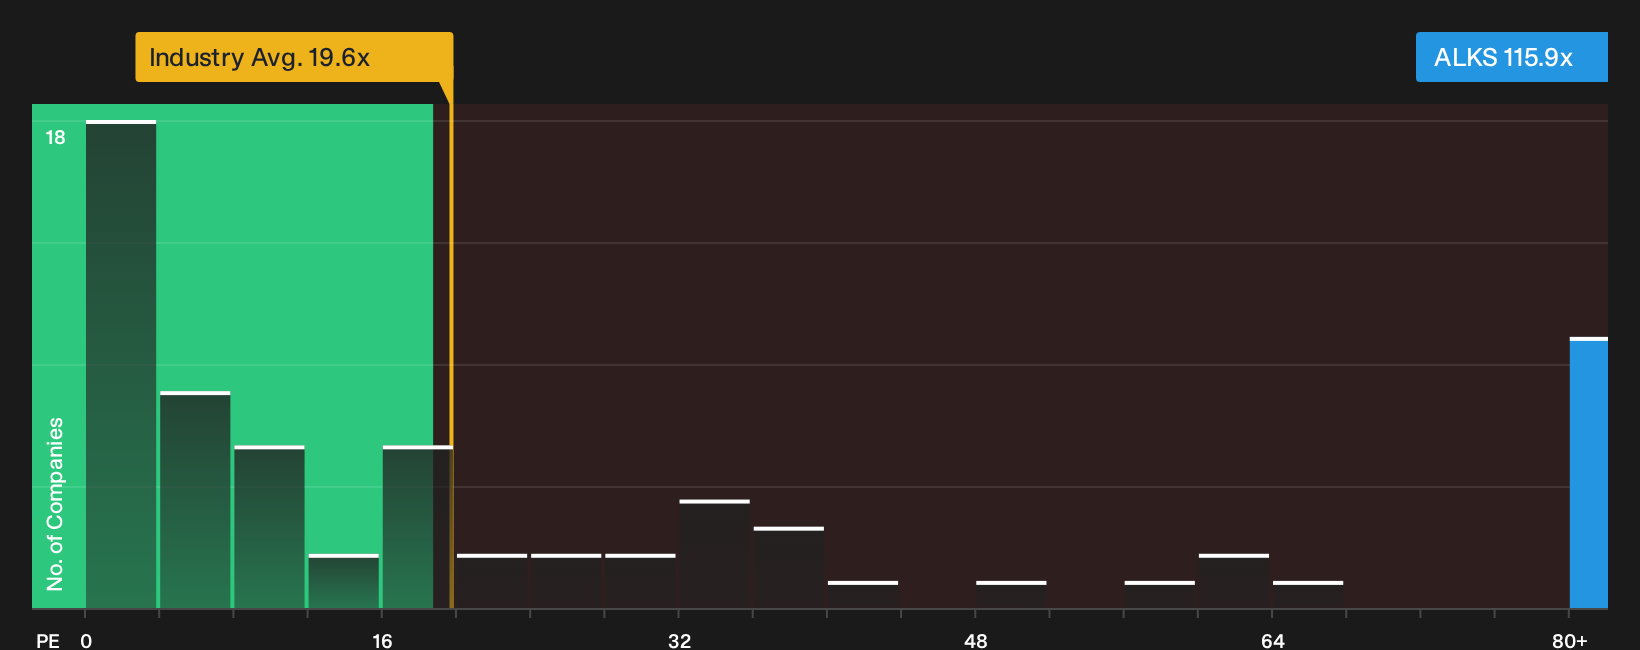
For Alkermes, the P/E ratio is the cleanest way to line up the share price with the earnings investors are paying for today. The stock trades on roughly 115.9x earnings, which is far above the broader Biotechs sector average of about 19.6x and also above the peer group at roughly 95.4x. That signals buyers are attaching a heavy premium to the current profit stream.
The Fair Ratio, which reflects what a tailored P/E could look like after factoring in Alkermes' growth profile, margins, size and risk, sits meaningfully below the present multiple. Because of that gap, the shares screen overvalued on this earnings lens, even after recent excitement around the ALKS 7290 trial work in depression and ADHD. For anyone weighing Alkermes at around US$45.69, the key question is whether the future cash flows and drug pipeline justify paying this kind of earnings premium today. Explore the numbers behind Alkermes's P/E valuation.
The Alkermes Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Alkermes valuation puzzle leaves off by spelling out what kind of future growth, margins and earnings power would need to show up for the stock to look materially richer or cheaper than it does today on the Community page. Each storyline links a fair value estimate to a clear set of potential catalysts and risks so you can track which version of Alkermes' future appears to be taking shape over time.
Community views on Alkermes are split between orexin powered upside and the drag from heavier spending and a guided loss in 2026.
Bull case: 19% undervalued
"Robust, above-expectation demand growth for Alkermes' proprietary neuroscience products VIVITROL, ARISTADA and LYBALVI, now reflected in Q2 2026 proprietary net sales of US$411.7 million..."
Discover why this Narrative puts Alkermes at 19% undervalued.
Bear case: 20% overvalued
"The bearish analysts are not forecasting that Alkermes will become profitable in next 3 years, with higher SG&A and R&D weighing on margins..."
Explore why this Narrative puts Alkermes at 20% overvalued.
One more Alkermes angle that could change the story
Alkermes' valuation only tells part of the story, because the people directing capital allocation, pipeline priorities and long term risk taking, and how they are rewarded for those choices can tilt investor outcomes in subtle but powerful ways. See who runs Alkermes and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com