
Coles Group (ASX:COL) Reports Q1 Sales Growth, Is The Pullback Signaling Value?
Coles Group (ASX:COL) just posted Q1 FY27 trading figures, with group sales revenue up 2.2% and supermarket sales up 3.6%. This update provides context for its first-half earnings outlook.
Coles Group shares have slipped in the short term, with the 7 day share price return down 10.34% and the 90 day move down 12.77%, while the 3 year total shareholder return of 52.51% indicates that longer term holders have still seen solid gains.
Scan how Coles Group compares with other retailers facing the same cost of living squeeze by reviewing our hand picked 3 high quality undervalued stocks across the market.
Coles Group appears to be a resilient retailer based on recent figures, yet the share price has pulled back significantly. Is the gap between operations and sentiment offering fair value or signaling a potential trap at today’s levels?
Most Popular Narrative: 5% Undervalued
Coles Group closed at A$21.25 against a narrative fair value of A$22.43, pointing to a modest discount that hinges on execution of its productivity and automation programs.
The Simplify and Save to Invest program has reached A$876m of benefits since FY24 and around A$1.9b of productivity savings since FY20, with guidance to exceed A$1b of SSI benefits by the end of FY27. Ongoing delivery from this cost program can remain an important driver of net margin and EBIT.
See why 65 investors see Coles Group as 5% undervalued.
Using a 7.35% discount rate, the most followed narrative points to fair value at A$22.43, only slightly above the current share price and broadly aligned with the A$22.19 analyst target, so the implied upside is measured rather than dramatic.
The same narrative leans on steady revenue growth assumptions of about 3.5% a year and forecast earnings growth of 8.1% per year, backed by high past and projected returns on equity of 27.6% today and 32.4% in three years, which together help support the discounted cash flow estimates.
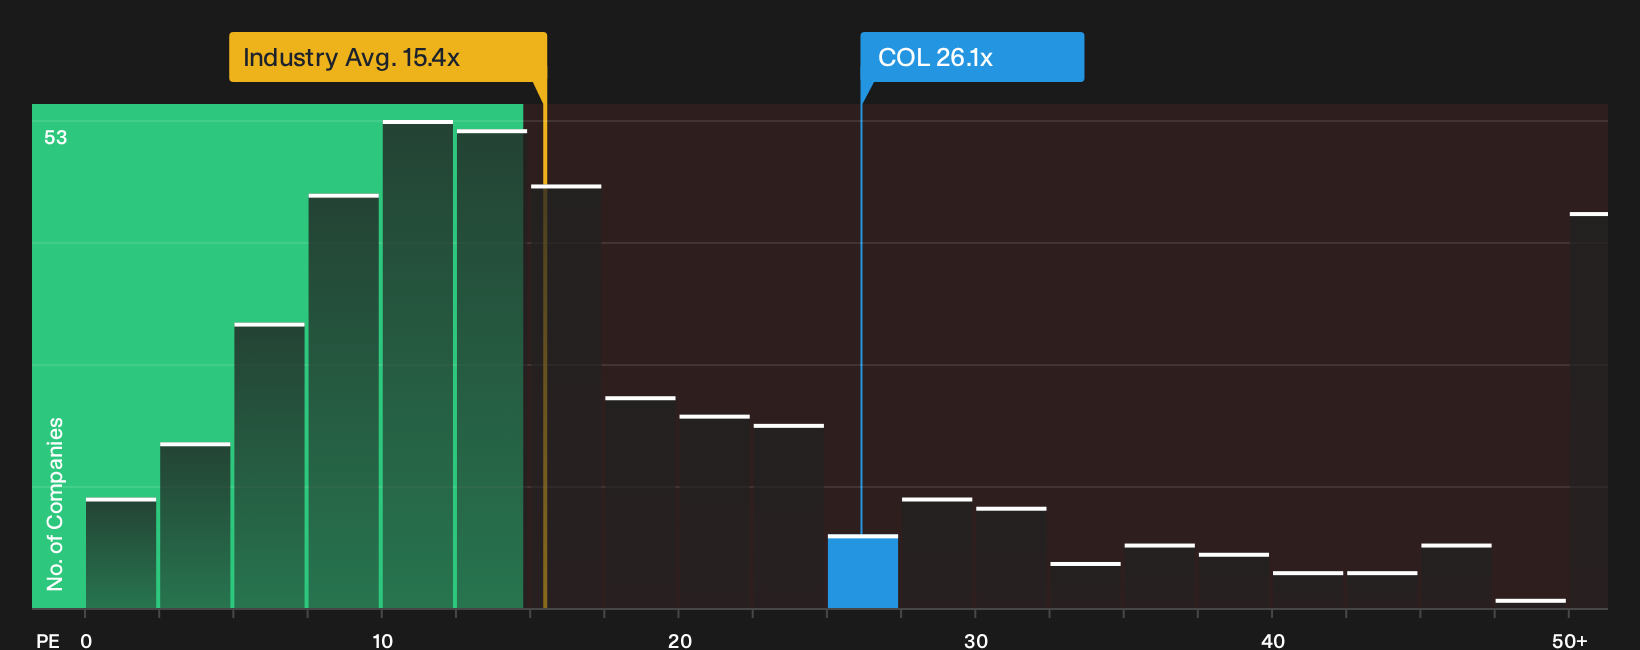
Against that backdrop, Coles Group screens as good value on the SWS DCF model, trading about 14.5% below the internal fair value estimate of A$24.87, although its value score of 2 out of 6 and a P/E of 26.1x that is higher than the global consumer retailing average of 15.4x highlight that expectations for future cash generation are already quite demanding.
Result: Fair Value of A$22.43 (UNDERVALUED)
Still, the Coles Group story can change quickly if tighter supermarket regulation reduces pricing power or if weakness in its Liquor division continues to drag on group earnings.
Find out about the key risks to this Coles Group narrative.
Another View: Coles Group Through The P/E Lens
Coles Group looks inexpensive on the SWS DCF model, yet its 26.1x P/E tells a different story. That multiple sits above both the estimated fair ratio of 25.8x and the global consumer retailing average of 15.4x. So is this a quality premium, or just limited valuation headroom if sentiment weakens?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed views on whether Coles Group is fairly priced or slightly undervalued, investors should not rely solely on headline narratives. Instead, weigh the potential upside and downside by examining the detailed breakdown of 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Coles Group?
If Coles Group has sharpened your focus on quality and price, broaden your watchlist now using targeted screeners built to surface differentiated opportunities.
- Target resilient value by reviewing a curated set of 3 high quality undervalued stocks that combine reasonable pricing with strong underlying fundamentals.
- Strengthen potential income streams by scanning a hand picked pool of 5 dividend fortresses that aim to pair higher yields with balance sheet support.
- Prioritise capital protection by filtering for 6 resilient stocks with low risk scores so you are not leaving lower volatility options on the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com