
Everus Construction Group (ECG) Jumped, What Is Driving Attention Now?
Everus Construction Group (ECG) drew fresh attention on November 3 after posting third quarter results that showed higher sales, stronger net income, and increased earnings per share compared with the same period last year.
The sharp 9.46% 1-day share price return to US$112.73 after the earnings release suggests investors reacted strongly to Everus Construction Group’s latest numbers, even though the 30-day share price return is down 8.61% and the 90-day share price return is down 19.91%.
Over a longer stretch, the year-to-date share price return of 26.41% and 1-year total shareholder return of 30.13% indicate that short-term volatility has emerged after a solid overall run, with the latest move suggesting that confidence in the earnings story may be rebuilding.
Scan contracting peers reacting to earnings surprises like Everus Construction Group and see which ones screen strongest on fundamentals with the list of solid balance sheet and fundamentals (23 results).
Everus Construction Group just delivered strong headline results while still trading at a sizeable discount to analyst targets. Is the market prudently sceptical after the pullback, or is it mispricing the latest step up in performance?
Most Popular Narrative: 37% Undervalued
On the most followed narrative, Everus Construction Group screens as materially undervalued, with a fair value estimate of $177.60 compared with the latest close at $112.73. That gap is being tied directly to how investors are pricing its project pipeline and margins.
Escalating power infrastructure needs tied to data centers, electric vehicles, industrial reshoring and undergrounding are supporting sustained T&D backlog growth and higher revenue visibility, reinforcing multi year revenue expansion.
Ongoing energy transition investments and utility commitments to grid hardening and substation upgrades are expanding Everus addressable market in renewables and T&D, contributing to an improving project pipeline and more resilient earnings across cycles.
See why 4 investors see Everus Construction Group as 37% undervalued.
Result: Fair Value of $177.60 (UNDERVALUED)
Still, the Everus Construction Group story depends heavily on data center demand and smooth M&A execution, and setbacks on either front could quickly challenge this undervalued narrative.
Find out about the key risks to this Everus Construction Group narrative.
Another Take On Everus Construction Group’s Value
The popular story has Everus Construction Group trading well below a US$177.60 fair value. Our DCF model points in the opposite direction. On this view, ECG at US$112.73 sits above an estimated future cash flow value of US$82.71, which frames the stock as expensive rather than cheap.
This gap between earnings based targets and the SWS DCF model raises a simple question for investors: Are cash flow assumptions too harsh, or are profit based expectations running ahead of what the balance of inflows can reasonably support over time?
Look into how the SWS DCF model arrives at its fair value.
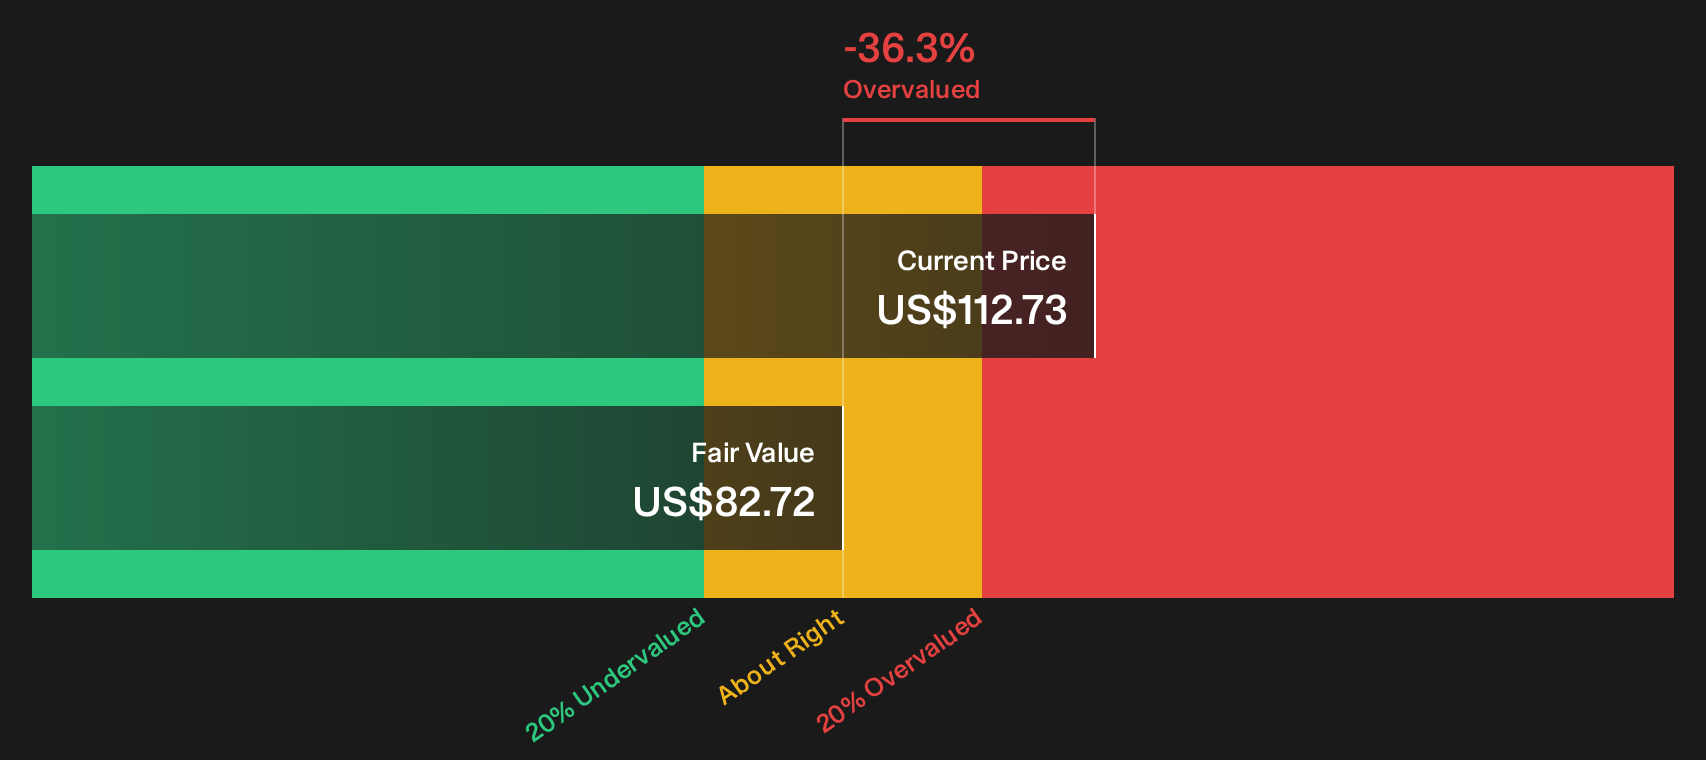
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Everus Construction Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Everus Construction Group after these results. Act while the data is fresh and pressure test both sides of the story with the 5 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Everus Construction Group?
Do not stop with Everus Construction Group. Use fresh data, clear filters, and a few targeted screens to spot opportunities that match how you actually invest.
- Target potential mispricings by scanning companies that combine quality fundamentals with low valuations through the 35 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses that score well on financial strength with the 30 resilient stocks with low risk scores.
- Hunt for less crowded opportunities by filtering for strong fundamentals in smaller, quieter stories using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com