
Is Henry Schein (HSIC) Still Reasonable After Raised Guidance?
Henry Schein has delivered a 30.1% gain over the past three years, and the share price recently closed at US$82.50. With earnings in focus after fresh profit news, the open question is whether that price still lines up with what the business is actually earning.
- A 30.1% return over three years puts real weight on the question of whether Henry Schein's current valuation is being carried by its earnings power.
- Recent profit strength, supported by higher sales in key categories and management's confidence in future earnings, can shape how much investors are prepared to pay for each dollar of Henry Schein's income.
- Your read on Henry Schein is one view; the desks covering it have another. See what analysts think Henry Schein's shares could be worth.
The issue now is whether Henry Schein's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to pressure test Henry Schein's earnings-based valuation against a wider set of opportunities, compare it with 35 high quality undervalued stocks.
Is Henry Schein Still Cheap on Earnings?
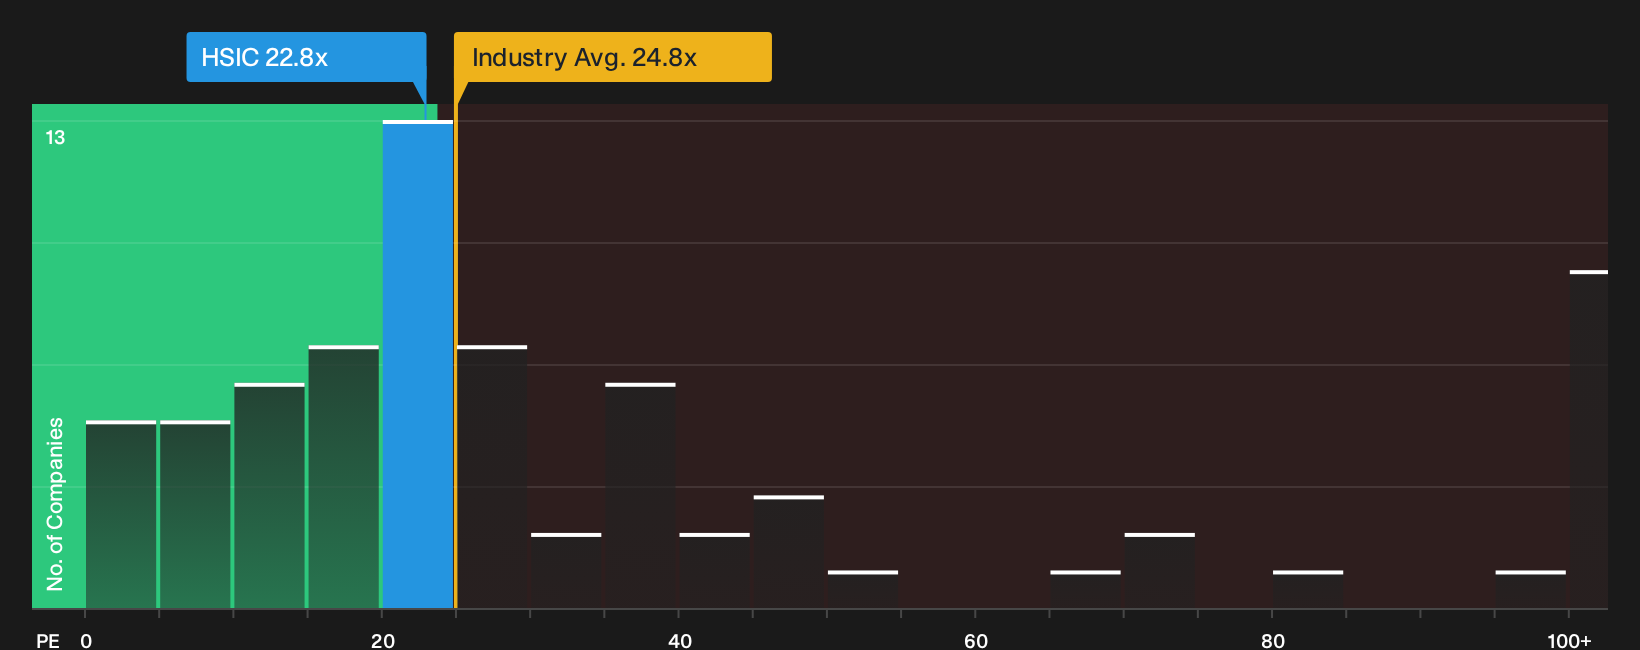
The P/E ratio works well for Henry Schein because its profit profile is central to how the market weighs the business. At a current P/E of 22.8x, the shares trade below the broader Healthcare sector average of about 24.8x and also under the peer group average of roughly 29.7x. That places the stock on a lower earnings tag than many comparable distributors and healthcare suppliers that investors can choose from.
The Fair Ratio model, which blends factors like growth prospects, profitability, size and risk, points to a higher P/E than where the stock trades today, so the current 22.8x screens as undervalued on this framework. Because management has recently raised full year earnings guidance following Henry Schein's Q3 2026 report, the gap between the market multiple and this tailored yardstick is particularly worth paying attention to if you are weighing whether the current price already reflects that outlook. Explore the numbers behind Henry Schein's P/E valuation.
The Henry Schein Narrative: What Would Justify Today's Price?
Henry Schein Narratives pick up where this valuation question leaves off by spelling out what kind of future for growth, margins and earnings would need to play out for the share price to sit meaningfully above or below today’s level. Each narrative treats Henry Schein's fair value as a thesis you can revisit over time rather than a single snapshot, and they sit on Simply Wall St's Community page for anyone who wants to track how those ideas hold up against fresh results.
Community views on Henry Schein are split between a margin driven upside story and a cautious read on execution and pricing risk.
Bull case: 16% undervalued
"Henry Schein is actively pursuing operational efficiencies, including at least US$200 million of operating income improvement targeted over the next few years..."
Discover why this Narrative puts Henry Schein at 16% undervalued.
Bear case: 11% overvalued
"The value creation program targets more than $200 million in operating income improvements and includes large scale outsourcing and shared services..."
Explore why this Narrative puts Henry Schein at 11% overvalued.
Henry Schein’s valuation still leaves one big piece of the picture off the table
Price multiples and fair value models only tell you where Henry Schein stands today. The missing piece is where professional analysts think this business could be a few years down the road. Explore where analysts expect Henry Schein to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com