
Circle Internet Group (CRCL) Freezes Hack Linked USDC, Is The Stock Fully Priced?
Circle Internet Group (CRCL) is back in focus after freezing more than US$800 million in USDC tied to the record US$6.3b Binance hack, sharpening investor attention on crypto counterparty and operational risk.
That rapid freeze response comes after a volatile stretch for Circle Internet Group, where an 18.87% 90 day share price return has been tempered by a year to date share price decline of 9.88% and a 1 year total shareholder return down 32.39%. This suggests recent momentum is rebuilding from a weaker longer term base.
Spot 21 cryptocurrency and blockchain stocks that pair Circle Internet Group style exposure to stablecoins and blockchain infrastructure with stronger recent share price momentum and distinct risk profiles across the crypto ecosystem.Bulls point to Circle Internet Group’s revenue and net income growth, along with a steep discount to analyst targets, while bears focus on drawdowns and hack risk. Which story does the current valuation lean toward next?
Most Popular Narrative: 30% Undervalued
At $75.22, Circle Internet Group trades well below the most followed fair value estimate of $106.98. This frames the current debate less around hype and more around whether its stablecoin rails and payments infrastructure can justify that gap.
Accelerating mainstream adoption of USDC for cross border and B2B payments via Circle Payments Network, with over 100x growth in trailing 30 day volumes and a pipeline of 500 institutions, should translate into sustained transaction driven revenue expansion and higher operating leverage.
See why 61 investors see Circle Internet Group as 30% undervalued.
Result: Fair Value of $106.98 (UNDERVALUED)
Still, the narrative can break if USDC reserve income weakens or if new stablecoin rules and rival platforms begin to chip away at the economics of Circle Internet Group.
Find out about the key risks to this Circle Internet Group narrative.
Another View: What The P/E Says About Circle Internet Group
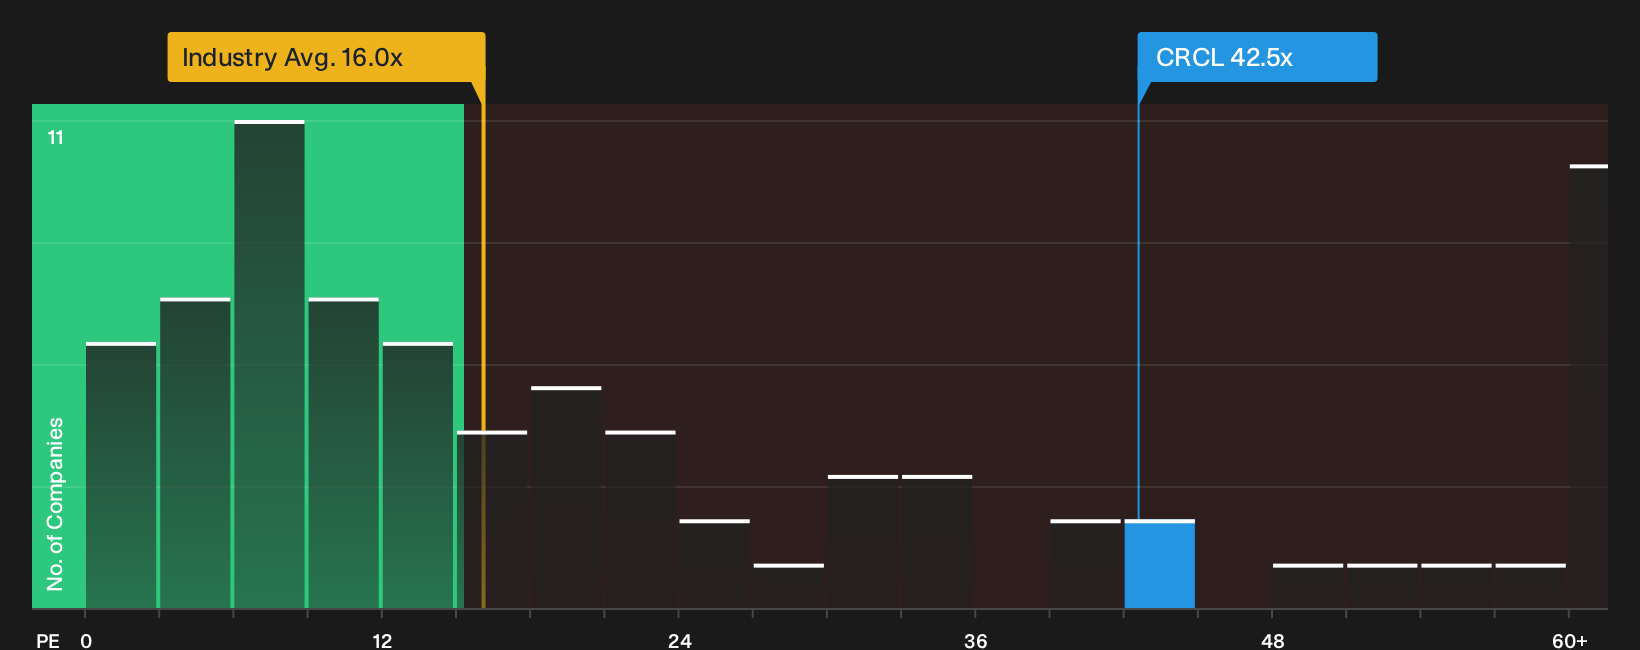
The story looks different when you move from analyst fair value estimates to the current P/E. Circle Internet Group trades at 42.5x earnings, while the US Diversified Financial industry sits closer to 16x and the fair ratio points to 19.3x. That gap suggests investors are already paying a steep premium. Is the USDC and Arc growth narrative strong enough in your view to support that kind of valuation stretch?
Before leaning on that premium, it is worth stress testing how much of it you think is justified by Circle Internet Group’s business model resilience and how much could unwind if sentiment cools, as set out in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of upside potential and hard to ignore risks around Circle Internet Group line up with your own instincts, or does it feel out of sync? Act while the information is fresh: review the key data points and weigh both the bullish and bearish arguments captured in the 2 key rewards and 3 important warning signs.
Looking for more Circle Internet Group style ideas?
If Circle Internet Group has sharpened your thinking, do not stop here. Use the screener to pressure test your thesis, spot patterns, and widen your opportunity set fast.
- Target companies that combine quality with a potential price gap by running your criteria through 35 high quality undervalued stocks for ideas that might sit off the obvious radar.
- Protect your downside by focusing on financial resilience and use the 30 resilient stocks with low risk scores to surface businesses with sturdier risk profiles.
- Hunt for fresher stories before the crowd and let the 19 high quality undiscovered gems highlight under-followed stocks with fundamentals that still stack up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com