
Hecla Mining (HL) Could Be 40% Undervalued After Fresh Earnings
Hecla Mining (HL) just reported its third quarter 2026 earnings, including US$394.82 million in sales and US$149.6 million in net income, giving investors updated profitability markers.
Hecla Mining's share price has come under pressure in recent months, with the stock down 23.2% over the past 30 days and 30% year to date. At the same time, the 1 year total shareholder return is 10.45% and the 5 year total shareholder return is 119.65%, which points to long term momentum that contrasts with the recent pullback around the latest earnings update.
Scan 10 top silver producer stocks to see how other silver producers stack up against Hecla Mining after this latest earnings update.After a sharp pullback and fresh earnings in hand, Hecla Mining now asks a simple question of you: Is it worth stepping in here, or does waiting for an even cheaper entry make more sense once you weigh the valuation?
Most Popular Narrative: 40% Undervalued
Hecla Mining last closed at $13.21 while the most followed narrative pegs fair value at about $22.08, which implies a sizeable valuation gap that investors now have to reconcile with slowing forecast revenue and thinner margins.
The company's disciplined production ramp-up at Keno Hill, targeting a sustainable throughput of 440 tonnes per day by 2028, alongside proven high-return economics even at conservative silver price levels, is described as setting the stage for steady long-term free cash flow and earnings growth as the mine achieves scale.
Enhanced operational efficiency through automation, advanced analytics, and mine planning improvements at Greens Creek and Lucky Friday is expected to lower all-in sustaining costs (AISC), which in turn is described as contributing to healthier net margins and stronger bottom-line performance as silver markets improve.
See why 67 investors see Hecla Mining as 40% undervalued.
Result: Fair Value of $22.08 (UNDERVALUED)
Still, heavier capital needs at Keno Hill and potential shareholder dilution from deleveraging plans could upset the Hecla Mining upside story that investors are weighing.
Find out about the key risks to this Hecla Mining narrative.
Another View On Hecla Mining’s Valuation
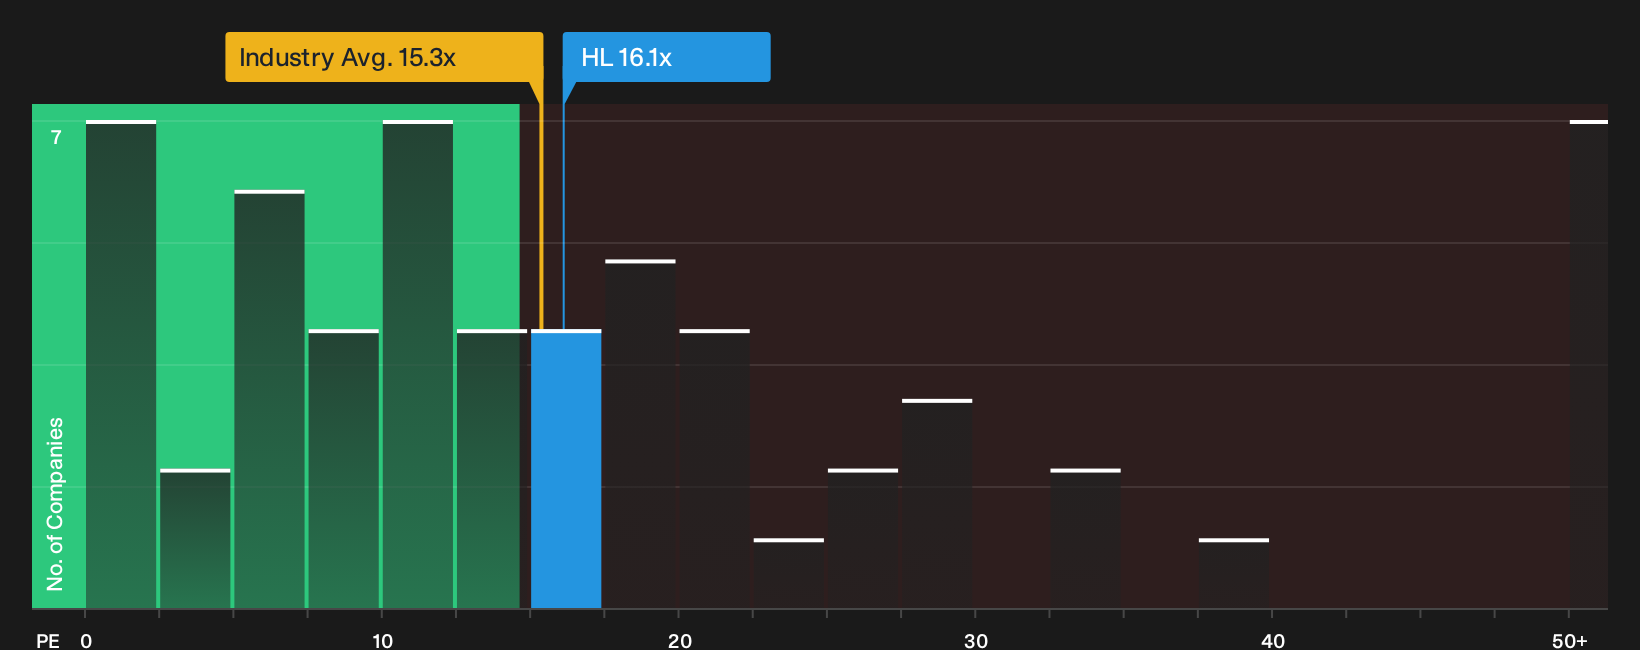
The first narrative leans on future earnings assumptions and a fair value of about $22.08. A different lens looks at what investors are paying for Hecla Mining today. On a P/E of 16.1x, the stock is described as more expensive than both its peer group at 14.3x and the wider US Metals and Mining sector at 15.3x.
That gap might be read as investors already paying a premium for Hecla’s profile, which could limit upside if the story does not keep improving, or prove reasonable if the business keeps justifying a higher tag. Which version of value do you trust more when deploying fresh capital into HL?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hecla Mining after these results. If you want to move quickly and still think independently, weigh both sides through the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hecla Mining?
If Hecla Mining has you thinking more broadly about your portfolio, use this moment to scan for other opportunities that fit your risk, income, and quality targets.
- Target fresh upside potential by reviewing the 19 high quality undiscovered gems that could complement or diversify away from your existing positions.
- Build a steadier core by focusing on companies in the list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when conditions get tougher.
- Strengthen your downside protection by filtering for the 30 resilient stocks with low risk scores that may suit a more cautious approach without giving up on return potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com