
Hulic (TSE:3003) Lifts Guidance And Dividend Outlook On Valuation Questions
Hulic (TSE:3003) is back in focus after management raised earnings guidance for 2026, projected record-high profit metrics, and lifted its dividend outlook, giving investors fresh numbers to reassess the real estate group.
That guidance upgrade has arrived while Hulic’s share price has been moving higher, with a 1-month share price return of 12.18% and a 7-day gain of 8.16%, and longer-term momentum reflected in a 1-year total shareholder return of 23.39% and a 5-year total shareholder return of 104.81%. This suggests investors have been reassessing both growth potential and income prospects around the stock.
Scan beyond Hulic and see how other real estate and income-focused plays are setting up in our hand-picked 30 dividend fortresses.
After this sharp rerating and a fresh set of record-profit targets from Hulic, the spread between the ¥1,883 share price and valuation estimates has widened. Where does fair value really sit in that range now?
Price-to-Earnings of 11.6x: Is it justified?
Hulic’s rerating now rests on a P/E of 11.6x at a ¥1,883 share price, which sits between broader Japan and sector valuation anchors.
The P/E ratio compares what investors are paying for each unit of current earnings. For a real estate operator like Hulic, which reports ¥123,180 of net income from ¥877,954 of revenue and has earnings forecast to grow 5.04% per year, this measure helps you weigh what the market is charging for its profit stream.
At a P/E of 11.6x, the stock trades below the wider JP market on 13.3x, yet above the JP Real Estate industry on 9.6x. That pattern suggests investors are assigning Hulic a premium to the sector while still paying a discount to the broader market. The fair P/E estimate of 16.2x is meaningfully higher than the current multiple, which indicates a level that market pricing could move toward if earnings quality and growth expectations remain in place.
Compared with peers, Hulic is described as good value versus the average 16.4x peer P/E, even as its own earnings growth has not outpaced the Real Estate industry and its Return on Equity of 12.7% is flagged as low. That mix of lower ROE, moderate growth, and a P/E sitting below both peer and fair ratios points to a market that is not aggressively pricing in upside despite the recent guidance and share price move.
Explore the SWS fair ratio for Hulic.
Result: Price-to-Earnings of 11.6x (UNDERVALUED)
Still, Hulic’s reliance on a single domestic market, along with its heavy exposure to office, hotel, and senior living assets, leaves the story sensitive to rental demand and tourism trends.
Find out about the key risks to this Hulic narrative.
Another view on Hulic’s value
The P/E picture shows Hulic on an 11.6x multiple that screens as good value against peers, yet the SWS DCF model lands in a very different place. On that approach, an estimated future cash flow value of ¥173.43 per share sits well below the ¥1,883 price, which points to an overvalued signal. Which lens should carry more weight in your own process?
Look into how the SWS DCF model arrives at its fair value.
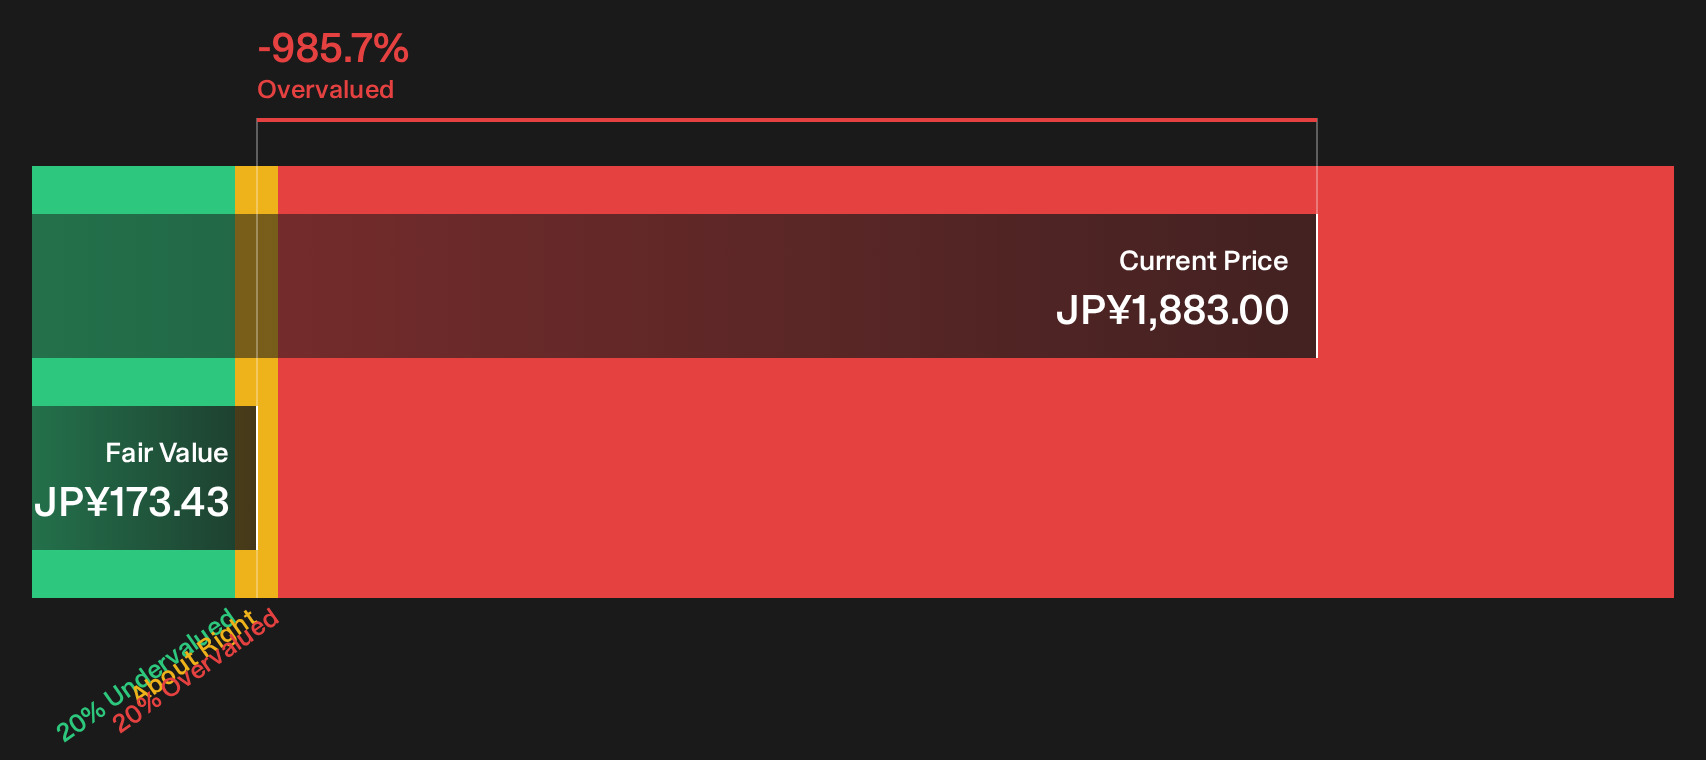
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hulic for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hulic’s valuation and guidance only matter if you dig into the details yourself and weigh both sides of the story quickly. To balance the upbeat targets with the areas investors are worried about, take a few minutes to review the 3 key rewards and 2 important warning signs.
Looking for more Hulic sized investment ideas?
If you stop at Hulic, you risk missing other opportunities that match your style. Widen the lens and put a few more candidates on your radar.
- Target resilience by reviewing companies in the 22 resilient stocks with low risk scores that aim to pair steadier fundamentals with more controlled risk profiles.
- Hunt for value by scanning the 18 high quality undervalued stocks and spot businesses where current pricing sits below what the underlying fundamentals suggest.
- Strengthen income potential by checking the 30 dividend fortresses and focus on stocks that combine higher yields with robust cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com