
Did Weaker Earnings Just Shift NCC's (OM:NCC B) Investment Narrative?
- NCC reported Q3 2026 results with sales of SEK 10,066 million, net income of SEK 444 million and mixed earnings per share trends versus last year.
- The construction group is pairing pressured nine month profitability with fresh project wins in Sweden and Norway that expand its long term order pipeline.
- We will now look at how NCC’s softer nine month profitability shapes the investment narrative that investors have been using up to now.
Compare how NCC’s latest orders and earnings stack up against peers by lining them up with list of solid balance sheet and fundamentals (195 results) in similar construction and infrastructure focused sectors.
NCC Investment Narrative Recap
NCC is a holding for investors who accept a contracting focused group with currently thin profitability and are watching whether order intake can offset softer earnings. Q3 highlighted that tension. Sales in the quarter were essentially flat at SEK 10,066 million, while net income of SEK 444 million and nine month figures pointed to pressured margins and lower profit versus last year.
The key near term swing factor remains execution on the asset light shift and the divestment of NCC Industry, together with keeping dispute costs and zero margin projects in check. The main risk is that persistent legal costs, weaker Property Development contributions and lower nine month earnings relative to the prior year keep returns subdued.
The fresh contract for the Framnäsbadet swim center in Lidköping, with an order value of about SEK 680 million, is one of the more relevant recent announcements against this earnings backdrop. It feeds directly into NCC Building Sweden and ties into the earlier point about the backlog growing through public and social infrastructure projects.
For you as an investor, this kind of multi year, turnkey partnering contract helps show how NCC is trying to support future revenue while dispute costs and muted Property Development EBIT remain a drag. Execution risk does not disappear. Cost control over a project running through 2029 and disciplined pricing will matter for whether this backlog translates into healthier margins or just more low return volume.
NCC's current analyst narrative points to revenues of SEK 44.0b and earnings of SEK 1.6b by 2029, based on an assumed yearly revenue decline of 6.6% and an earnings increase of about SEK 1.5b from SEK 78.0m today.
Uncover how NCC's fair value indicates an 8% potential upside to its current price that may not last much longer.
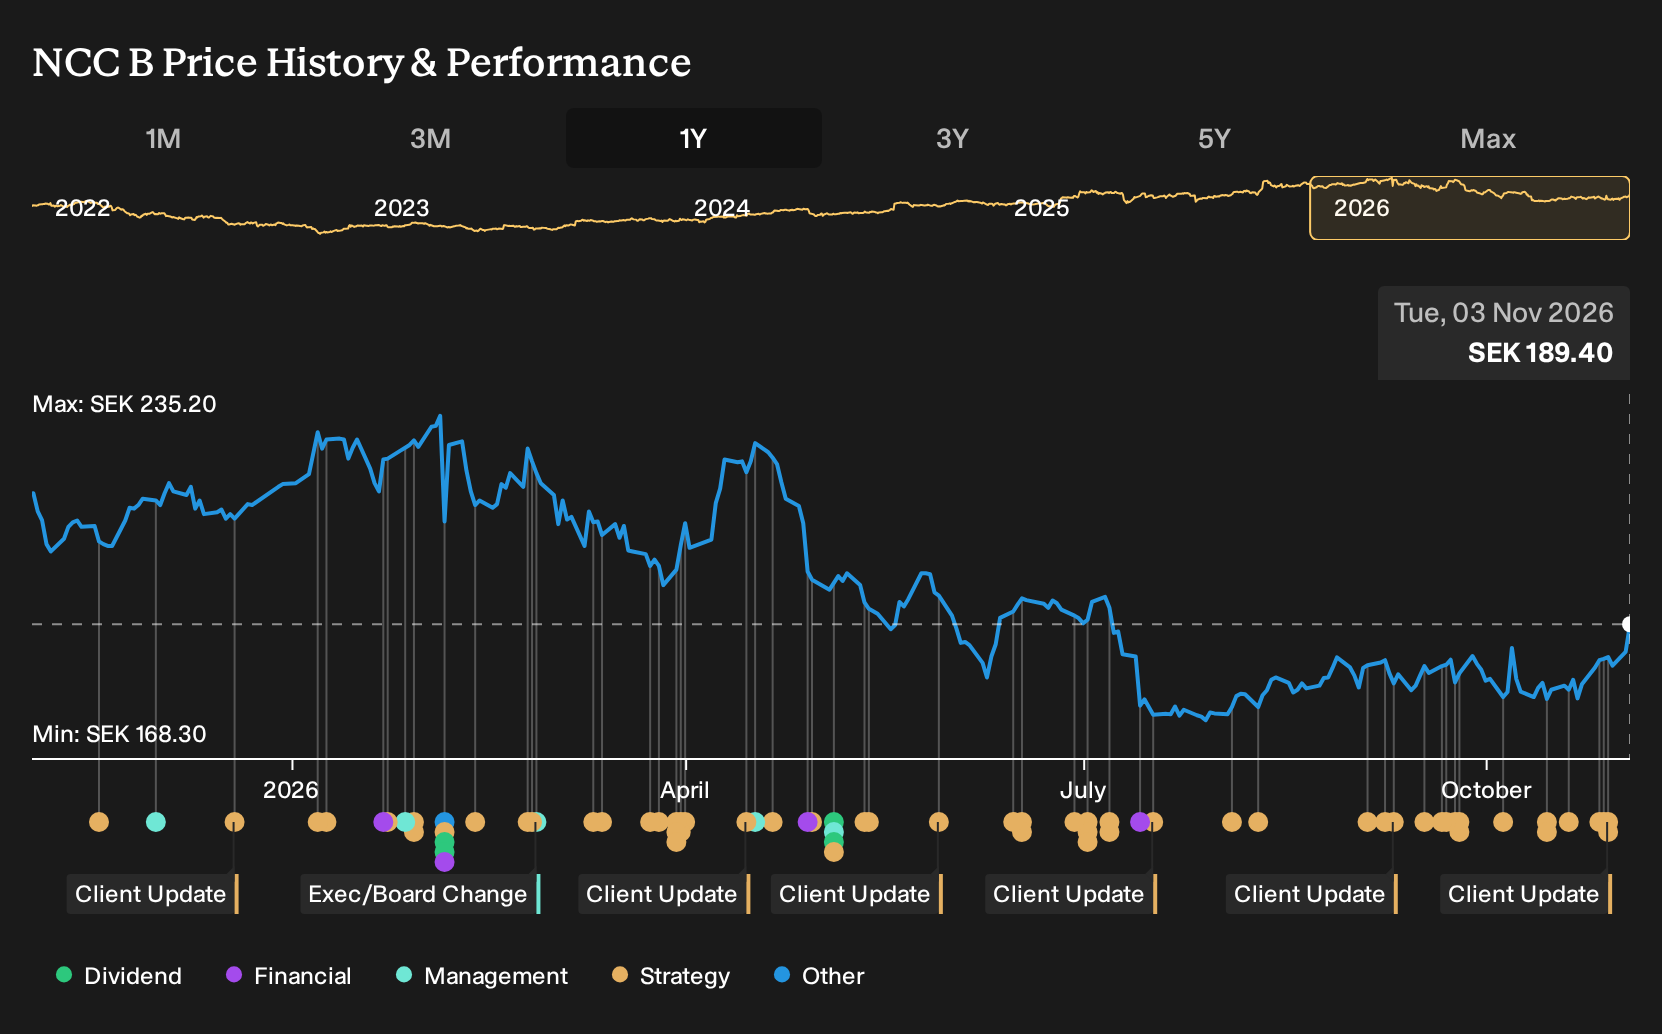
Exploring Other Perspectives
Some of the most optimistic NCC analysts put more weight on the growing order backlog as a catalyst, expecting revenue of about SEK 46.5b and earnings around SEK 1.5b by 2029. Those forecasts were set before this Q3 report and the latest prison and cultural center contracts, so you may see analyst views shift as the new data sinks in.
Explore 2 other NCC fair value estimates, including one that indicates there could be as much as 8% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NCC research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for NCC. This report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCC's overall financial health at a glance.
Looking For More NCC Investment Ideas Beyond This Stock?
If you want to stress test your thinking on NCC and broaden your watchlist at the same time, the Simply Wall St Screener can help you line up similar opportunities by balance sheet strength, income potential, or quality at a reasonable price.
- For investors who care most about financial resilience and low leverage, start with a list of solid balance sheet and fundamentals (195 results) to help you focus on sturdier businesses first.
- If you are hunting for quality companies that the market may be overlooking, shortlist ideas through 605 high quality undiscovered gems that match your return and risk preferences.
- Income focused investors can zero in on potential cash generators by scanning for 221 dividend fortresses that may fit a yield oriented approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com