
Do October Metrics Change The Bull Case For Interactive Brokers (IBKR)?
- Interactive Brokers Group recently reported October 2026 electronic brokerage metrics and detailed execution statistics for IBKR PRO clients, alongside the rollout of IBKR Autonomous Trading that lets eligible users authorize connected AI platforms to trade within a ring fenced AI Partition.
- The pairing of granular monthly performance disclosure with an AI driven trading capability highlights Interactive Brokers Group’s emphasis on transparency, automation and operational scale for active traders worldwide.
- We will look at how Interactive Brokers Group’s investment narrative is affected by IBKR Autonomous Trading’s push toward automated, instruction based execution.
Scan how IBKR Autonomous Trading fits into a broader shift toward AI driven execution by comparing it with 40 profitable AI stocks that aren't just burning cash that pair real earnings with automation tailwinds.
Interactive Brokers Group Investment Narrative Recap
To own Interactive Brokers Group, you need to believe the brokerage can keep adding active users, keep them trading and keep monetising client cash and margin balances efficiently. The short term swing factor is still trading volume and client activity. The latest October metrics and execution stats give you more real time evidence on how that activity is holding up, which helps frame that catalyst.
The biggest near term risk is that pricing pressure, aggressive rivals or lower benchmark rates squeeze both commissions and interest income at the same time, against already high expectations. IBKR Autonomous Trading does not change that core risk, although it could gradually shift more flow onto IBKR if adoption is broad.
Among the recent developments, IBKR Autonomous Trading is the clearest operational catalyst linked to this news. It moves Interactive Brokers Group further along the path from tools that help clients generate ideas to infrastructure that can execute instructions automatically within a dedicated AI Partition across more than 75,000 instruments.
For you as a potential shareholder, the key questions are practical. Does this capability lead to more orders per client, deeper use of IBKR’s global product set and stickier relationships, without creating outsized operational or compliance risk as it scales across countries and entities? That balance between higher engagement and tighter safeguards will shape how powerful a driver this feature becomes.
Interactive Brokers Group's current narrative points to forecast revenues of US$10.7b and projected earnings of US$1.8b by 2029, based on analyst estimates. That profile assumes yearly revenue growth of 16.0% and an earnings increase of about US$700m from the current US$1.1b level to the 2029 consensus figure.
Uncover why Interactive Brokers Group's fair value indicates a 37% potential upside to its current price that may not last much longer.
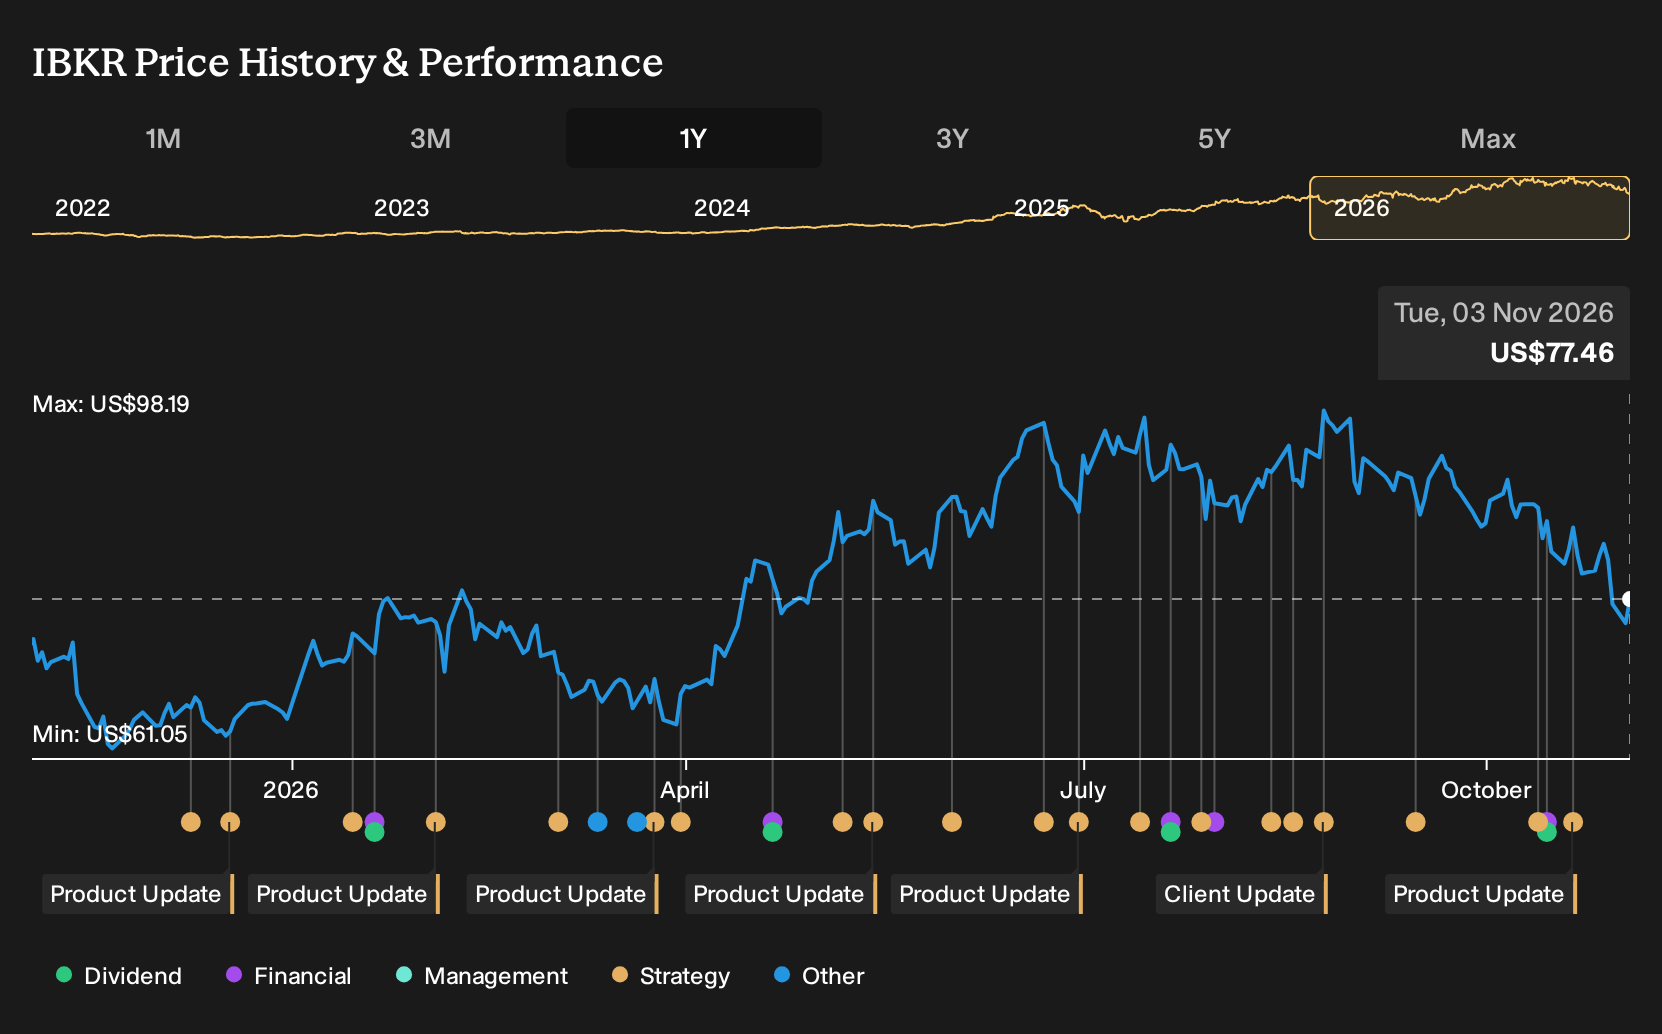
Exploring Other Perspectives
Some of the most optimistic analysts already assumed Interactive Brokers Group could reach about US$12.0b of revenue and US$2.1b of earnings by 2029, helped by very high pretax margins and AI enabled efficiency. You can now compare those upbeat assumptions with IBKR Autonomous Trading and decide whether this product nudges your narrative closer to theirs or not.
Explore 6 other Interactive Brokers Group fair value estimates, including one that suggests as much as 44% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Interactive Brokers Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interactive Brokers Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interactive Brokers Group's overall financial health at a glance.
Looking for more investment ideas beyond Interactive Brokers Group?
Once you have a view on Interactive Brokers Group, it can help to line it up against other opportunities that fit clear criteria around quality, value and resilience. The Simply Wall St Screener lets you filter the market quickly so you can spend more time weighing the businesses that actually match your approach.
- If you want income strength to be front and center, scan for companies with robust yields and payout records through 4 dividend fortresses.
- For investors who prefer steadier, lower risk profiles, narrow your watchlist to stocks with resilient balance sheets and business fundamentals via the 30 resilient stocks with low risk scores.
- If you are hunting for underfollowed opportunities with solid fundamentals, start with a curated 19 high quality undiscovered gems that may not yet be widely owned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com