
UK Stock Market Today: FTSE 100 Futures Edge Higher On Strong Factory Rebound Hope
The Morning Bull - UK Market Morning Update Wednesday, 4 Nov 2026
UK equities are set for a firmer open, with sentiment anchored by a surprisingly strong UK Manufacturing PMI print. The mood is cautiously upbeat, supported by a clearer signal that domestic industry is expanding again.
The UK Manufacturing PMI came in at 52.8 for October 2026, the highest in more than two years, indicating growth in new orders and activity. At the same time, input cost inflation accelerated and supplier lead times lengthened, highlighting persistent price pressures.
Stronger factory output, together with rising input costs, keeps the debate on future borrowing costs active. If producers pass higher expenses through to customers, that can squeeze households and influence how investors assess earnings resilience for more domestically focused companies.
An open question is how the Bank of England will balance firmer manufacturing data against lingering inflation risks at its 5 November meeting. That decision on rates and guidance could either support today’s cautiously positive tone or lead to a rapid reassessment.
Stocks to Watch Before the Opening Bell
Shell (SHEL)
Shell is in focus after agreeing to sell its 16.67% non operated interest in the North West Shelf LNG project to Abu Dhabi backed XRG for about US$1.45b. The exit from the long running Australian venture aligns with Shell’s focus on what it calls advantaged integrated gas positions. Investors can watch for how capital from this sale is redeployed.
Shell is also involved in exploration work in Queensland’s Taroom Trough, where early drilling results include gas and 300 barrels a day of light oil entering the domestic market. Together with ongoing moves in US crude inventories, this keeps attention on how Shell’s global gas and oil portfolio is being reshaped.
Babcock International Group (BAB)
Babcock International Group has picked the KierBAM joint venture to deliver a £600m upgrade at the 10 Dock facility in Devonport. The programme is aimed at improving maintenance capacity for current and future Royal Navy submarine fleets and is being run through Babcock’s Major Nuclear Capital Programmes unit.
The Devonport work forms part of longer term spending on UK naval infrastructure. Readers following Babcock International Group can focus on execution risk, cash flow timing from such large projects, and any feedback on margins as the upgrade progresses.
Marks and Spencer Group (MKS)
Marks and Spencer Group is pushing harder into international food retail, with plans to open five Foodhalls in the UAE over the next 12 months. The first site, at Dubai Festival City, is set to be a 15,327 sq ft Foodhall and the largest M&S food outlet outside the UK.
The retailer intends to cut prices on more than half of Foodhall items in the UAE and broaden the range to support a full weekly shop. Marks and Spencer Group watchers can pay attention to how this pricing shift affects volumes and profitability in the region.
Top Movers
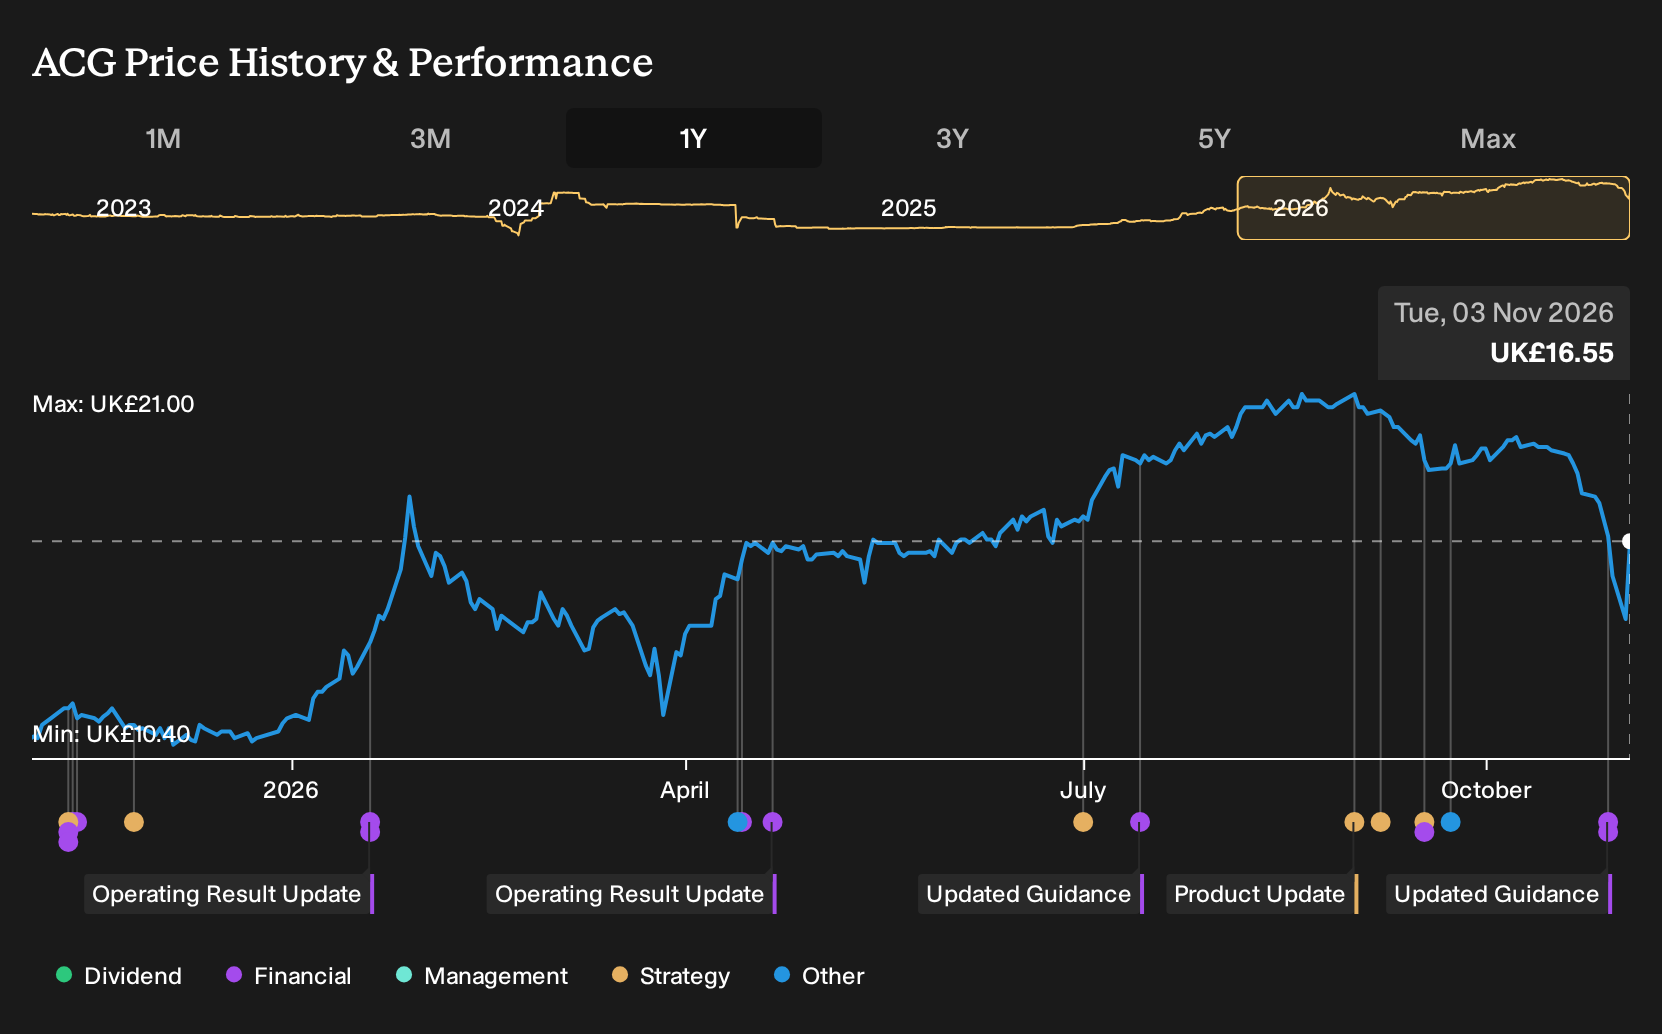
- ACG Metals (LSE:ACG) jumped 16.55% after agreeing an all share US$220m acquisition of Blue Moon Norway.
- International Workplace Group (LSE:IWG) advanced 8.57% following Q3 results that showed higher revenue and tighter adjusted EBITDA guidance above consensus.
- Drax Group (LSE:DRX) gained 6.61% after announcing a potential £20b AI data centre partnership at its Yorkshire power station.
Top Losers
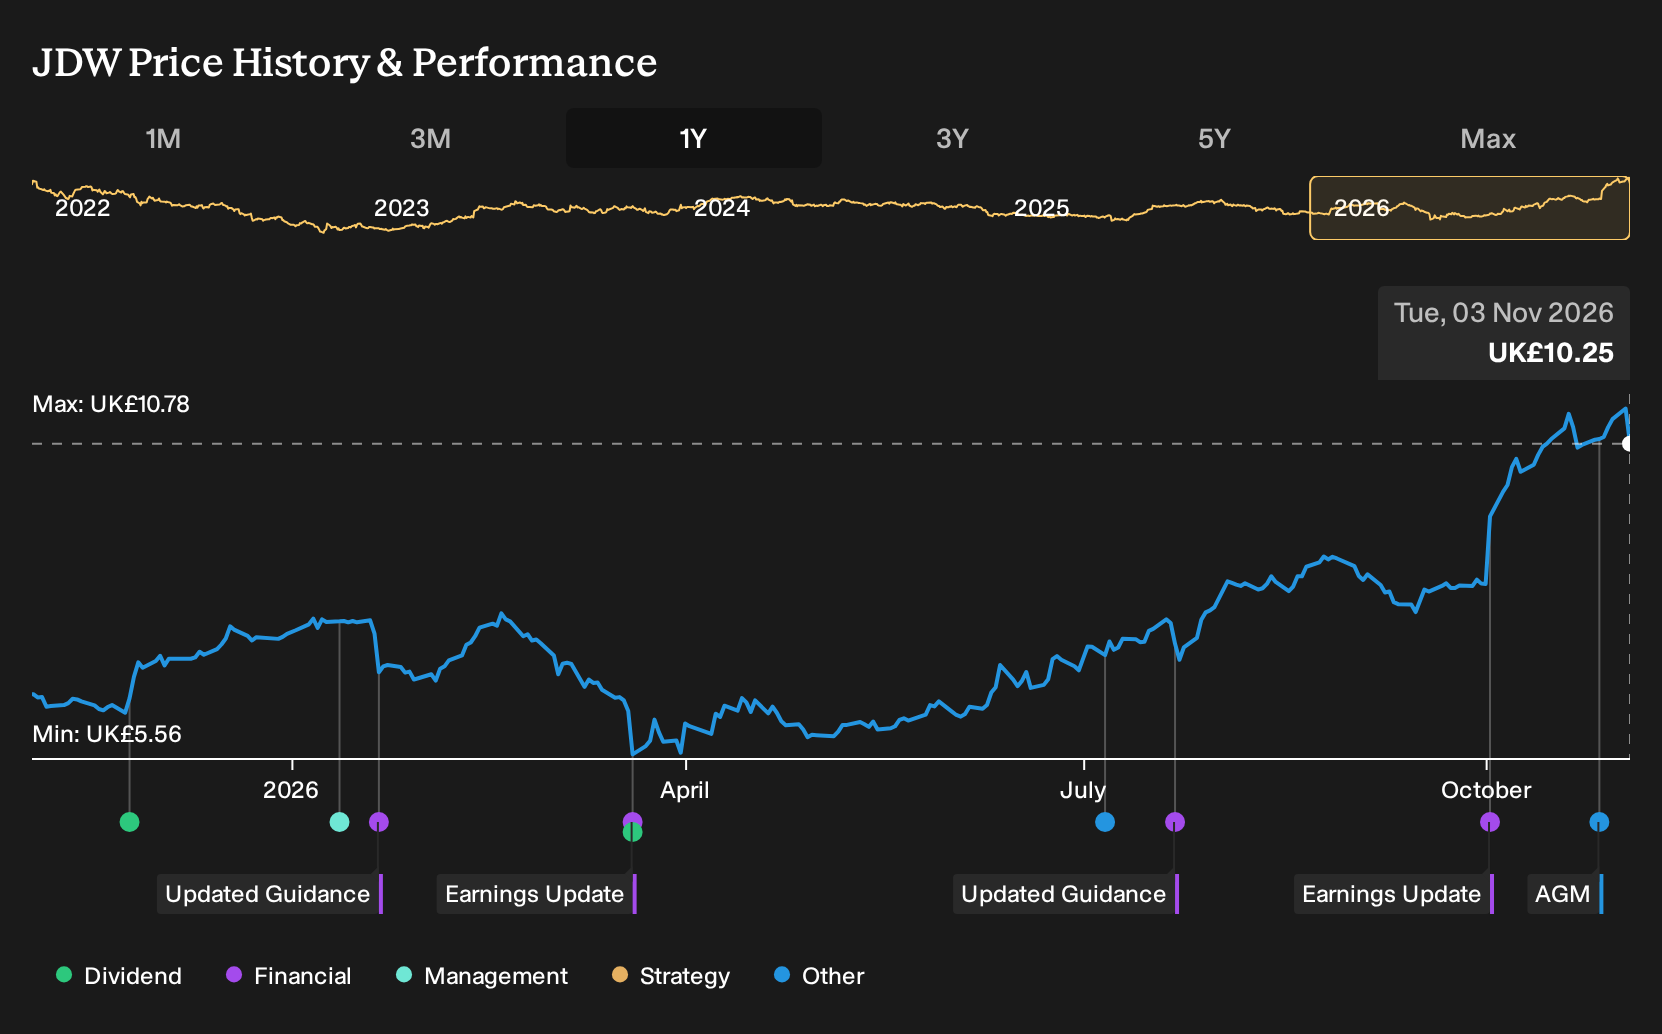
- J D Wetherspoon (LSE:JDW) fell 4.92% as the pub operator traded lower during a broad UK market pullback.
- Barratt Redrow (LSE:BTRW) declined 4.66% after Citi cut its target price and flagged slower margin recovery.
- Young's Brewery (LSE:YNGA) fell 4.16%.
On The Radar
The next few sessions are dominated by the Bank of England decision and a packed slate of FTSE earnings that sit alongside US jobs data and euro area inflation prints.
- BoE Interest Rate Decision and Monetary Policy Report, Thu 5 Nov. Markets currently look for Bank Rate to move from 3.75% toward 4%, so anything softer or firmer on the path of rates feeds directly into UK borrowing costs, housebuilders and the pound.
- S&P Global UK Construction PMI, Thu 5 Nov. The survey last read 46.1, and a result clearly above or below that level gives a quick read on activity for listed builders, materials suppliers and related employment in the sector.
- BT Group, Thu 5 Nov. Q2 2027 figures focus attention on revenue trends and cost control in UK fixed line and mobile operations, which in turn shape how much cash the telecom can allocate between debt reduction, fibre rollout and shareholder returns.
- National Grid, Thu 5 Nov. Half year 2027 numbers put regulated asset base growth and operating margins in the spotlight, which are key inputs for how investors think about future allowed returns and the funding cost of UK network investment plans.
- US Non Farm Payrolls and Unemployment Rate, Fri 6 Nov. Consensus looks for payrolls at 65K with unemployment at 4.2%, and a print significantly away from those marks can shift US yields and the dollar, which often feeds through to UK equities and FX.
Sector & Industry Watch
Energy: Oil and Gas cool after strong year
Energy and Oil and Gas have eased over the past week, with both sectors down a little over 2% even though 12 month and year to date returns remain well ahead of the wider GB Market. Headlines around Shell refocusing its LNG portfolio, US crude stock draws and geopolitics keep day to day moves tightly tied to Brent and diesel prices.
If you hold fuel producers, the clean catalyst to watch now is tonight’s US crude and gasoline inventory reports, because sharp moves in oil can quickly influence both UK energy bills and cash generation expectations for London listed producers.
Metals and Mining: Sector under pressure as deals keep coming
Metals and Mining have had a softer patch, with the sector down just over 5% on seven day figures and Materials broadly tracking that weaker tone for the month. At the same time corporate news is busy, from ACG Metals’ Blue Moon Norway copper deal to Arkadian’s Greenland rare earth progress and Zanaga’s iron ore sampling milestone.
If miners feature in your ISA or SIPP, the key macro data point today is the euro area inflation flash, because any surprise there can shift expectations for European industrial demand that sit behind copper, iron ore and precious metal revenue potential for UK listed groups.
Real Estate: Property recovery leans on flexible offices
Real Estate has edged higher over the past week and month, helped by International Workplace Group’s solid Q3 update that highlighted demand for flexible office space. That recent strength sits alongside ongoing worries about debt costs and refinancing for landlords and student housing operators after earlier earnings softness.
If you own REITs or property developers, the pairing to focus on remains Thursday’s UK Construction PMI alongside the Bank of England decision, since building activity and the path of interest rates together influence rental prospects, asset values and how easily Real Estate companies can roll over loans.
Healthcare: Pharma and biotech supported by fresh funding
Healthcare and Pharmaceuticals & Biotech have been among the steadier areas recently, with seven day gains helped by AstraZeneca and fresh capital raises at Ondine Biomedical and Oxford BioDynamics. Those fundraisings underline how trial results, regulator meetings and access to capital often matter more for these groups than short term moves in PMIs or house prices.
If healthcare stocks sit in your pension or ISA, the main triggers to watch are upcoming clinical readouts and regulator interactions such as Ondine’s planned FDA timetable or access updates like Shield Therapeutics’ Medicaid story, because these events can change revenue expectations much faster than broad macro releases.
Tech and Semiconductors: Hot year, choppy week for chips
Tech has eased slightly on seven day numbers, while Semiconductors have seen a sharper pullback after a very large 12 month rise well above 100% and strong year to date gains. Profit taking has hit the more volatile chip stocks hardest, even as demand stories around AI infrastructure and electronics keep longer term interest in the space intact.
If you are exposed to UK Tech funds or semiconductor shares, the catalyst to track is today’s US ISM Services PMI, since that survey feeds into views on global IT and data centre spending that are important for revenue expectations at software, hardware and chip producers listed in London.
Where Are The Opportunities Now?
With Metals and Mining under pressure over the past week, you can focus your research on this list of 33 best rare earth metal stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com