
Tokyo Steel Manufacturing (TSE:5423) As Lower Earnings Leave Its 19x P E Looking Pricey
Tokyo Steel Manufacturing (TSE:5423) has reported new figures, showing higher half-year sales, lower profit and earnings per share, and a reduced interim dividend that may influence how shareholders view the stock.
Recent price action suggests investors are still willing to back Tokyo Steel Manufacturing despite the softer earnings and lower payout. The share price is at ¥1,771, with a 19.74% year to date share price return and a 32.82% 1 year total shareholder return. Multi year total shareholder returns sit in the double digits, which points to momentum that has cooled in the short term but remains supportive over a longer horizon.
Spot opportunities beyond Tokyo Steel Manufacturing by scanning a curated set of steels and materials peers, built on cash flow strength and balance sheet resilience, through our list of solid balance sheet and fundamentals (22 results).Tokyo Steel Manufacturing now carries a stronger share price yet softer earnings and a trimmed interim dividend, which sets up a clear tension between optimism and caution. Which side does the valuation actually support?
Price-to-Earnings of 19x: Is it justified?
On current figures, Tokyo Steel Manufacturing trades on a P/E of 19x, which looks expensive next to peers even with the recent share price strength up to ¥1,771.
The P/E ratio compares the share price with earnings per share and gives a quick read on how much investors pay for each unit of profit. For a mature steel producer operating in a cyclical sector, a richer multiple often implies the market is willing to pay up for steady profitability or resilience in future downturns.
Here, the stock carries a P/E of 19x while the estimated fair P/E is 12x. That gap suggests the market is putting a much higher price on Tokyo Steel Manufacturing's earnings than the level a valuation model indicates it could settle toward. Profit margins recently moved from 5.6% to 3.3%, earnings over the last 5 years declined 17.6% per year, and return on equity sits at 4.3%, so the current premium asks investors to accept softer profitability on a higher earnings tag.
Against the broader JP Metals and Mining industry, where the average P/E is 10.6x, Tokyo Steel Manufacturing trades at a markedly richer level. The share also screens as expensive versus a peer average multiple of 11x, which reinforces the view that this is a premium valuation rather than a sector norm.
Explore the SWS fair ratio for Tokyo Steel Manufacturing.
Result: Price-to-Earnings of 19x (OVERVALUED)
Still, Tokyo Steel Manufacturing faces risk if the recent net income growth of 1.36% and profit margins at 3.3% fail to support that richer 19x P/E.
Find out about the key risks to this Tokyo Steel Manufacturing narrative.
Another view using the SWS DCF model
A different lens tells a similar story. Our DCF model points to a future cash flow value of ¥1,454.96 per share, while Tokyo Steel Manufacturing trades at about ¥1,760. That gap suggests investors are paying well above what cash generation alone might support. Could sentiment be running ahead of fundamentals?
Look into how the SWS DCF model arrives at its fair value.
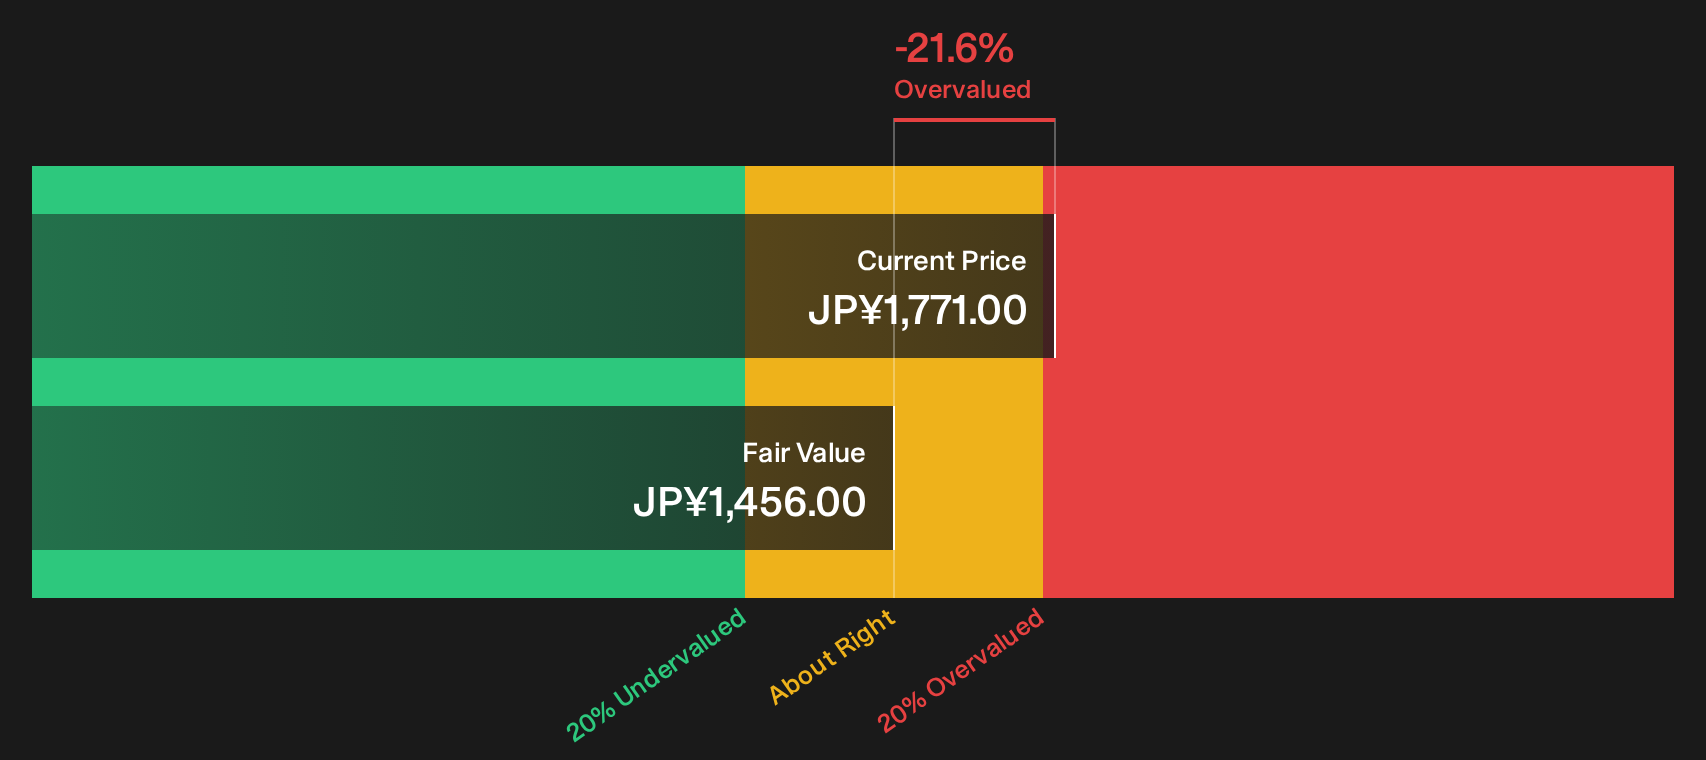
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Steel Manufacturing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Tokyo Steel Manufacturing can feel confusing, so use that to your advantage and pressure test the story yourself while sentiment is still forming. To frame both sides of the debate in one place, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Tokyo Steel Manufacturing?
If Tokyo Steel Manufacturing feels fully priced, do not stop there. Use the screener to surface fresh opportunities that fit your return and risk preferences.
- Target stronger upside potential by focusing on companies that look mispriced on fundamentals through our 18 high quality undervalued stocks.
- Prioritise portfolio resilience by zeroing in on businesses with robust finances using the 22 resilient stocks with low risk scores.
- Spot future leaders early by tracking high quality companies that the market has not yet crowded into via the 74 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com