
Why Viasat (VSAT) Is Back In The Spotlight
Viasat (VSAT) has been in focus after two recent announcements. A new memorandum of understanding with Terrestar Solutions and Space42 on interoperable satellite infrastructure, and the Maxwell spacecraft launch for NASA’s Communications Services Project, both highlight its next generation service ambitions.
Those announcements landed after a sharp run, with Viasat’s share price at US$75.24 and a year to date share price return of about 100%, while the 1-year total shareholder return of roughly 103% and very large 3-year total shareholder return point to momentum that has been building despite a 90-day share price decline of just over 7%.
Scan 53 AI infrastructure stocks to see other satellite and communications players pursuing the same kind of next generation data links that Viasat is targeting with Equatys and its NASA relay work.
After that kind of surge, and with Viasat trading below the average analyst target yet above some intrinsic value estimates, the real puzzle is where fair value sits within that range.
Most Popular Narrative: 28% Undervalued
On the most followed narrative, Viasat’s fair value of $103.94 sits well above the last close at $75.24. This puts the recent rally in a different light and frames the current move as only part of the valuation gap that narrative is trying to explain.
The main thing that has to go right is that Viasat converts its expanded multi-orbit capacity, MSS spectrum position, and Equatys partnership into durable cash generation while managing competitive and regulatory pressures in aviation, maritime, and fixed broadband.
The current valuation implies the market is not fully pricing in the potential value of Viasat’s MSS spectrum, direct-to-device opportunities, and ongoing free cash flow and deleveraging progress.
See why 30 investors see Viasat as 28% undervalued.
Result: Fair Value of $103.94 (UNDERVALUED)
Still, Viasat’s story can break if heavy capex keeps leverage high or if spectrum and authorisation hurdles curb how much new capacity actually earns.
Find out about the key risks to this Viasat narrative.
Another View On Viasat’s Valuation
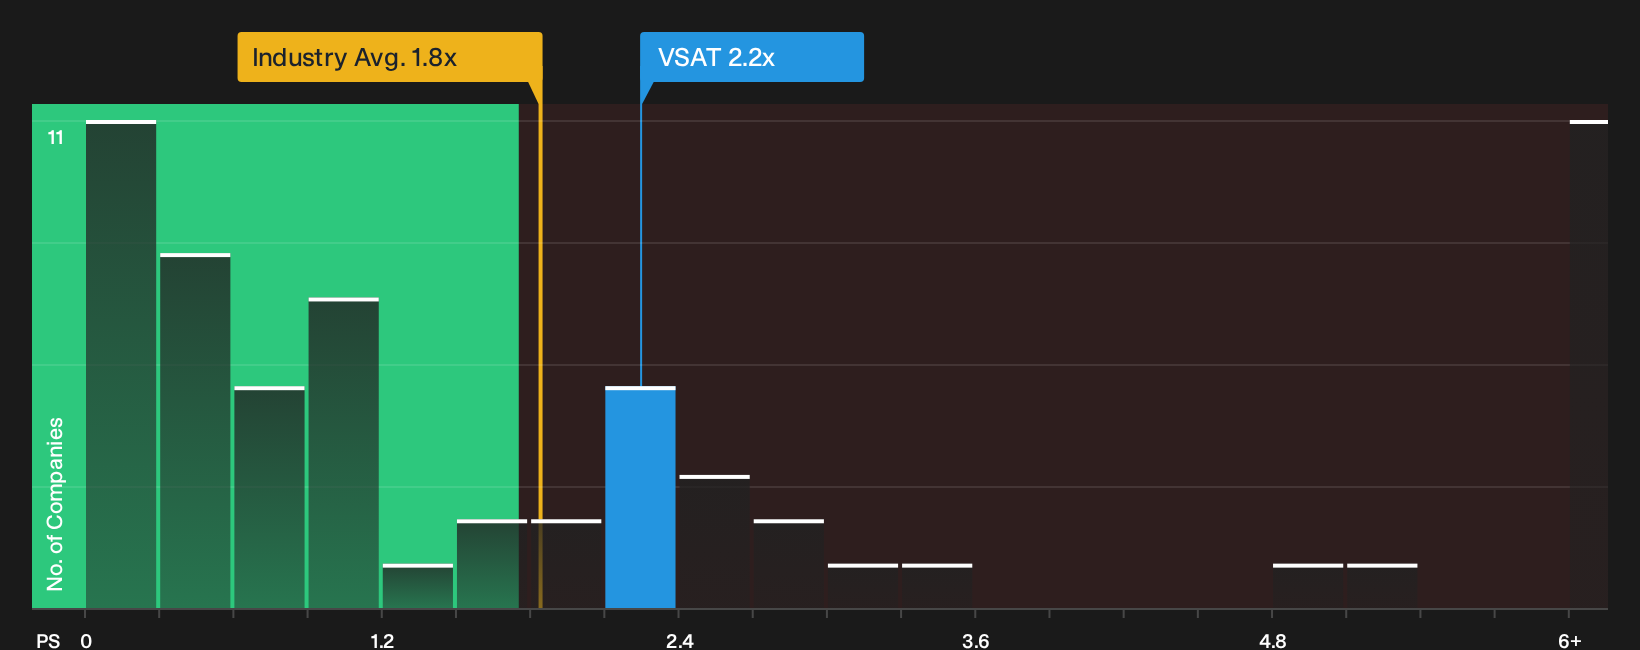
That 28% upside narrative leans on earnings and future multiples. A different yardstick, the P/S ratio, tells a cooler story. Viasat trades around 2.2x sales, a touch richer than the US Communications average at 2.1x and above a fair ratio of 1.7x, which points to some valuation risk if sentiment normalises. The same 2.2x looks much cheaper against peers at 7.9x, so the question is whether the market converges toward the broader sector or that lower fair ratio.
For a deeper look at how this P/S view was built and stress tested, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether this mostly optimistic read on Viasat matches your own instincts? Run the numbers yourself, move quickly, and weigh those 3 important warning signs.
Looking for more investment ideas beyond Viasat?
Do not stop your research with a single ticker. Broaden your watchlist with a few focused screens that surface different types of opportunities in seconds.
- Target deep value first by scanning companies that currently screen as 35 high quality undervalued stocks and are backed by stronger fundamentals than their prices suggest.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (23 results) so you can focus on businesses that may be better positioned to handle shocks when conditions turn rough.
- Hunt for potential future leaders by checking a curated pool of 19 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com