
Should Product Recall Require Action From United Natural Foods (UNFI) Investors?
- Snack Right Super Foods Inc., doing business as Brad's Raw Chips, previously recalled Brad's Plant Based Crunchy Kale and Brad's Veggie Chips Kale due to potential thallium contamination in roughly 25,000 bags distributed nationwide through KeHE Distributors and United Natural Foods.
- The incident highlights how product safety issues at smaller brands can still create operational and reputational pressure for United Natural Foods, given its role as a large distributor in organic and specialty categories.
- We will now look at how United Natural Foods' investment narrative could be affected by distributing recalled products tied to potential contamination.
United Natural Foods Investment Narrative Recap
To own United Natural Foods, you have to believe the distributor can turn modest category growth in natural and specialty goods into steadier earnings, even with thin margins and a heavy capital spend on IT and automation. The key near term swing factor is execution on efficiency programs and contract profitability, not isolated supplier issues.
The Brad's Raw Chips recall looks operationally contained for United Natural Foods, given the limited volume involved relative to more than US$31b in annual revenue. The bigger risk still sits in customer concentration and pricing pressure as large grocers push harder on terms, while the main opportunity is sustaining recent profitability after a period of one off hits.
With no major fresh announcements tied directly to this recall, the most relevant context remains United Natural Foods' recent return to profitability and its ongoing investment in supply chain systems, traceability, and automation. Those projects are designed to tighten quality control and inventory visibility, which matters when any contamination issue touches a distributor.
For catalysts, the recall keeps a spotlight on whether these technology and process upgrades reduce disruption risk and protect key relationships with retailers that rely on consistent, safe supply. For a shareholder, the watchpoint is simple: Do these operational upgrades translate into more resilient margins and better coverage of interest costs while handling occasional product incidents like this one?
United Natural Foods' current analyst narrative points to revenues of US$32.9b and earnings of US$262.0m by 2029. That profile lines up with forecast revenue growth of 1.9% per year and implies an earnings increase of US$178.0m from US$84.0m today.
Discover why United Natural Foods' fair value indicates an 18% potential upside to its current price that may not last much longer.
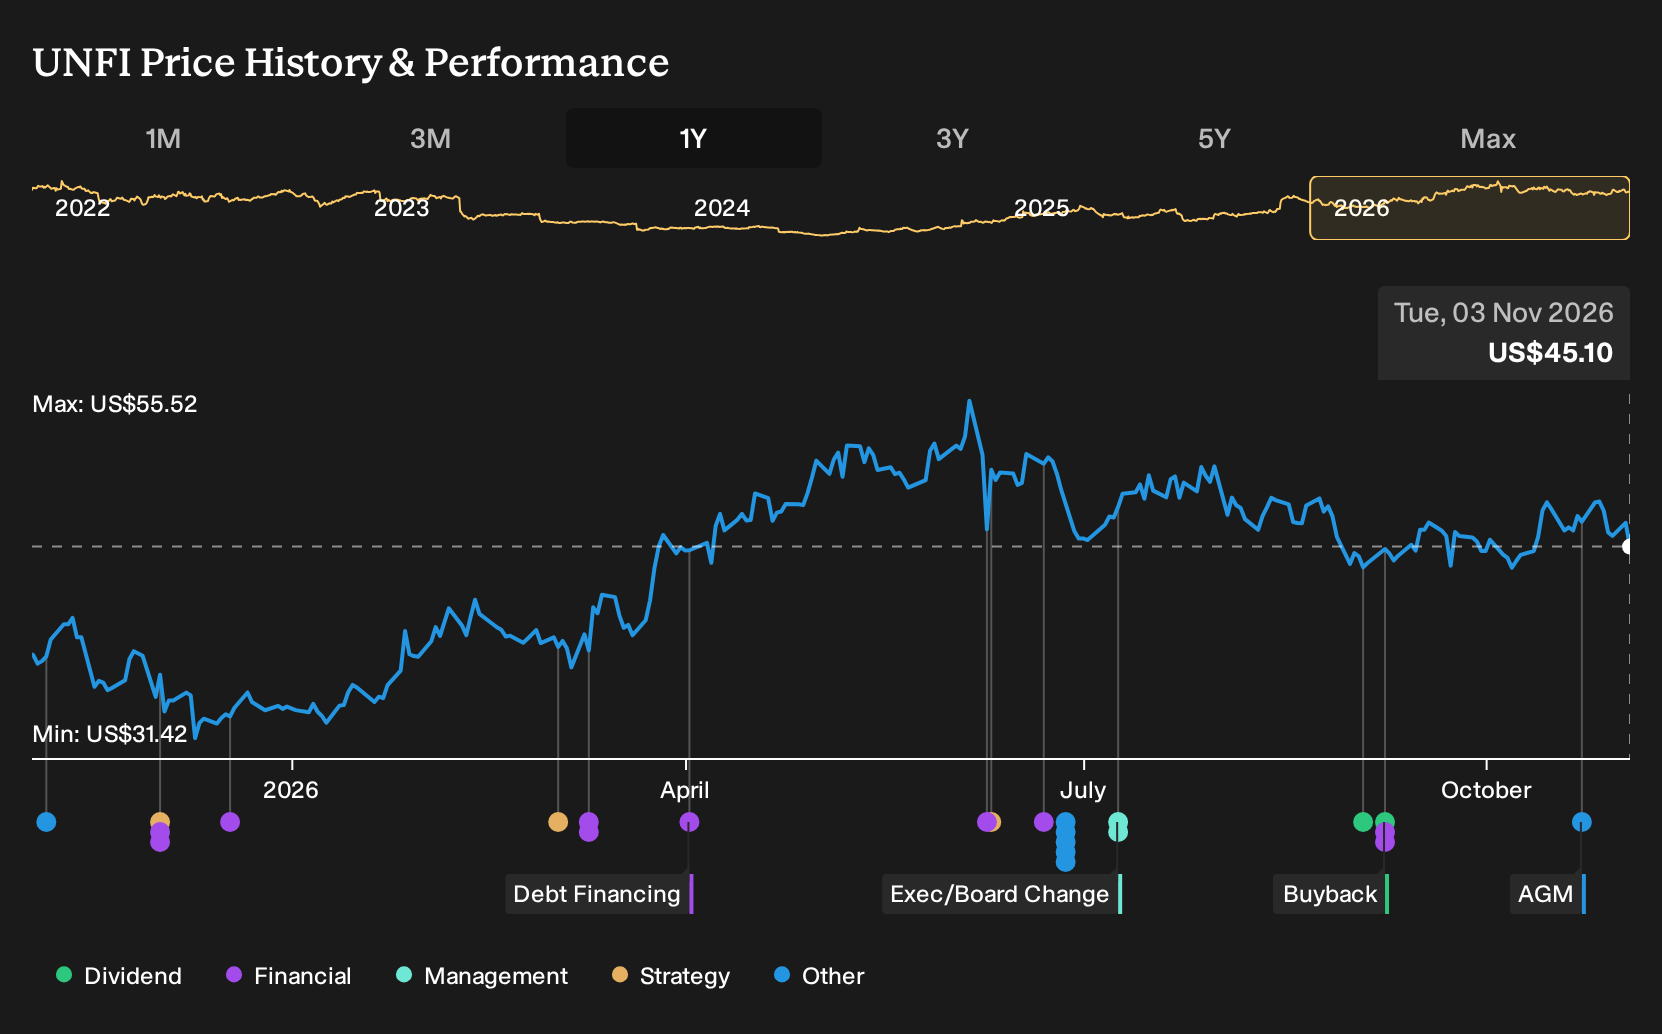
Exploring Other Perspectives
One alternate view on United Natural Foods puts more weight on fuel and transport costs than on recalls like Brad's Raw Chips. The most cautious analysts were already pencilling in roughly US$32.9b of revenue and about US$267.8m of earnings by 2029, yet still saw only a US$45.0 price target. Opinions clearly span a wide range, so treat this recall as a fresh input that could influence both the optimistic and pessimistic scenarios you compare.
Explore 3 other United Natural Foods fair value estimates, including one that suggests it could be worth just $45.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Natural Foods research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Natural Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Natural Foods' overall financial health at a glance.
Looking for more investment ideas beyond United Natural Foods?
Once you have a view on United Natural Foods, it helps to widen the lens and compare it with other businesses that fit different risk and balance sheet profiles. The Simply Wall St Screener can help you quickly surface candidates that match the type of portfolio you want to build, rather than chasing whatever happens to be in the headlines.
- If capital preservation matters most, start with a curated 30 resilient stocks with low risk scores that focus on resilience and lower overall risk scores than the broader market.
- For readers hunting for quality at a reasonable tag, scan a 35 high quality undervalued stocks that combine stronger fundamentals with more modest pricing than many peers.
- If you want sturdier balance sheets backing the story, work through a list of solid balance sheet and fundamentals (23 results) that pair healthier leverage and liquidity with underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com