
Is Horace Mann Educators (HMN) Undervalued On Its Earnings Beat?
Horace Mann Educators (HMN) just posted third quarter earnings that beat profit forecasts, while revenue of US$439.2 million came in slightly below expectations and was flat compared with the prior year.
Horace Mann Educators’ recent earnings surprise lands at a share price of US$47.47, with the stock showing a 4.88% 1 month share price return but a 3 month share price return that is down 8.89%. The 3 year total shareholder return of 61.00% points to stronger longer term momentum than the near term swings suggest.
Scan how Horace Mann Educators stacks up against other financially solid insurers and protection providers by reviewing our hand picked list of solid balance sheet and fundamentals (23 results) today.
After a sharp earnings beat but a 3 month pullback, Horace Mann Educators now sits at an interesting crossroads for fresh capital. Does the current share price still offer a favourable trade off between risk and reward?
Most Popular Narrative: 16% Undervalued
Against a narrative fair value of $56.50 and a last close of $47.47, Horace Mann Educators is framed as undervalued. The gap is tied closely to how its earnings mix could evolve over time rather than to the latest quarter alone.
Recent agreement to acquire three Medical Mutual businesses, expected to add nearly US$200 million of annual revenue, over 1,000,000 covered lives and 7,000 employer relationships along with US$20 million to US$25 million of net core earnings and about 100 basis points of ROE within 12 months of closing, points to additional scale in group benefits and employer solutions that can support revenue growth and returns.
See why 2 investors see Horace Mann Educators as 16% undervalued.
Result: Fair Value of $56.50 (UNDERVALUED)
Still, heavy reliance on the education sector and management’s lower 2026 net investment income outlook could both work against the current Horace Mann Educators narrative.
Find out about the key risks to this Horace Mann Educators narrative.
Another View: Cash Flows Point To A Richer Price
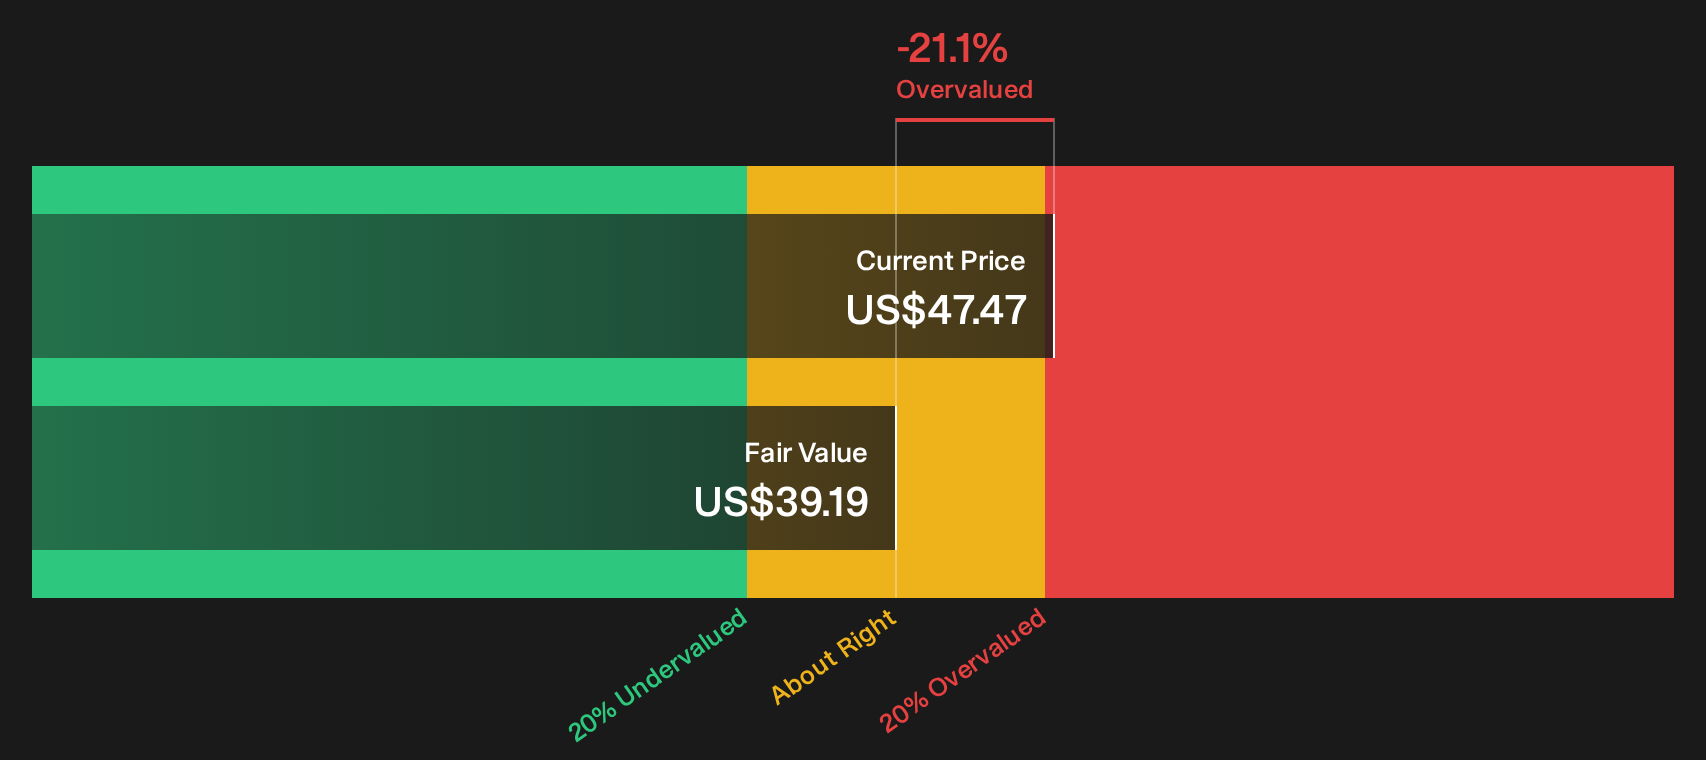
The narrative fair value of $56.50 paints Horace Mann Educators as 16% undervalued, yet Simply Wall St’s DCF model tells a different story. On that cash flow view, an estimate of $39.19 per share sits well below the current $47.47 price, which suggests less of a margin of safety than the narrative implies. Does that gap signal mispricing or just different assumptions about how dependable future cash flows really are?
For a closer look at how the modeled cash flows stack up against today’s share price, review how the SWS DCF model is built and what would need to change for the outputs to converge.Look into how the SWS DCF model arrives at its fair value.
Here is how that cash flow based appraisal lines up visually against the current market value and narrative fair value estimates.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Horace Mann Educators for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Horace Mann Educators so far. Weigh those concerns about risk against the potential upside by scanning the full picture of 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Horace Mann Educators?
If Horace Mann Educators has you rethinking your watchlist, use this moment to widen your search and pressure test your next move with fresh ideas.
- Target stronger income potential by reviewing companies that offer steady payouts and screen as 4 dividend fortresses.
- Spot quality businesses priced below their implied worth by scanning a curated set of 35 high quality undervalued stocks.
- Dial back portfolio risk by focusing on companies with sturdier finances using our 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com