
Advanced Micro Devices (AMD) Could Be 47% Undervalued As Q3 Results Reset The Debate
Advanced Micro Devices (AMD) stock is reacting to a clear catalyst. The company has just posted third quarter 2026 results, reporting revenue of US$13.377b and net income of US$2.428b, alongside updated nine-month figures.
The latest earnings have landed in the middle of a sharp sentiment swing. AMD’s 1-day share price return of 3.65% came after the stock fell 16.34% over the past week and 23.40% over the past month, a pullback that followed a very strong year-to-date share price return of 116.54% and a 1-year total shareholder return of 88.78%. The current bounce reflects traders reassessing growth potential and risk after a string of AI focused customer wins and fresh data center guidance.
Capture this AI-driven swing in Advanced Micro Devices by scanning hand-picked peers riding similar demand with the 53 AI infrastructure stocks.Advanced Micro Devices now trades about 20% below one fair value estimate and roughly 25% under the average analyst target after that steep pullback. Is this discount compensation for real risk, or is caution overshooting the numbers?
Most Popular Narrative: 47% Undervalued
Advanced Micro Devices is being valued very differently by the most followed thesis compared with the market price. That narrative points to a fair value of $907.32 against the latest close of $483.90, which puts a sizable gap between what traders are paying and what long term believers think the business is worth.
The market previously priced AMD as a "forced choice" spillover. Recent quarters, particularly the massive Data Center revenue run-rates achieved into 2026, have completely shattered this narrative. AMD is no longer just a GPU alternative; it has cemented itself as the definitive "End-to-End AI Platform." With hyperscalers aggressively expanding their infrastructure, AMD is rapidly scaling from a "Second Player" into the absolute backbone of modern AI data centers.
See why 198 investors see Advanced Micro Devices as 47% undervalued.
On that view, the discount is not just about short term sentiment around a 16% weekly pullback. It reflects a belief that AMD's shift toward data center, where the firm generated $22.214b of segment revenue out of $41.305b total, supports a much higher long term earnings power than the current share price implies.
Supporters of this thesis point to a few anchors in the latest data. Earnings rose 137.4% over the past year compared with a 10.9% per year clip over five years, profit margins sit at 15.7% versus 9.2% a year ago, and earnings are forecast to grow 38.7% per year, faster than both the wider US market at 17% and sector level growth of 45.6% over the past year. Revenue is also projected to grow 32.6% annually, ahead of the US market at 13.2%.
The same framework assumes that this expansion in AI focused sales and margin mix can support a long run profit margin of 32% and a future P/E of 30x. This then feeds into that $907.32 narrative fair value using an 8% discount rate. That compares with the current implied P/E of 122.1x and a fair P/E estimate of 50.5x, highlighting how much of today’s valuation depends on cash flows many years out.
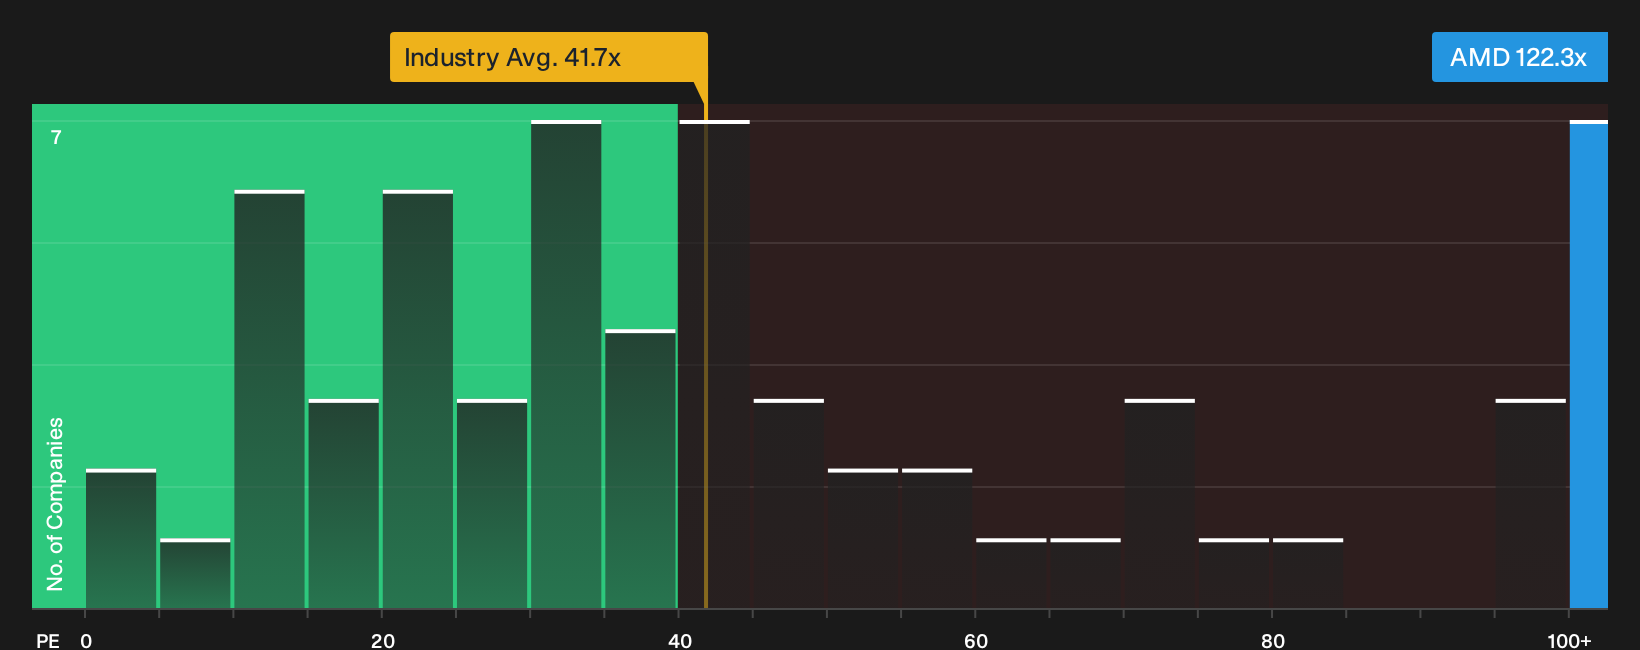
There are still tension points. AMD screens as expensive relative to its sector on several traditional checks, with its current P/E well above peer averages of 37.6x and the broader US Semiconductor industry on 43.5x. Analyst targets are about 25% above spot at $649.38, although those forecasts do not sit in a tight range, and board oversight includes higher CEO compensation of $55.16m compared with a $14.84m peer median and a pay rise above 20% in the last year.
Yet the discount to cash flow based work remains clear. AMD trades 20.3% below one internal fair value estimate and below a future cash flow value of $607.16 from the SWS DCF model, which uses projected cash flows rather than near term earnings multiples. Combined with a 46.7% gap to the $907.32 narrative fair value, that is the spread investors are now weighing up against execution risk and AI demand sustainability.
Result: Fair Value of $907.32 (UNDERVALUED)
Still, the bullish Advanced Micro Devices narrative can crack if hyperscalers slow AI infrastructure orders or if competing chips compress AMD’s pricing power and future margin potential.
Find out about the key risks to this Advanced Micro Devices narrative.
Another View: Advanced Micro Devices Through Earnings Multiples
There is a very different message coming from a simple earnings ratio check. On a P/E of 122.1x against a fair ratio of 50.5x, Advanced Micro Devices screens as richly priced, and also far above peer averages of 37.6x and the wider US Semiconductor group on 43.5x. Does that premium reflect durable AI firepower, or just crowded enthusiasm after a strong run?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Recent moves around Advanced Micro Devices split opinion. If you want to move past the noise and weigh the upside yourself, start with the 3 key rewards.
Looking for more investment ideas beyond Advanced Micro Devices?
Do not stop with one ticker. Broaden your watchlist using focused stock lists that surface different kinds of opportunities and help you pressure test your thesis on AMD.
- Target potential mispricings by scanning a curated set of companies that screen as high quality and attractively valued through the 35 high quality undervalued stocks.
- Strengthen your focus on resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you spot businesses built to handle tougher conditions.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that may not yet be widely followed but already show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com