
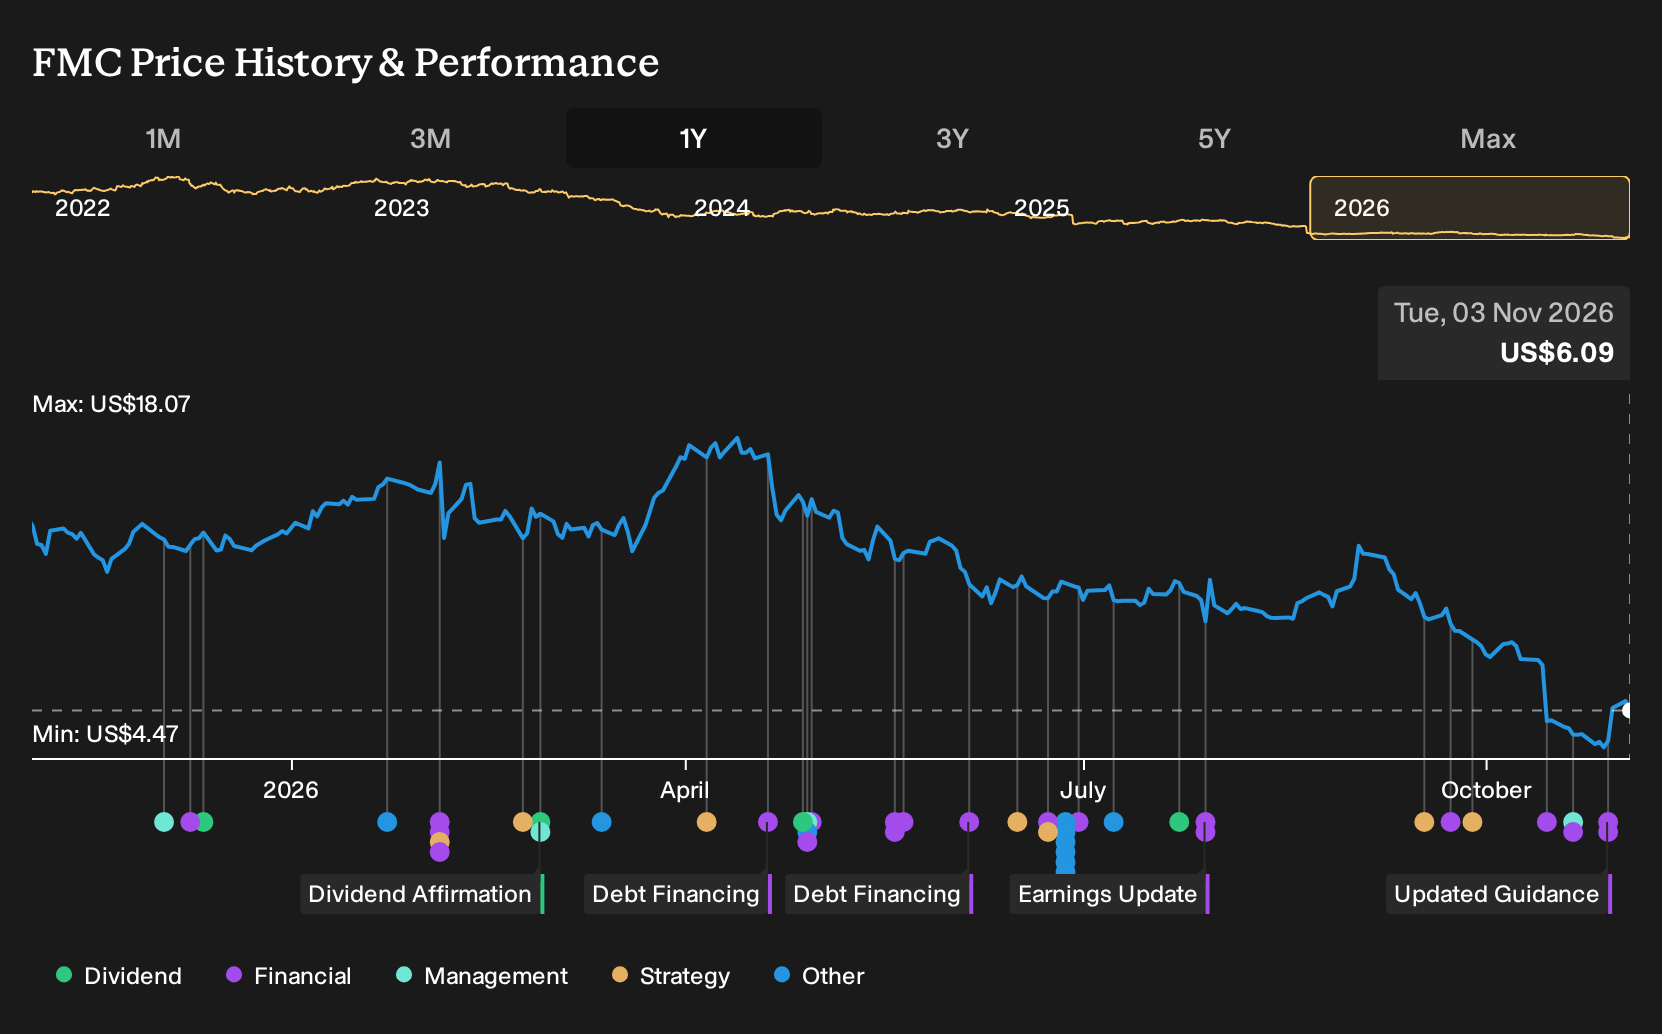
Why FMC Stock Is Down 6.3% And What's Next After Weak Earnings
- FMC Corporation reported very weak third quarter 2026 results, with sales of US$105.9 million compared with US$542.2 million a year earlier and a net loss of US$2,066.9 million. The company also projected a large year over year revenue decline for full year 2026.
- The latest numbers highlight how patent expirations, heavy debt, channel inventory issues and restructuring linked to exiting commercial operations in India are weighing on FMC’s earnings profile and financial flexibility.
- The focus will now be on how FMC’s weaker 2026 outlook and sharp quarterly loss affect the earlier investment narrative around portfolio transition.
FMC Investment Narrative Recap
To stay on board with FMC, a shareholder needs to believe the portfolio shift to newer patented molecules and biologicals can gradually offset pressure on older chemistries and pricing. The third quarter 2026 sales drop to US$105.9 million and net loss of US$2,066.9 million underline how far the starting point has moved. The most important near term catalyst is execution on that product transition at the same time as volumes recover in key regions.
The biggest risk right now is that high leverage and pricing pressure collide with weaker than expected operating cash flow. Full year 2026 guidance for revenue excluding India of US$2.75 billion to US$2.85 billion, which implies a sizeable year over year fall, keeps that concern front and center. If new products and direct to grower efforts do not gain traction fast enough, balance sheet flexibility stays tight.
The revised fourth quarter and 2026 outlook announced on 29 October sits at the center of this story. Management now expects fourth quarter revenue excluding India in the US$1.04 billion to US$1.14 billion band. High single digit price declines are expected to be offset by volume growth from Brazil direct to grower sales, new products and sharper pricing. That mix goes straight to the question of whether FMC can trade price for volume without eroding long run economics.
For catalysts, this update is important because it gives a clearer hurdle for operational progress over the next few quarters. Investors can track whether volume gains on newer actives and Brazil execution show up in reported sales, and whether that supports the plan to gradually de risk the balance sheet. Analyst rating language around equal weight or neutral sits in the background here, while cash generation, debt paydown and product mix are what really matter for the FMC thesis.
FMC's current analyst narrative points to US$3.4b in revenue and US$203.2 million in earnings by 2029. This is based on an assumption of revenue growth of 1.8% per year and an earnings swing of about US$2.9b from current earnings of a US$2.7b loss to the projected profit level.
Uncover why FMC's fair value indicates a 43% potential upside to its current price, a discount that could close sooner than many investors anticipate.
Exploring Other Perspectives
You can see a very different angle when you look at the most bearish FMC forecasts. Before this earnings shock, the lowest analysts were pencilling in roughly flat revenue around US$3.2b by 2029, but still projecting earnings of about US$335.6 million. That is a far more cautious story than the consensus, and this fresh update may push those views to shift again.
Explore 4 other FMC fair value estimates, including one that suggests as much as 34% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your FMC research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for FMC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate FMC's overall financial health at a glance.
Looking For More Investment Ideas Beyond FMC?
If FMC's recent reset has you reassessing risk and reward, it can help to widen your watchlist and compare this situation with other businesses that have different balance sheets, income profiles and dividend policies.
- For investors who care most about valuation support and quality fundamentals, review a 35 high quality undervalued stocks that already filters for resilient cash flows and stronger financial footing.
- If capital preservation ranks higher on your list than aggressive upside, focus on stability with a 30 resilient stocks with low risk scores designed to highlight stocks with lower risk scores.
- Income focused investors can concentrate on cash returns by scanning 4 dividend fortresses that aim for yields above 5% while still keeping an eye on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com