
Viper Energy (VNOM) Stock Looks Overvalued With Earnings In Focus
Viper Energy has delivered a 27.5% gain over the past year, so the current share price puts a spotlight on a simple question for investors. Are you now paying a level that is fully backed by the company’s earnings power, or has the recent performance moved ahead of what the profit stream can reasonably support?
- Viper Energy is up 27.5% over the past 12 months, which raises the stakes on whether that share price move is aligned with what its earnings justify.
- Recent acquisitions of royalty acreage in the Permian Basin can reshape the future earnings base by affecting how much royalty income flows through with relatively low operating costs.
- There is a second opinion on Viper Energy worth weighing. See what analysts think Viper Energy's shares could be worth.
The stock's next move may depend on whether Viper Energy's current earnings are strong and resilient enough to support today’s valuation.
If you want to stress test the same earnings question you are asking of Viper Energy across a wider field, scan through 34 high quality undervalued stocks.
Is Viper Energy Getting Expensive on Earnings?
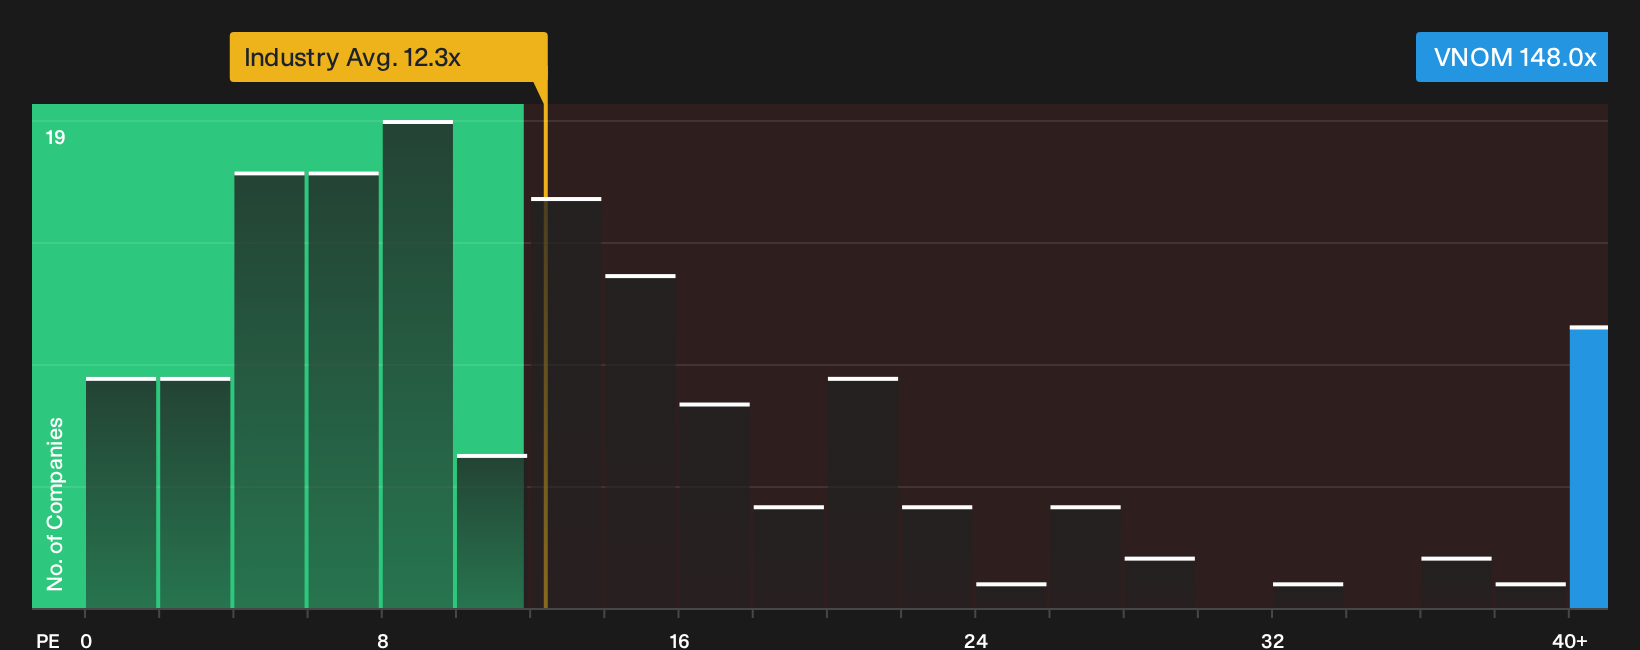
P/E works well for Viper Energy because the business earns income on royalty interests with relatively lean operating costs, so net profit is a key yardstick. On that yardstick, the stock trades on a P/E of about 148.0x, compared with an Oil and Gas sector average near 12.3x and a peer group around 19.0x. That is a very steep premium to both the broader industry and closer royalty and energy comparables.
The fair multiple implied by a more tailored model, which folds in Viper Energy’s margins, growth profile, size and risk, sits far below today’s P/E, so the shares screen as overvalued on this framework. Recent acquisitions like Riverbend and McElroy Ranch, along with the declared dividend and buybacks reported in 2026, help explain why sentiment is strong, yet the current earnings multiple still prices in a lot of optimism. If you hold the line on earnings as the anchor for what you are willing to pay, this kind of gap can matter a lot to the risk and reward trade off at today’s price. Explore the numbers behind Viper Energy's P/E valuation.
The Viper Energy Narrative: What Would Justify Today's Price?
Narratives for Viper Energy pick up where the P/E puzzle leaves off by spelling out which paths for future revenue, earnings and margins would need to play out for the current share price to look either stretched or conservative. Instead of a single figure from a ratio or model, they lay out the future conditions those numbers rely on so you can watch how Viper Energy's actual results line up with the story on Simply Wall St's Community page.
Community views on Viper Energy split between those who see hidden value in the mineral estate and those who think the market already prices in a lot of good news.
Bull case: 21% undervalued
"Viper is not merely a stream of today''s royalty checks. It is ownership of a large Permian mineral estate through which thousands of existing wells already produce..."
Discover why this Narrative puts Viper Energy at 21% undervalued.
Bear case: 38% overvalued
"As I just briefly explained, the company has a high-margin business model, as it does not incur drilling costs..."
Explore why this Narrative puts Viper Energy at 38% overvalued.
One last Viper Energy check that sits beyond today's P/E debate
Price ratios frame where Viper Energy trades today, but the analyst view of where earnings and cash generation could be a few years from now offers a different reference point. Explore where analysts expect Viper Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com