
Onto Innovation (ONTO) Nears Earnings With Analyst Optimism, Is The Valuation Still Too Rich?
Onto Innovation (ONTO) is back in focus after a 5.05% share decline ahead of its November 9 earnings release, as expectations for stronger earnings and revenue are drawing heightened attention from analysts and investors.
That near term slide fits into a choppy year for Onto Innovation, with the 30 day share price return down 38.25% and the 90 day move lower by 26.67%. Even so, the year to date share price return is 22.02% and the 1 year total shareholder return is 56.76%, which points to longer term momentum meeting shorter term profit taking as investors reassess risks ahead of earnings.
Scan opportunities moving with or against Onto Innovation's momentum by checking the hand picked 34 high quality undervalued stocks that combine quality fundamentals with potential mispricing.
For Onto Innovation, that steep short term pullback sits against strong multi year shareholder gains and analyst optimism ahead of earnings. Is this downdraft a signal about the business itself, or mainly a reset in sentiment that changes the valuation picture?
Most Popular Narrative: 47% Undervalued
The most followed narrative on Onto Innovation anchors on a fair value of about $380 per share versus the last close at $202.39. This is a wide gap that frames the pullback as a potential valuation reset rather than a simple loss of confidence.
Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision.
See why 39 investors see Onto Innovation as 47% undervalued.
Result: Fair Value of $380 (UNDERVALUED)
Still, the bullish Onto Innovation story can break if advanced packaging demand or key customer ramps disappoint, or if larger rivals outspend it in critical metrology niches.
Find out about the key risks to this Onto Innovation narrative.
Another View On Onto Innovation’s Valuation
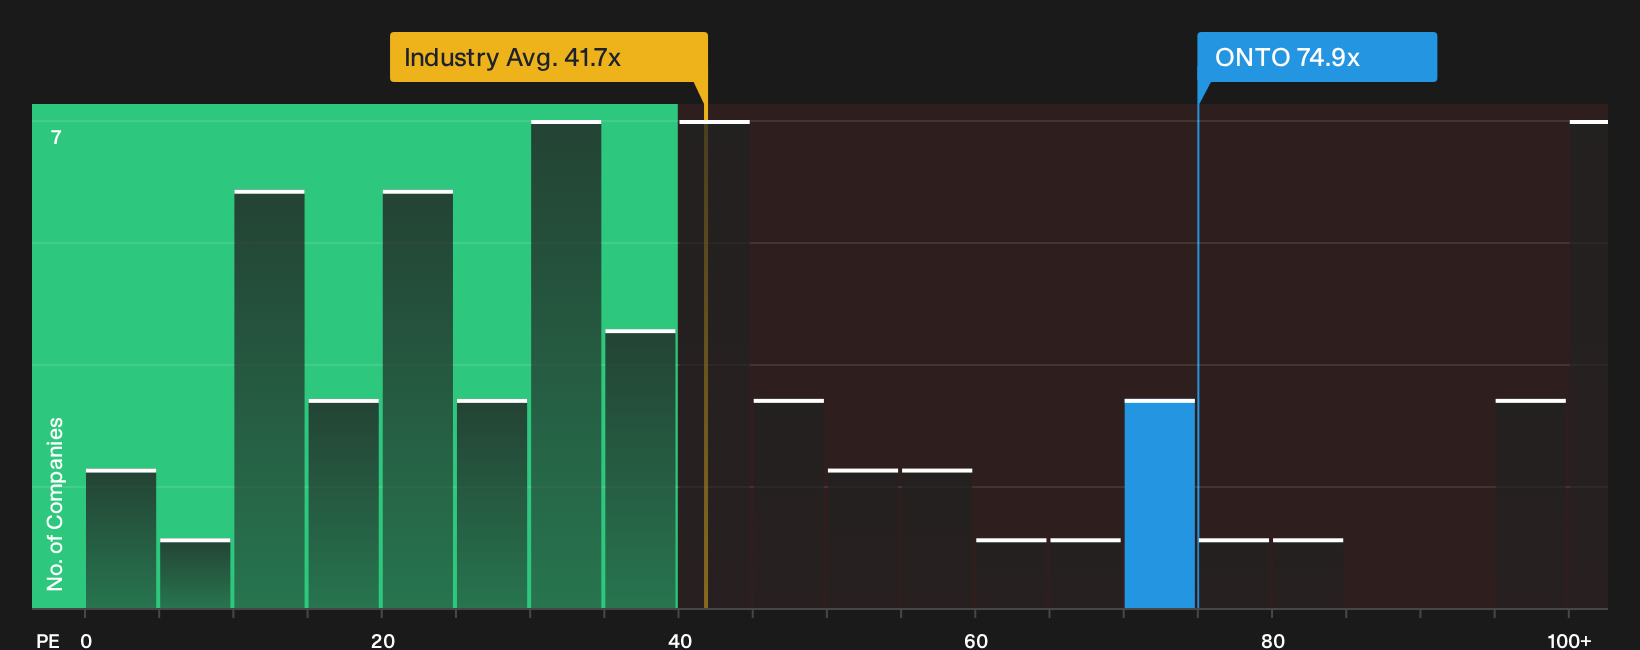
There is a sharp contrast between that US$380 fair value narrative and what simple earnings multiples imply. Onto Innovation trades on a P/E of 74.9x, compared with a 41.7x average for the US Semiconductor industry, a 31.5x peer average, and a fair ratio estimate of 46.7x. That gap points to meaningful valuation risk if the market leans back toward those lower benchmarks.
For anyone weighing how that kind of earnings multiple could compress or hold up, it helps to see the full breakdown behind those ratios and assumptions, not just the headline premium, so See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Onto Innovation's setup right now. Act while the data is fresh, weigh the upside against the downside, and scan the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Onto Innovation?
Do not stop with Onto Innovation. Put fresh ideas on your radar by running a few focused screens and let the data surface opportunities you might otherwise overlook.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (24 results). This can help anchor a portfolio when sentiment swings.
- Spot potential mispricing quickly by scanning the 19 high quality undiscovered gems before the market fully pays attention.
- Dial down portfolio swings by focusing on the 30 resilient stocks with low risk scores. These pass strict resilience checks and still offer meaningful upside potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com