
Learn Why The Bull Case For Expand Energy Stock Could Change Following Production Guidance
- Expand Energy reported third quarter 2026 basic and diluted EPS from continuing operations of US$2.24, alongside nine month EPS from continuing operations of roughly US$9.30 on a basic basis and US$9.29 on a diluted basis, and affirmed a quarterly base dividend of US$0.575 per share payable in December 2026.
- The updated 2026 production guidance of roughly 7.45 to 7.55 Bcfe per day gives investors a clearer read on how Expand Energy is balancing output, capital use and cash returns in a gas market that management previously described as modestly oversupplied.
- This article examines how Expand Energy's broader investment narrative aligns with its latest earnings report and updated production guidance.
Scan beyond Expand Energy and identify other gas producers whose balance sheets and fundamentals appear able to support payouts of this kind by using the list of solid balance sheet and fundamentals (24 results).
Expand Energy Investment Narrative Recap
To own Expand Energy, you need to believe its integrated gas model and efficiency gains can matter more than a modestly oversupplied market. The latest quarter shows EPS from continuing operations broadly in line with last year, which helps support that view. The key near term swing factor remains gas prices relative to the firm’s cost and breakeven progress.
The biggest risk is still extended price pressure if supply stays heavy into 2027, which could cap the benefit of volume and marketing initiatives. This new earnings print does not materially change that risk reward balance, but it does reinforce that execution on costs and marketing remains central.
The most relevant update for that thesis is the 2026 production guidance of about 7.45 to 7.55 Bcfe per day. That range gives you a concrete sense of how Expand Energy plans to run its asset base while the gas market is described as modestly oversupplied.
For catalysts, that volume plan sits alongside ongoing work on the integrated marketing platform and Twin Eagle synergies. The combination means investors can track two things at once: whether production stays within guidance and whether marketing and efficiency gains help cushion realized pricing risk over the next few years.
Expand Energy's narrative projects US$12.9b revenue and US$3.2b earnings by 2029. This implies relatively flat annual revenue growth and an increase in earnings of about US$0.4b from US$2.8b today.
Uncover why Expand Energy's fair value indicates a 36% potential upside to its current price that may not last much longer.
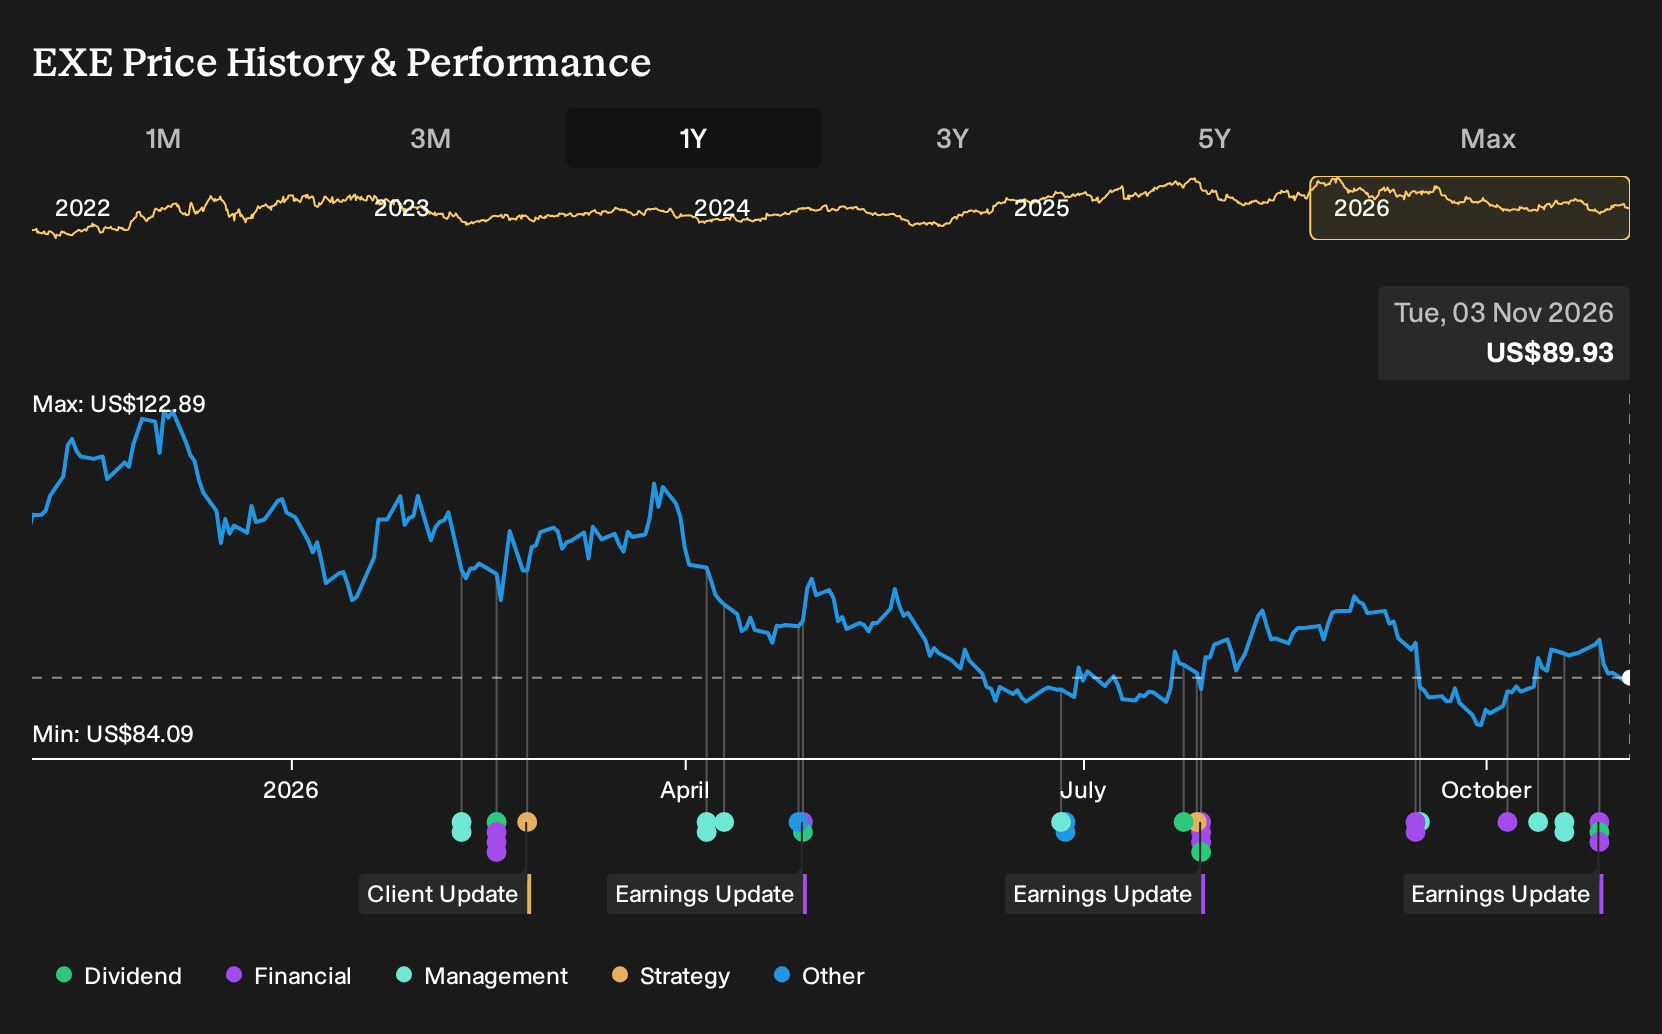
Exploring Other Perspectives
One alternate view focuses on marketing execution risk rather than efficiency gains. The most pessimistic analysts were modelling 2029 revenue of about US$10.7b and earnings of US$2.3b, compared with the baseline US$12.9b and US$3.2b before this earnings release. Those lower figures reflect concern that Expand Energy’s premium pricing plans may deliver less uplift than hoped. You can treat this latest EPS and production update as a fresh data point and decide which camp you lean toward as forecasts adjust.
Explore 4 other Expand Energy fair value estimates, including one that suggests it could be worth just $108.01!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Expand Energy research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Expand Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expand Energy's overall financial health at a glance.
Looking for more investment ideas beyond Expand Energy?
Once you have a view on Expand Energy, it can help to line it up against other opportunities that match your risk tolerance and income needs. The Simply Wall St Screener lets you quickly filter the market so you can keep a watchlist that really fits your goals instead of chasing every headline.
- If you want potential upside with strict quality filters, start with a curated set of 19 high quality undiscovered gems that pair sturdy fundamentals with cleaner balance sheets.
- For defensively minded investors who care about capital resilience first, focus on companies flagged as having lower overall risk across key metrics through the 30 resilient stocks with low risk scores.
- If income is a priority and you want payouts that look more durable on paper, center your search on businesses highlighted as 4 dividend fortresses to see which yields might suit a long term portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com