
How Investors Are Reacting To Booking Holdings (BKNG) Steady Third Quarter Earnings
- Booking Holdings reported third quarter 2026 revenue of US$8.893b and net income of US$2.717b, with basic earnings per share from continuing operations at US$3.62 and diluted earnings per share at US$3.61.
- Across the first nine months of 2026, Booking Holdings generated US$21.777b of revenue and US$5.75b of net income, highlighting its earnings power in the context of regulatory scrutiny and questions around the impact of AI travel agents on its model.
- This analysis will examine how Booking Holdings' largely steady third quarter profitability influences the investment narrative built around Connected Trip and AI.
Compare Booking Holdings' reset expectations and regulatory overhang with other travel and platform plays by scanning our curated list of 34 high quality undervalued stocks that the market may be pricing cautiously.
Booking Holdings Investment Narrative Recap
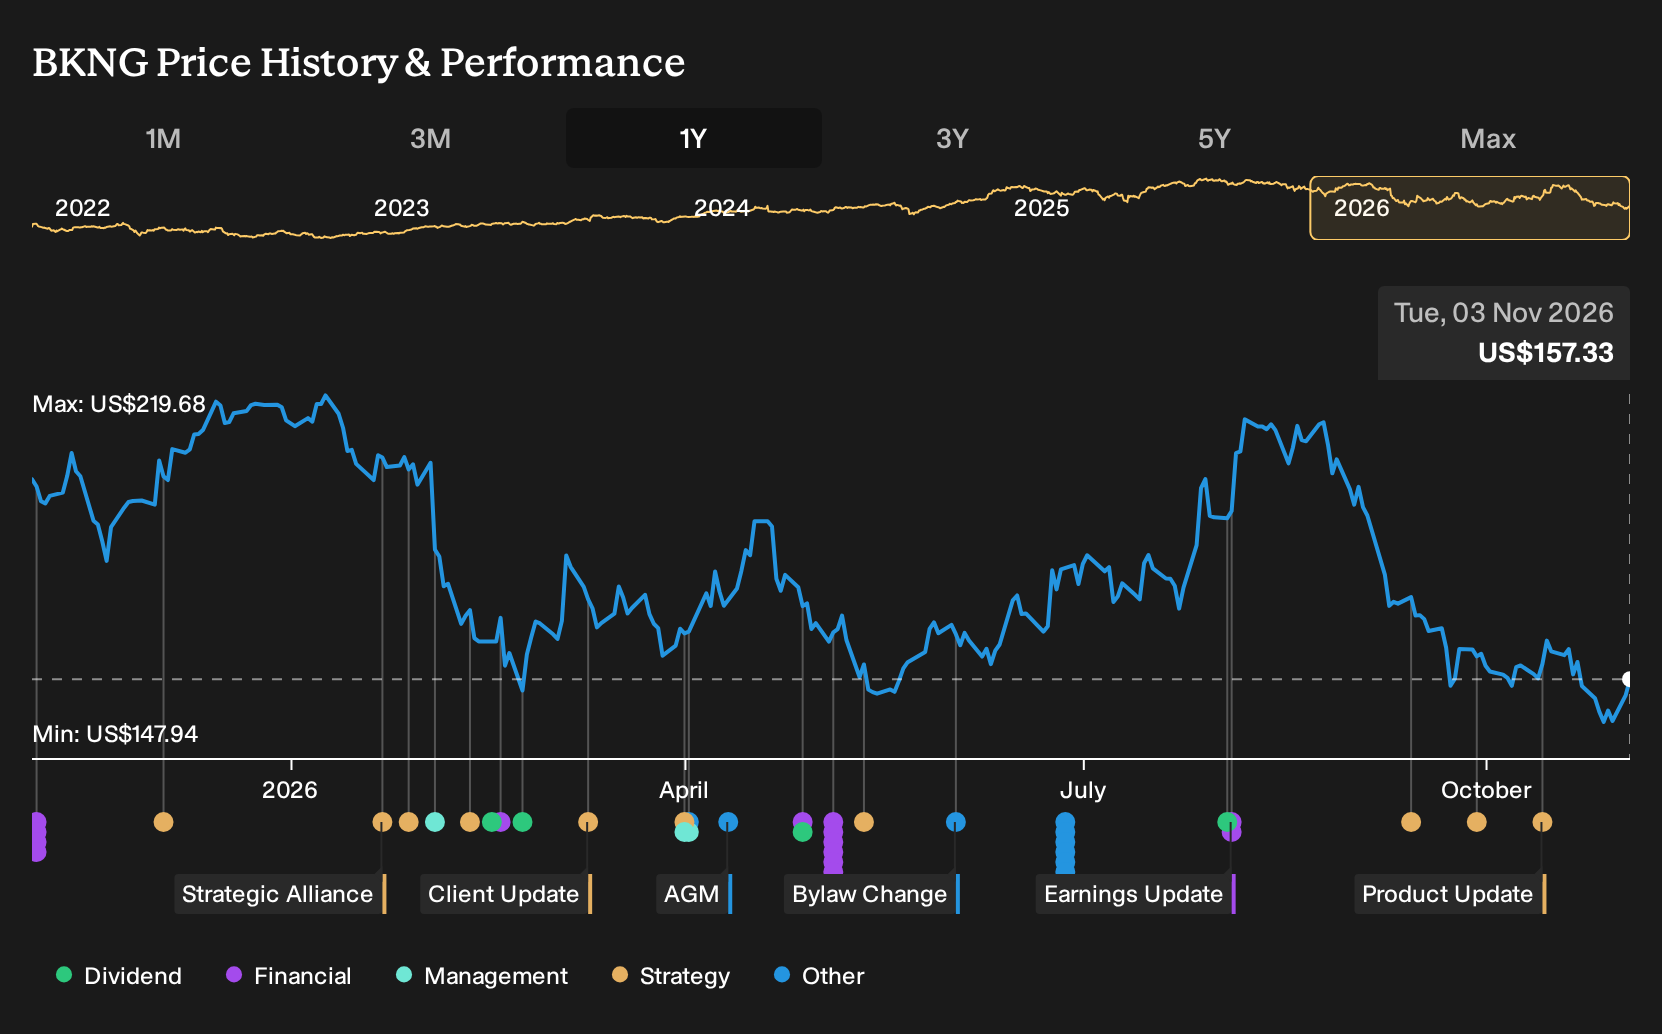
To own Booking Holdings, you need to believe its Connected Trip vision, AI rollout and heavy app and loyalty usage can keep travelers and partners engaged even as regulation and new AI agents reshape online booking. The latest quarter shows relatively stable profitability despite a small step down in quarterly revenue and net income year on year, so the core engine still looks intact.
The key near term swing factor is whether cross sell and direct, mobile traffic keep offsetting regulatory and fee pressure. The biggest risk remains regulatory and legal action in Europe and elsewhere, which could force changes to pricing, ranking and marketing that weigh on margins without giving much time to retool product or contracts.
The most relevant update for this earnings print is management’s continued emphasis on AI across Booking Holdings platforms and the Connected Trip build out. That context matters when you see basic EPS rise to US$3.62 in the quarter while revenue is slightly below the prior year, since it points to efficiency and mix as important levers, not just volume.
For you as a shareholder, the real question is whether these AI tools and the 73% merchant payments mix keep improving unit economics faster than regulatory and competitive pressures from third party AI agents and direct supplier channels erode them. Progress on alternative accommodations, Genius penetration and app share will be the operational signals to watch against that risk.
Booking Holdings' current analyst narrative points to revenue of US$36.2b and earnings of US$10.5b by 2029, based on an assumed 8.6% yearly revenue growth rate and an earnings increase of about US$3.3b from US$7.2b today.
Uncover how Booking Holdings' fair value indicates a 48% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Some of the most optimistic analysts framed third party AI agents as a potential upside for Booking Holdings rather than a threat, expecting revenue of about US$38.8b and earnings near US$11.8b by 2029. You can treat this quarter’s steady US$8.9b revenue and US$2.7b net income as a new data point that might reshape those views.
Explore 7 other Booking Holdings fair value estimates, including one that suggests as much as 3374% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Booking Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Booking Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Booking Holdings' overall financial health at a glance.
Looking for more ideas beyond Booking Holdings?
If the Booking Holdings story has sharpened your thinking, use that same lens across a broader watchlist. The Simply Wall St Screener lets you quickly narrow the field to companies that fit the balance of quality, risk and income that suits you.
- Focus on financial resilience by scanning a list of solid balance sheet and fundamentals (24 results) that can help if you care about stronger balance sheets backing the equity story.
- If capital preservation sits high on your list, filter for 30 resilient stocks with low risk scores and concentrate on businesses with lower overall risk scores.
- Prefer to hunt for less crowded ideas, where fewer eyes might be looking, by starting with 19 high quality undiscovered gems that already show strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com