
Spyre Therapeutics (SYRE) Could Be 19% Undervalued After Wider Quarterly Losses
Spyre Therapeutics (SYRE) is back in focus after reporting third quarter 2026 results that showed a net loss of US$96.12 million and wider per share losses from continuing operations.
Recent trading has been choppy. Spyre Therapeutics has a 1 month share price return of 6.52% and a year to date share price gain of 224.62%. However, the 3 month share price return fell 4.87%, while the 1 year total shareholder return of 331.98% and 3 year total shareholder return of almost 9x indicate strong longer term momentum that frames the latest earnings driven move as part of a much larger rerating story.
Compare this latest swing in Spyre Therapeutics with a curated group of biotech and high-risk growth names that have been screened for stronger balance sheets and fundamentals in our list of solid balance sheet and fundamentals (24 results).
Spyre Therapeutics now trades about 19% below the average analyst target after a sharp move and much heavier recent losses. Is that a valuation gap worth attention, or a warning the market is rightly cautious?
Most Popular Narrative: 17% Undervalued
The most followed valuation narrative puts Spyre Therapeutics at a fair value of about $120 per share, compared with a last close of $99.27. That gap reflects expectations that the IBD and autoimmune pipeline, plus the cash position, could justify a richer price if execution matches the story.
Positive Part A data from SPY001, SPY002 and SPY003 in ulcerative colitis and the move of all three into SKYLINE Part B across a large global site footprint could create a path to late stage IBD programs that, if successful, may expand Spyre Therapeutics revenue potential in the next decade.
The focus on combination efficacy gains in IBD of roughly 10 percentage points in clinical remission compared with existing drugs, in a market where a small group of therapies historically captures most revenue, means any successful Spyre Therapeutics regimen could concentrate prescribing and materially influence long run revenue and operating leverage.
See why 2 investors see Spyre Therapeutics as 17% undervalued.
Result: Fair Value of $120.08 (UNDERVALUED)
Still, the Spyre Therapeutics story can change quickly if SKYLINE or SKYWAY data underwhelm, or if insider selling continues to pressure confidence and funding flexibility.
Find out about the key risks to this Spyre Therapeutics narrative.
Another View: What Spyre Therapeutics’ Price Tag Signals
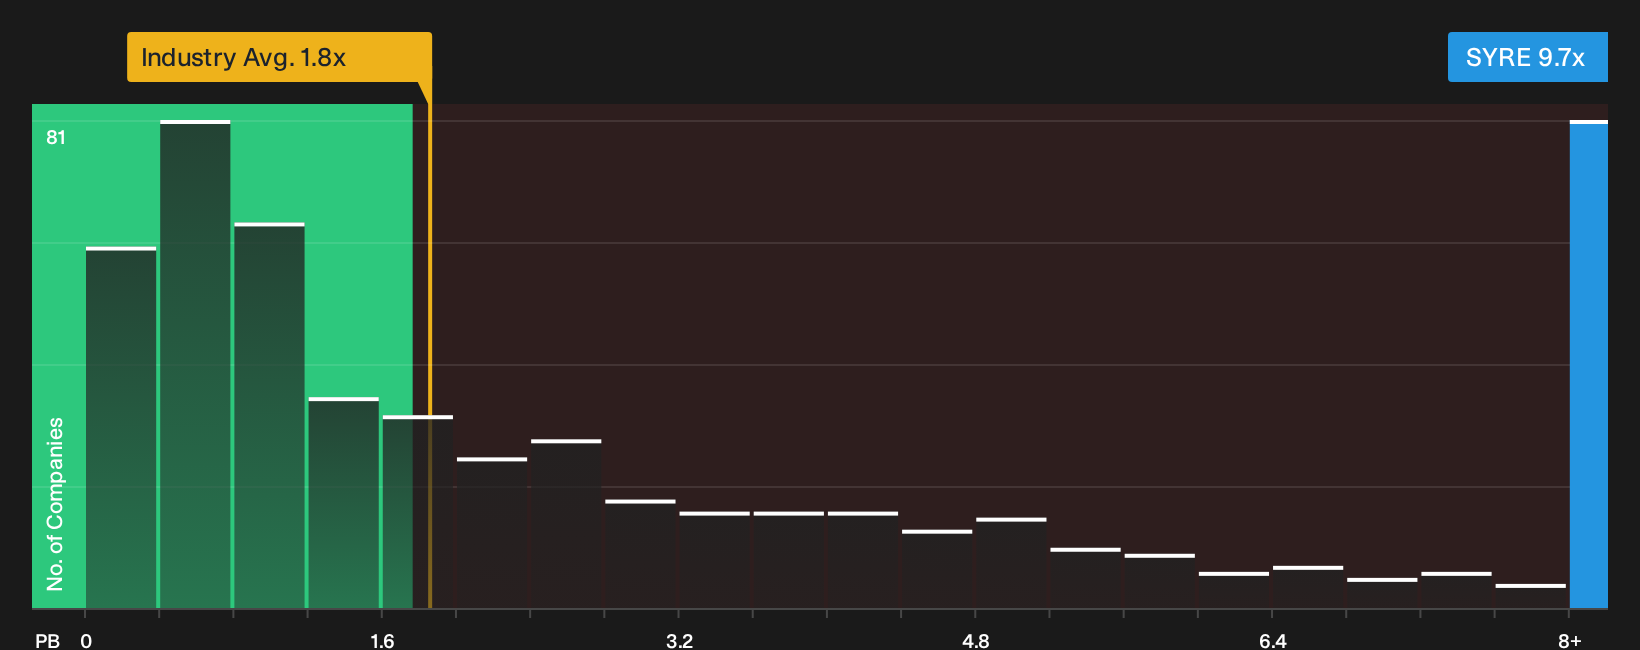
The analyst narrative paints Spyre Therapeutics as roughly 17% undervalued on a fair value of about $120 per share. The market is telling a different story. On a P/B of 9.7x versus 1.8x for the broader US Biotechs group, the stock carries a very rich premium.
Peer comparisons soften that picture a little, since similar companies trade around 10.7x P/B. Even so, buying into a valuation this far above the wider industry leaves less room for error if trials slip or sentiment turns. Are you comfortable paying up so heavily for a pipeline that is still pre revenue and loss making?
Before leaning on this type of comparison, it helps to see how the story looks through profit based ratios and other valuation checks in our See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Spyre Therapeutics stacks up against the sector on this metric, review the latest chart in
Next Steps
Mixed signals on Spyre Therapeutics so far. If you want to move sooner rather than later, consider both sides of the story in our 1 key reward and 5 important warning signs.
Looking for more investment ideas beyond Spyre Therapeutics?
If Spyre Therapeutics has your attention, do not stop there. Cast a wider net now so you are not relying on a single high risk biotech story.
- Target resilient compounding by checking companies with strong fundamentals and robust finances in the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by scanning the 34 high quality undervalued stocks that pair quality metrics with discounted market prices.
- Prioritise stability by reviewing companies with resilient risk profiles in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com