
How Investors May Respond To Lam Research Stock After In Line Guidance
- Lam Research reported first quarter fiscal 2027 sales of US$8.22b and net income of US$2.75b, with diluted EPS of US$2.19 from continuing operations. The company also issued December quarter revenue guidance of US$8.6b plus or minus US$400m, with expected net income per diluted share of US$2.33 plus or minus US$0.15.
- The business paired record quarterly performance with warnings on weaker China related revenue and ongoing component shortages, highlighting how near term supply and regional demand pressures can sit alongside a larger wafer fab equipment opportunity and an expanding installed base for Lam Research.
- Next comes a look at how Lam Research's record quarter, combined with cautious guidance on China and supply constraints, might reshape its investment narrative.
Compare how Lam Research's setup after this record quarter stacks against other chip related opportunities by scanning our hand picked 53 AI infrastructure stocks.
Lam Research Investment Narrative Recap
To own Lam Research, you need to be comfortable with a wafer fab equipment cycle tied heavily to AI, new Tier 1 fabs and more complex 3D chip architectures. The recent record quarter and December guidance keep that big picture intact, while pointing to component tightness and China exposure as practical constraints rather than thesis breakers.
The key near term swing factor is whether Lam Research converts strong demand into shipments as supply bottlenecks and export controls bite. The biggest risk still sits in China related limits and mix shift, which could add lumpiness if non China fab ramps slow or customer timing changes.
The earnings guidance for the December 2026 quarter, calling for US$8.6b revenue plus or minus US$400m and net income per diluted share of US$2.33 plus or minus US$0.15, is the clearest operational reference point right now. It anchors expectations around what Lam Research can ship while component shortages and export rules are in effect.
For catalysts, that range frames how quickly delayed tools might move into later quarters and how effectively the business offsets lower China contribution with US, Korea, Taiwan and other regions. It also gives you a way to track execution against management’s wider wafer fab equipment opportunity and the growing installed base services story.
Lam Research's analyst narrative centers on projected revenues of US$49.9b and earnings of US$18.5b by 2029, based on assumed yearly revenue growth of 24.1% and an earnings increase of about US$10.1b from US$8.4b today.
Uncover why Lam Research's fair value indicates a 58% potential upside to its current price, which could narrow quickly.
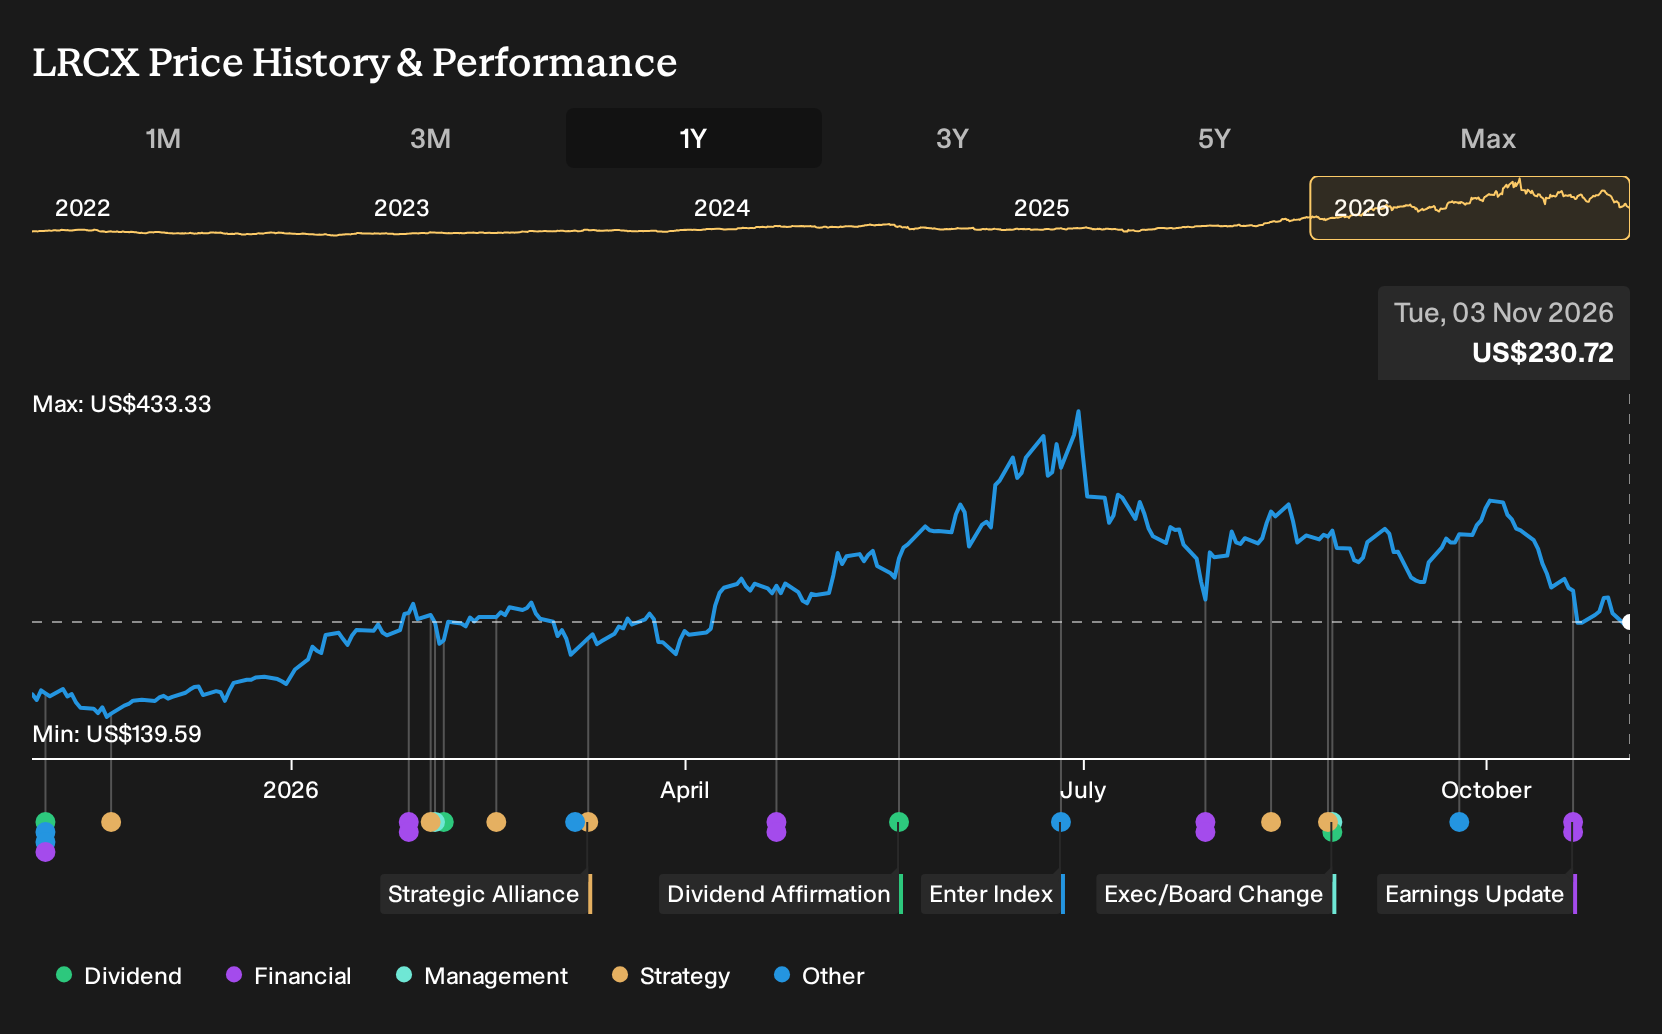
Exploring Other Perspectives
Some of the most optimistic analysts frame a different catalyst for Lam Research. They focus on compressed NAND conversion and advanced packaging demand, where their October 2026 models were already penciling in US$57.7b of revenue and US$23.7b of earnings by 2029. Those projections came before this record quarter, so expectations may evolve and vary widely.
Explore 8 other Lam Research fair value estimates, including one that suggests there could be as much as 107% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lam Research research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lam Research. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lam Research's overall financial health at a glance.
Looking For More Ideas Beyond Lam Research?
If the Lam Research story has sharpened your thinking about where to put fresh capital, use this as a springboard to size up other opportunities with the Simply Wall St Screener before you commit more money to a single chip related play.
- If you prefer companies with meaningful income streams and higher yields that might help smooth out volatility over time, scan through 4 dividend fortresses to see which ones fit that brief.
- If resilience and balance sheet strength sit at the top of your checklist, start with the list of solid balance sheet and fundamentals (24 results) to narrow the field to businesses with sturdier financial foundations.
- For investors hunting for less crowded opportunities backed by solid fundamentals, take a look at our 19 high quality undiscovered gems and see which tickers deserve a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com